A Malibu-to-Surfside move calls for more than a comparison of property taxes and monthly dues. Evaluate the full ownership budget, distinguish service charges from gratuities, and assess the building’s reserve schedule before choosing a residence.
Moving from Malibu to Surfside can change more than the coastline outside the window. For a buyer exchanging a standalone house for a condominium, it also changes how ownership is managed and billed. Individually arranged maintenance may give way to association payments, while service charges and shared capital commitments demand a different budgeting discipline.
The right comparison is not a Malibu property-tax bill against a Surfside monthly association payment. It is the complete annual cost of each residence, considered alongside the cash required over the intended holding period. A lower recurring payment is not necessarily preferable if substantial capital spending falls outside it.
Separate the relocation decision from the property-type decision. Some differences reflect California versus Florida; others reflect private-house ownership versus shared-building ownership. Keeping those distinctions clear makes the financial comparison more useful.
For a new Malibu purchase, preliminary tax estimates cluster around 1.2% of purchase price, with approximately 1.22% used as a planning figure. These are starting points, not parcel-specific quotations. Under a separate illustrative assumption of 1.15%, a $4.5 million purchase produces $51,750 in annual property tax.
An existing owner’s bill can be a misleading benchmark. California’s Proposition 13 generally limits annual assessed-value growth to 2%, but that protection does not give a new buyer the seller’s historic assessment. A longtime Malibu owner considering a move should distinguish the actual cost of keeping that home from the estimated cost of buying another.
Surfside requires a different distinction: municipal millage is not total millage. The town’s adopted FY 2025 operating rate was 4.0000 mills, or $4 per $1,000 of taxable value. Its town-level voted-debt rate was zero, but overlapping county, school and other taxes still applied.
The 2025 combined Surfside figure was 18.6245 mills, equivalent to 1.86245% of taxable value. These are historical 2025 benchmarks, not verified current rates. Nor should taxable value automatically be equated with purchase price. Obtain a buyer-specific estimate using the applicable assessment assumptions and current rates before comparing residences.
Organize each candidate property into the same categories: property taxes, insurance, association operations, reserve contributions, special assessments, private maintenance and service spending. Keep financing costs separate so the property comparison does not shift with the borrowing structure.
A Malibu house may require individual budgets for landscaping, pool maintenance and housekeeping. Some properties also carry HOA dues or Geologic Hazard Abatement District assessments. Insurance warrants a current, property-specific quote rather than an extrapolation from an old premium.
For a Surfside condominium, annualize the association payment, then identify what it includes. If reserve contributions are already embedded in dues, show them as a component, not an additional expense. Ask which insurance costs fall within the association budget and which require separate owner coverage.
When considering Arte Surfside, start with the unit’s actual payment obligations. Request the budget breakdown and identify which household services would remain privately arranged. The aim is to compare equivalent responsibilities, not merely equivalent purchase prices.
Keep confirmed assessments separate from recurring expenses, showing both their total amount and payment timing. A manageable annual average can conceal a concentrated cash requirement.
Service is part of the appeal, but access to an amenity does not establish that every use is included. Request written schedules for any valet, beach service, dining, club access or other amenity relevant to the residence under consideration.
Sort those services into three categories: services included in ownership payments, mandatory charges outside those payments, and optional spending. Ask whether any minimums, guest charges or usage-based fees apply. The answers should come from the property’s documents, not assumptions about Surfside generally.
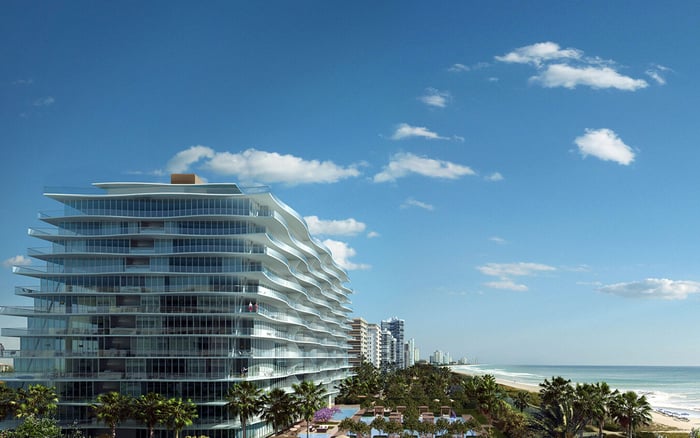
For a residence under consideration at The Surf Club Four Seasons Surfside, establish that distinction in writing before estimating annual service spending. Do not infer the unit’s obligations from a brand name or a description of the lifestyle.
Gratuities belong on a separate line. Confirm whether a billed service charge includes a gratuity before budgeting an additional tip. Do not assume a universal tipping rate. Set a discretionary allowance based on your household’s expected usage, and keep voluntary holiday giving distinct from mandatory fees.
The monthly payment describes today’s collection, not necessarily tomorrow’s capital needs. A Structural Integrity Reserve Study, or SIRS, evaluates major building components and projected funding requirements. Read it alongside association financials, reserve schedules, milestone inspection findings and planned assessments.
For Fendi Château Residences Surfside, as for any candidate property, request the applicable documents rather than presuming a funding position from the property’s presentation. Establish what work is anticipated, when funds are needed, and what share of that funding the proposed purchase would carry.
Model reserve growth from the building’s documented schedule, rather than applying a uniform annual increase to all dues. Separate changes in operating expenses from increases in reserve contributions. Then identify capital work funded through an assessment or another payment obligation, taking care not to count the same cost twice.
A larger reserve balance alone does not settle the question. Evaluate it against projected needs and timing. Likewise, a lower monthly payment is not evidence of a lower long-term burden. Have qualified advisers confirm the requirements applicable to the building; do not assume that a single funding rule or deadline covers every purchase.
Prepare a first-year cash budget and a forward schedule covering your intended holding period. Show recurring obligations, documented changes, assessment installments and discretionary services separately. Where future figures remain uncertain, label each planning allowance as an assumption rather than a quoted expense.
For Ocean House Surfside, the same discipline applies: establish which figures are adopted obligations and which are projections before relying on an annual total. Use the documents applicable to the purchase rather than importing another building’s costs.
Model your own occupancy pattern. A household using services regularly should budget differently from one planning occasional stays, while fixed ownership obligations should remain visible in either case. Keep a personal liquidity cushion distinct from the association’s reserves; it is financial preparation, not another building charge.
The strongest property decision aligns the residence with both daily expectations and future commitments. Compare the verified annual budget, capital-payment schedule and service arrangements together. The objective is not simply the smallest monthly bill, but a level of ownership cost and uncertainty you are comfortable with throughout the holding period.
For a discreet conversation about your Malibu-to-Surfside property search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationBuild a complete annual budget for each property, separating taxes, insurance, association payments, private maintenance and services. Distinguish location differences from house-versus-condominium differences.
Not as a new-purchase estimate. Proposition 13 generally limits annual assessed-value growth to 2%, but a new buyer does not inherit the seller’s historic assessment.
Preliminary estimates cluster around 1.2% of purchase price, with approximately 1.22% used as a planning figure. Obtain a parcel-specific estimate before relying on that assumption.
No. That FY 2025 operating rate covered the town levy, not overlapping county, school and other taxes.
Not automatically: 18.6245 mills equals 1.86245% of taxable value, which may differ from purchase price. The 2025 figure is historical, so confirm current rates and buyer-specific assessment assumptions.
Show reserve contributions as a component of dues rather than adding them again. Separately identify any additional assessment obligations.
Review association financials, reserve schedules, applicable SIRS findings, milestone inspection documentation and planned assessments. Together, they help clarify capital needs beyond the advertised monthly payment.
Keep them separate and confirm whether a service charge already includes a gratuity. Obtain written fee schedules and treat discretionary tipping as a household allowance.
No. Use the building’s documented operating budget, reserve-funding schedule and planned capital work rather than assuming a uniform increase.
Not necessarily. Compare included services, reserve contributions and separate capital obligations before judging the full ownership burden.