A seller-financed luxury condominium purchase requires separate scrutiny of ownership documents, association replacement-cost valuations, interior coverage, and ordinance-or-law protection. A current appraisal is a starting point, not a guarantee against underinsurance.
In a seller-financed luxury condominium purchase, the ownership arrangement and insurance review belong in the same closing conversation, but answer different questions. Title and financing documents address ownership and the seller’s security. A replacement-cost appraisal addresses the cost of reconstructing the property to be insured. Neither substitutes for the other.
For a buyer considering The Residences at 1428 Brickell, the meaningful distinction is not between an impressive purchase price and an impressive policy limit. It is among the property interests being acquired, the components being insured, and the obligations established by the transaction documents. This is a diligence framework, not a statement about any particular residence’s insurance or financing availability.
Before selecting an ownership vehicle or finalizing seller-financing terms, ask legal counsel to address title, security, and the treatment of insurance proceeds separately. Ask the insurance adviser to explain insured property, exclusions, deductibles, and endorsements. An appraisal cannot resolve those legal questions or guarantee coverage for a future claim.
Replacement-cost valuation estimates reconstruction costs, not the amount a buyer would pay for a residence. It is not the condominium’s resale value, tax assessment, purchase price, or seller-financed loan balance. Keeping these figures distinct prevents a negotiated transaction price from becoming an inappropriate insurance benchmark.
Florida condominium associations must determine the replacement cost of insured property at least once every 36 months, using an independent insurance appraisal or an update to a previous appraisal. Before closing, obtain the latest appraisal or update and check its valuation date against that interval.
The appraisal also matters to underwriting: insurers may require a full replacement-cost appraisal when an association applies for coverage. Its practical value extends beyond establishing a date on a compliance calendar.
Read the valuation alongside the policy’s insured-property description and limits. The question is whether the valuation and coverage address the same property-not whether the appraisal resembles the unit’s asking price. A current valuation provides a useful foundation, but exclusions and policy terms remain material.
The association’s master policy and the owner’s individual policy cover different property interests. For a luxury buyer, that boundary is essential: a substantial interior investment can fall outside the association’s property coverage.
Florida’s statutory exclusions include floor, wall, and ceiling coverings located within a unit and serving only that unit. Other listed exclusions include electrical fixtures, appliances, water heaters, water filters, built-in cabinets, countertops, and window treatments located within and serving only one unit.
A master policy described as providing full replacement cost should therefore not be assumed to insure specialty flooring, upgraded cabinetry, stone countertops, appliances, or window treatments. The phrase describes a valuation approach; it does not erase the boundary between association-insured and owner-insured components.
For a Miami Beach buyer considering The Perigon Miami Beach, the question is the same as for any condominium purchase: which interior components require separate unit-owner protection? The project name is not evidence of coverage. The actual policy and residence must guide the review.
A separate finish inventory is a sensible diligence recommendation, not an additional statutory mandate. Record the components that fall outside association coverage, then have the insurance adviser evaluate the appropriate unit-level valuation and protection.
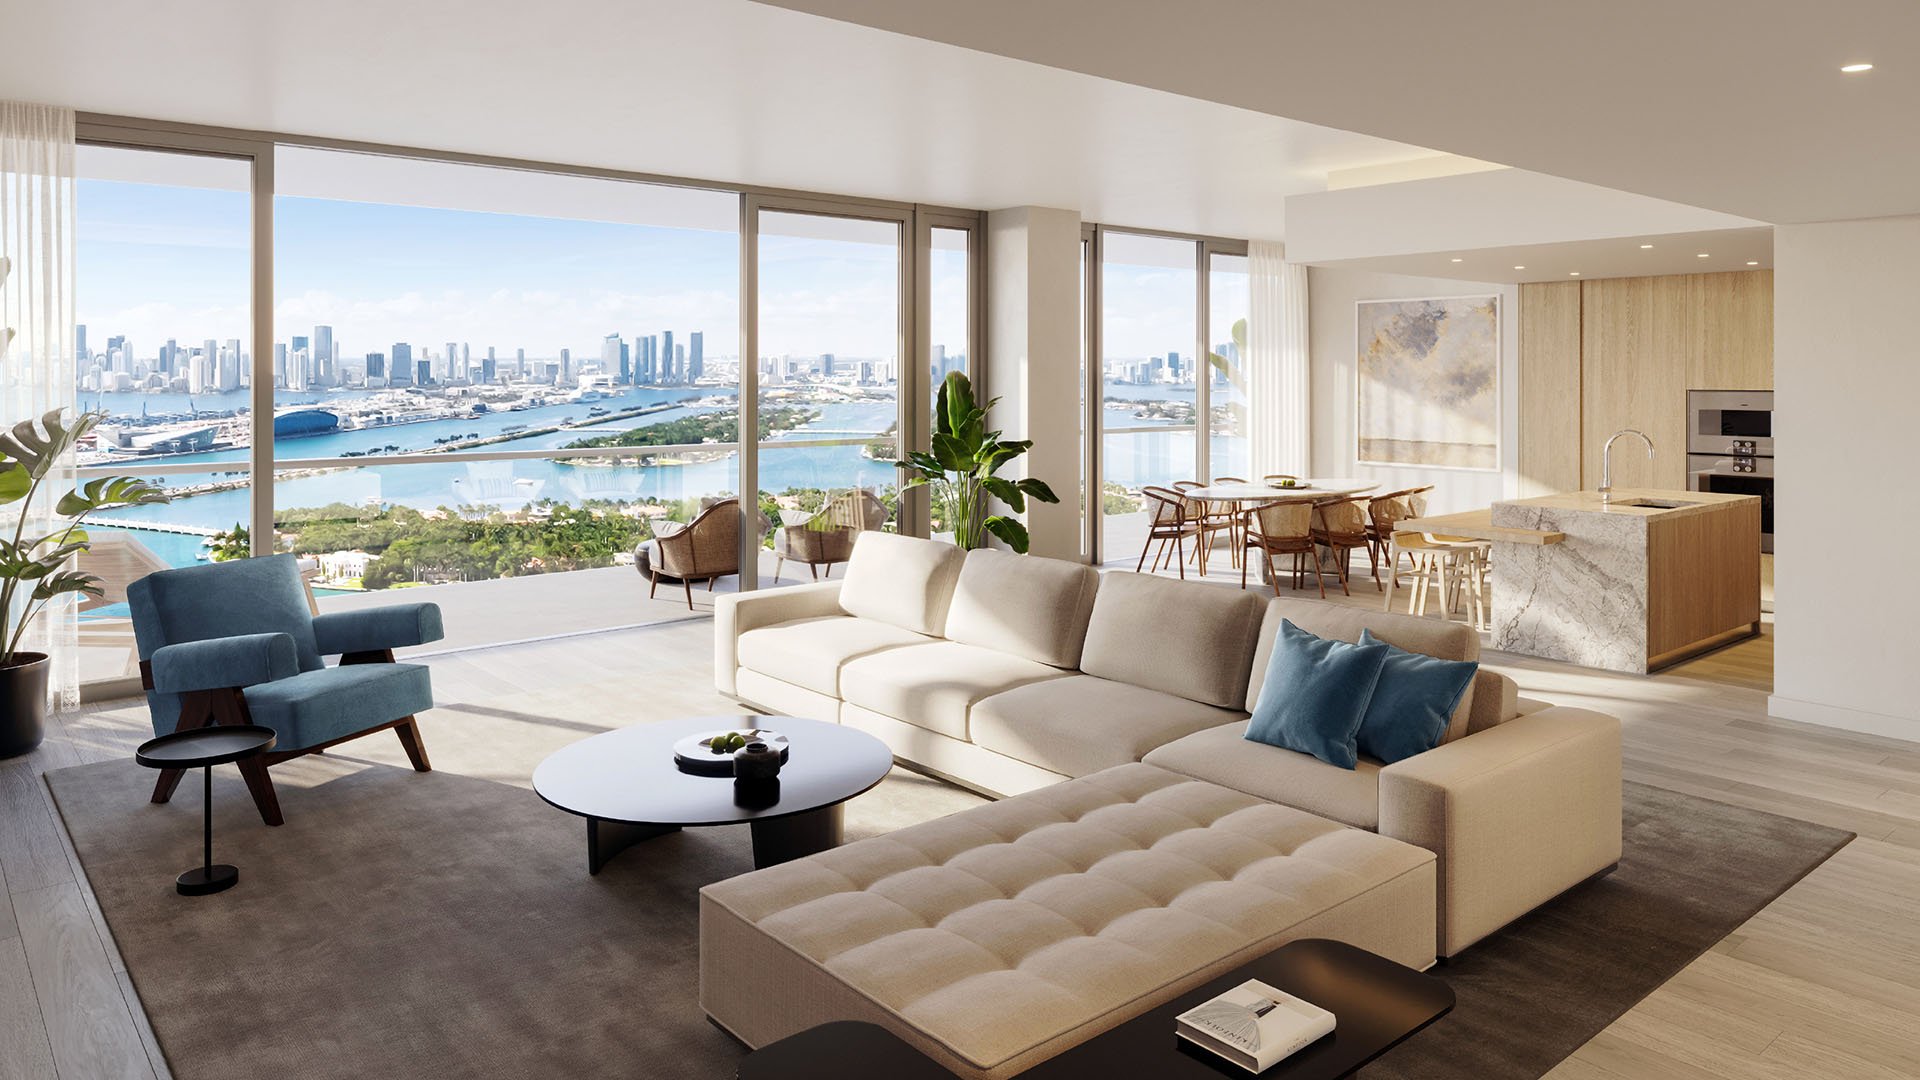
The inventory should distinguish floor coverings, wall and ceiling treatments, cabinetry, countertops, fixtures, appliances, and window treatments. Available specifications and improvement documentation can make that review more precise. The objective is to identify what would need to be replaced-not to use the residence’s overall purchase price as a proxy for its interior value.
A buyer evaluating Jade Signature Sunny Isles Beach should apply this review to the particular unit and its actual improvements. The diligence remains unit-specific, even when the association has a current replacement-cost appraisal.
Ask for a clear explanation of how the proposed owner’s policy addresses the inventoried components. An updated association valuation cannot eliminate a unit-level gap created by an excluded finish or equipment category. Review both layers independently, then consider them together.
Reconstruction and compliance are related, but they are not identical costs. Ordinance-or-law coverage addresses the additional costs of meeting applicable laws and ordinances when repairing or replacing insured property after a covered loss.
Florida’s dwelling-coverage provision allows additional ordinance-or-law costs to be limited to 25% or 50% of the dwelling limit, depending on the policyholder’s selected coverage. It applies coverage to repairs of the damaged portion unless total damage exceeds 50% of the structure’s replacement cost.
Those percentages and that damage threshold are not universal terms of every condominium master policy. The applicable policy form, endorsements, and statutory scope require review. A percentage without its coverage context is not a reliable basis for a closing decision.
When considering Fendi Château Residences Surfside, ask the insurance adviser to identify the applicable ordinance-or-law terms rather than infer protection from a replacement-cost description. Focus on what the relevant policies actually provide, including their limits and conditions.
A disciplined closing file should connect the insurance documents without confusing them with the ownership documents. Request the association’s latest replacement-cost appraisal or update, the master policy, and relevant endorsements. Separately, review the proposed unit-owner policy and interior inventory.
Use those materials to answer three practical questions. Is the association valuation within the required interval? Do the insurance limits adequately reflect reconstruction costs for the property being insured? Are excluded unit components and applicable ordinance-or-law costs addressed by the appropriate coverage?
These document requests and comparisons are diligence recommendations, not new statutory requirements. Legal counsel should separately review the proposed ownership and seller-financing arrangement. Do not assume that the insurance valuation establishes who holds title, how the seller’s lien is secured, or how proceeds must be distributed.
Underinsurance arises when limits do not adequately reflect reconstruction costs. A replacement-cost valuation helps establish an appropriate basis, but a current date alone does not establish adequate protection. The scope of insured property and the treatment of interiors remain equally important.
The strongest review keeps four questions distinct: what is owned, what is insured, what it would cost to reconstruct, and which policy terms govern a covered loss. Bringing those answers together creates a more informed closing conversation without asking an appraisal to do the work of a policy or legal document.
For a considered perspective on South Florida luxury residences, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAt least once every 36 months, using an independent insurance appraisal or an update to a previous appraisal.
No. Replacement cost estimates reconstruction costs for the property to be insured, not purchase price, resale value, tax assessment, or the seller-financed balance.
No. It does not establish who holds title, how the seller’s lien is secured, or how insurance proceeds must be distributed.
It should not be assumed to include excluded unit interiors. The association policy and unit-owner policy cover different property interests.
Listed exclusions include unit-only floor, wall, and ceiling coverings, electrical fixtures, appliances, water heaters, water filters, built-in cabinets, countertops, and window treatments.
The inventory is a diligence recommendation, not an additional statutory mandate. It helps identify components that need separate unit-level insurance review.
It addresses additional costs needed to meet applicable laws and ordinances when repairing or replacing insured property after a covered loss.
No. Those figures relate to the cited dwelling-coverage provision; the applicable policy form, endorsements, and statutory scope must be reviewed.
No. Insurance limits must adequately reflect reconstruction costs, and unit-level exclusions can leave separate coverage gaps.
As diligence, request the latest association appraisal or update, the master policy and relevant endorsements, and the proposed unit-owner policy. Review these alongside an inventory of interior improvements.