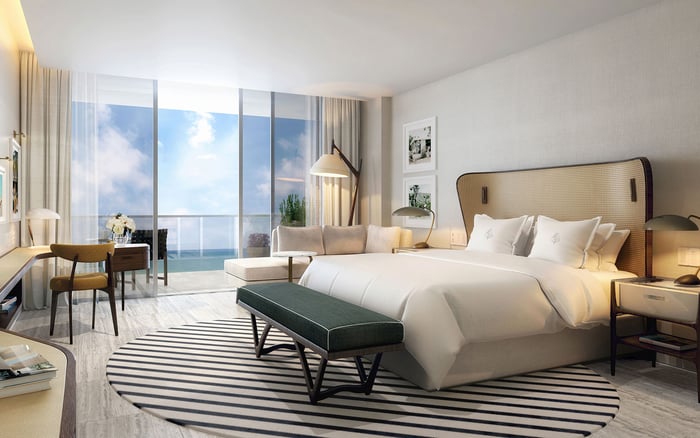
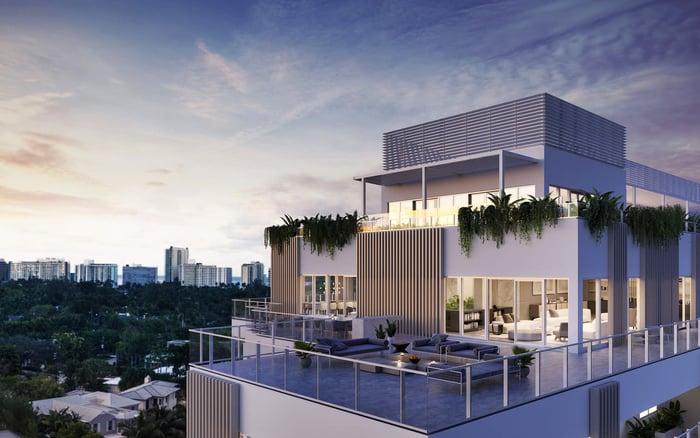
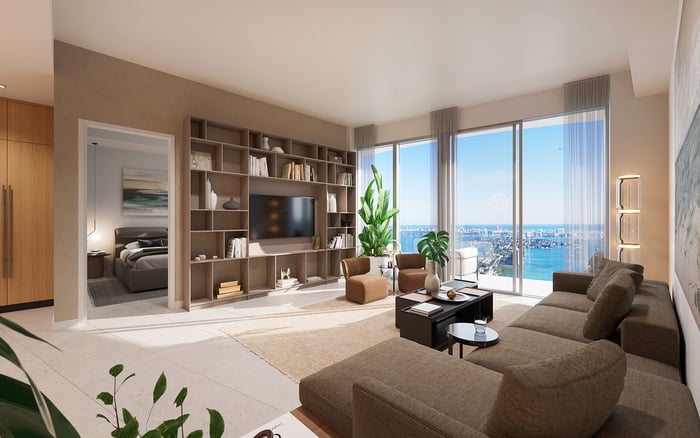
A seasonal second-home purchase calls for alignment between ownership structure, mortgage classification, and closing liquidity. This guide explains how to reconcile the Closing Disclosure, evaluate points and lender credits, and separate prepaids from escrow deposits without confusing seasonal use with Florida homestead eligibility.
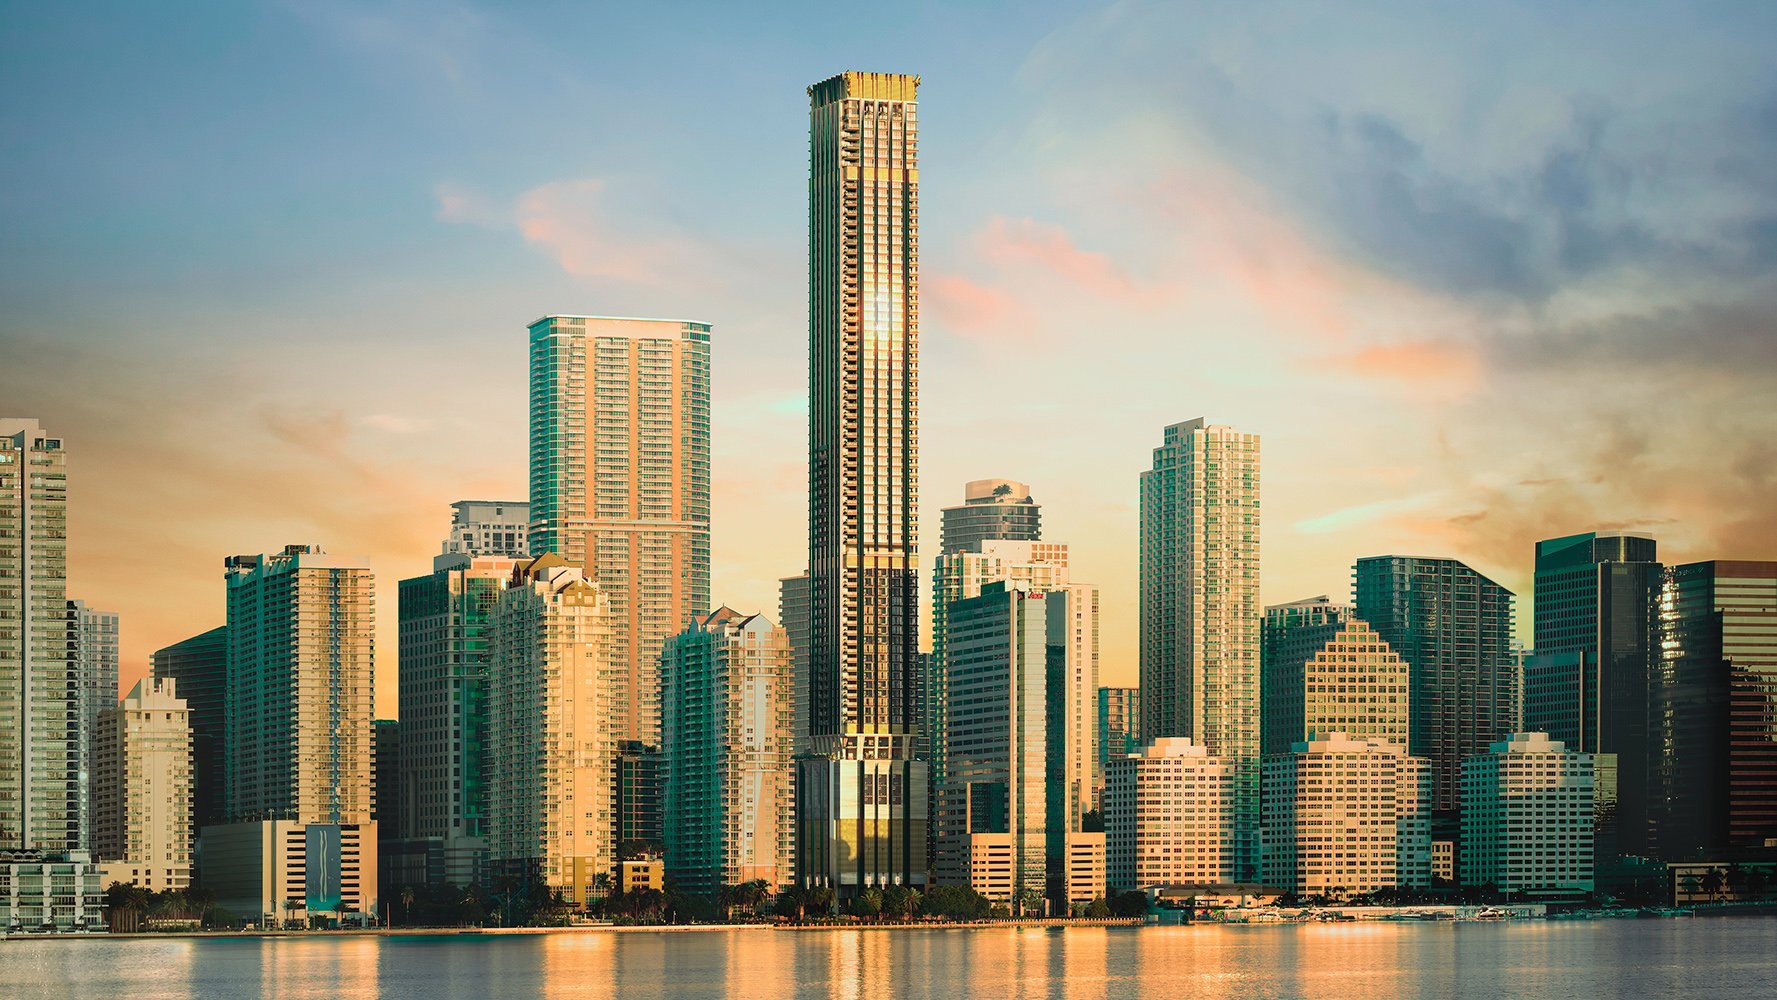
A South Florida second home should bring ease to the calendar, not ambiguity to the balance sheet. Before reviewing final settlement figures, a seasonal buyer should separate three decisions: who will hold title, how the lender will classify the property, and how much liquidity closing will require. These decisions intersect, but none substitutes for another.
Whether considering The Residences at 1428 Brickell in Brickell or a residence elsewhere in South Florida, the prudent sequence remains the same: establish intended use, review the proposed ownership vehicle with counsel, and confirm its acceptability with the lender. A structure that serves an estate plan should not be assumed to satisfy mortgage requirements.
The Closing Disclosure is the financial checkpoint. It summarizes final loan terms, projected payments, closing costs, and Cash to Close. For the buyer, its purpose is not simply to identify a transfer amount. It is to make every material difference from the latest Loan Estimate understandable.
Under the qualifying conventional second-home framework described here, the property must be occupied by the borrower for part of the year, consist of one unit, and be suitable for year-round occupancy. It must remain under the borrower’s exclusive control, rather than operate as a timeshare or under an agreement that gives a management company control over occupancy.
These requirements are program-specific, not universal rules for every luxury mortgage. A property that falls outside them may require investment-property financing. Rental income does not automatically disqualify a second home, but generally cannot be used to qualify the borrower within this framework.
For a Miami Beach buyer evaluating The Perigon Miami Beach, the question extends beyond how many weeks the owner expects to visit. The intended occupancy and any management arrangement must align with the selected loan program. A project name alone establishes neither eligibility nor acceptable use.
Portfolio owners should also distinguish closing funds from required reserves. The applicable automated-underwriting framework permits up to 10 financed properties, subject to eligibility requirements, with additional reserve requirements tied to financed-property holdings. Confirm the rules for the financing selected.
Personal ownership, a revocable trust, and an LLC are not interchangeable choices. Their suitability requires review of the buyer’s objectives and specific circumstances, alongside the lender’s title requirements. Homestead compatibility alone does not establish mortgage eligibility for either a trust or an LLC.
Florida’s homestead property-tax exemption generally requires the property to be the owner’s permanent residence or the permanent residence of the owner’s dependent. Seasonal occupancy alone should not be treated as establishing eligibility. A revocable trust may qualify as an ownership vehicle for homestead purposes, whereas an LLC generally does not. Ownership and residence facts still require legal review.
For someone considering Alina Residences Boca Raton in Boca Raton, this distinction matters before tax assumptions enter the budget. A second-home mortgage designation is not a homestead determination. Ask counsel to assess the proposed title structure and residence facts, while the lender separately confirms financing requirements.
Begin with the loan itself. Compare the loan amount, interest rate, monthly payment, and closing costs with the most recent Loan Estimate. Ask the lender to explain discrepancies; do not treat the final disclosure as self-explanatory.
Then review the transaction accounting. Confirm the purchase price, deposits already paid, seller credits, and adjustments for items such as property taxes and association charges. The “Calculating Cash to Close” section helps identify changes between estimated and final figures. Read it alongside the detailed charges, not as a substitute for them.
Cash to Close is the amount payable at closing in addition to money already paid. It differs from total closing costs because it also incorporates the down payment, deposits, credits, and transaction adjustments. A change in this figure does not necessarily mean lender fees increased.
For a West Palm Beach purchase at Forté on Flagler West Palm Beach, apply the same discipline: match deposit entries to payments already made, then reconcile credits and adjustments with the transaction documents. The residence may be distinctive; the accounting should remain transparent.
Discount points are upfront charges paid to obtain a lower mortgage interest rate. Distinguish them from other origination fees. Lender credits generally represent the opposite choice: reduced upfront closing costs in exchange for a higher rate.
Neither option is inherently preferable. Compare liquidity retained today with interest expense over the expected life of the loan. Request comparable pricing alternatives so that a lower Cash to Close does not obscure a higher ongoing payment.
A simple screening calculation for points is:
Break-even months = upfront cost of points ÷ monthly principal-and-interest savings.
This calculation is a starting point, not a complete analysis. It does not fully account for refinancing risk or the time value of money. Consider the expected mortgage holding period, not only how long the residence will remain in the family.
Keep seller credits separate from lender credits. They have different sources and appear separately in the transaction accounting. A lender credit is a financing tradeoff, not a reduction in the home’s purchase price.
Prepaids commonly include interest from closing through the end of the month and the first year’s homeowners-insurance premium. Prepaid interest depends on the closing date, so a scheduling change can alter the amount collected at settlement.
Initial escrow payments fund the account used for future property-tax and insurance payments. They are not lender origination charges. Prepaids, escrow deposits, loan fees, and the down payment all affect closing liquidity, but they should remain separate categories in the buyer’s review.
If the closing date changes, ask which figures changed with it. The goal is an explained adjustment, not simply a revised total.
Before authorizing closing funds, confirm that intended use, proposed title, and financing classification remain aligned. Recheck final loan terms, points or lender credits, prepaids, escrow funding, deposits, seller credits, and transaction adjustments. Keep required reserves distinct from the funds payable at settlement.
A well-prepared seasonal acquisition leaves the buyer with a clear ownership structure and a fully understood closing balance-not assumptions carried into the first season.
Explore South Florida residences with MILLION as you refine your second-home acquisition plans.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIt summarizes final loan terms, projected payments, closing costs, and Cash to Close. Compare it with the most recent Loan Estimate and ask the lender to explain discrepancies.
No. Cash to Close also reflects the down payment, deposits already paid, credits, and transaction adjustments.
In the conventional framework discussed here, it must be a one-unit, year-round residence occupied by the borrower for part of the year and under the borrower’s exclusive control. Requirements depend on the selected loan program.
No, but generally it cannot be used to qualify the borrower within the framework described. Intended use and occupancy arrangements must still meet the program’s requirements.
They reduce upfront closing costs and are typically exchanged for a higher interest rate. They do not reduce the purchase price.
Divide the upfront cost of points by monthly principal-and-interest savings for a simple break-even estimate. This screening calculation does not fully address refinancing risk or the time value of money.
Prepaid interest depends on the closing date and commonly covers the period from closing through month-end. A date change can therefore alter the amount collected.
No. They fund an account for future property-tax and insurance payments and should be reviewed separately from origination charges.
No. Eligibility generally depends on the property being the permanent residence of the owner or the owner’s dependent, not merely a seasonal retreat.
No. A revocable trust may be compatible with homestead ownership requirements, whereas an LLC generally is not, but mortgage title requirements require separate confirmation with the lender and counsel.