
A disciplined framework for funding a South Florida branded residence, separating association charges, taxes, insurance, private staffing, hospitality services, and assessment liquidity while keeping ownership decisions grounded in property-specific advice.
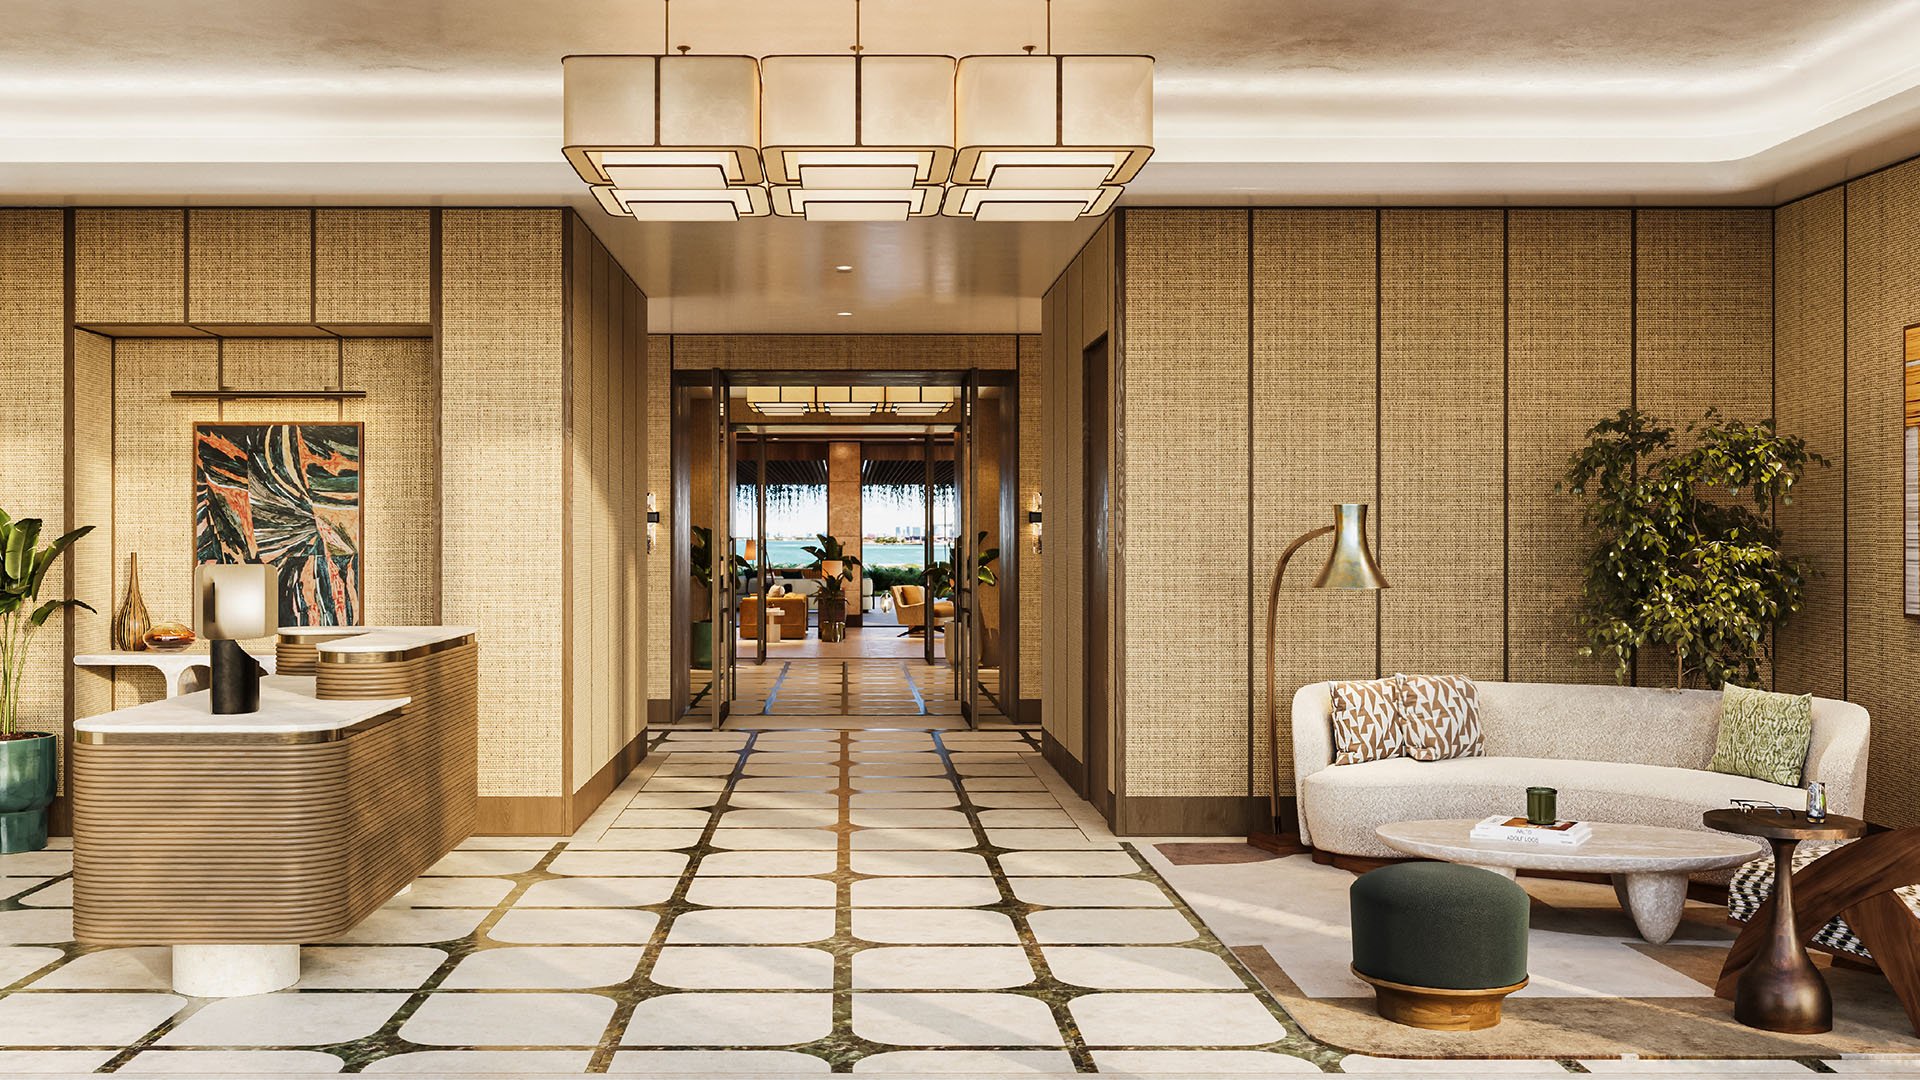
The appeal of a branded residence is effortless living. The financial structure behind it deserves equal consideration. For a South Florida condominium with hotel services, the question is not simply how much the monthly assessment costs, but what annual funding will sustain the owner's intended lifestyle-without confusing included services with separately billed privileges.
A useful ownership budget separates seven categories: association assessments, property taxes, unit insurance, mandatory service charges, private staffing, usage-based hospitality services, and an irregular-assessment contingency. Each deserves its own line, even when several flow through the same payment account. The objective is clarity, not an artificially precise total assembled from market averages.
Treat the choice of individual, LLC, trust, or partnership ownership as a legal and tax question distinct from the residence's operating budget. Do not select a structure on the assumption that it automatically lowers carrying costs or preserves homestead eligibility. Have counsel and tax advisers confirm the proposed arrangement's implications before relying on exemptions or estimated savings.
Alongside that decision, establish a practical funding protocol: who pays association assessments, who authorizes discretionary services, and how irregular expenses will be funded. A year-round household and a seasonal residence may require different service budgets even when their fixed property obligations are similar.
For a buyer considering Waldorf Astoria Residences Downtown Miami, the Downtown Miami address and brand should begin the inquiry, not determine the budget. Request the applicable unit assessment and written service terms rather than attaching a generic hospitality premium to the purchase price.
Review the association budget for common-area and structural insurance, maintenance, management, security, trash collection, reserves, and any included utilities or amenities. Use the declaration and operating documents to confirm the actual allocation rather than assuming that hotel-level staffing or services are included.
Annualize the applicable unit assessment, then identify any mandatory charges billed outside it. Keep taxes, unit insurance, separately billed services, and private staffing visible as distinct expenses. A broad branded-residence cost range is not a substitute for the property's own budget.
When evaluating Four Seasons Hotel & Private Residences Fort Lauderdale, frame the Fort Lauderdale comparison around three questions: what is funded collectively, what is mandatory but billed separately, and what becomes payable only when used?
Do not use the seller's property-tax bill as a forecast of the buyer's future liability. Ask advisers to build the estimate around projected taxable value and applicable millage, accounting for reassessment, assessment limits, municipality, and any confirmed exemptions.
Do not assume homestead savings for a non-primary residence or an ownership arrangement whose eligibility remains unconfirmed. Confirm exemption eligibility and application requirements with advisers and the relevant county property appraiser. Base the tax reserve on an unexempted estimate until any assumed benefit has been validated.
Do not treat the association's insurance as a substitute for a unit-level coverage review. Compare the master policy with proposed owner coverage to establish responsibility for interior finishes, improvements, contents, and relevant deductibles or exclusions.
Obtain a quote addressing the actual residence and its contents. Ask the insurance adviser to evaluate high-value interiors, coverage limits, deductibles, and flood or wind exposure rather than relying on a generic annual allowance.
The distinction is especially useful when considering a Miami Beach residence such as Setai Residences Miami Beach. Evaluate the insurance allocation independently of the service experience. Neither branding nor a substantial association assessment establishes what the owner's policy must cover.
Hotel-level staffing funded through association charges is not the same expense as a private housekeeper or a separately billed hospitality service. Housekeeping, room service, valet, spa treatments, transportation, and in-residence dining should not automatically be treated as included in dues. Confirm availability, inclusions, and pricing in writing.
For optional services, estimate expected use against the applicable service schedule. Separate recurring arrangements from occasional requests, and identify any mandatory charges before classifying the remainder as discretionary. A seasonal owner's service assumptions should reflect actual occupancy and intended use, rather than defaulting to a year-round pattern.
Private staffing requires employment-cost estimates or vendor proposals. Avoid a percentage allowance unsupported by the household's requirements. Above all, check that a service is not budgeted twice: once within association-funded operations and again as an assumed private expense.
Review the association's reserve funding for capital expenditures and deferred maintenance with qualified advisers. Confirm which contributions are already included in dues and what obligations apply to the building. An owner's additional liquidity buffer is a separate decision, not another payment of the same reserve contribution.
Size that contingency around the building's documented financial position and the owner's funding capacity rather than an unsupported percentage of dues. Budget known assessments and identified capital needs directly, keeping them separate from cash retained for uncertain expenses.
Before finalizing the annual funding plan, review the declaration, bylaws, current budget, financial statements, reserve studies, applicable inspection reports, and pending assessment notices. Then separate expected annual spending from cash retained for uncertainty. That distinction makes an ownership budget useful: it funds the lifestyle while keeping the building's financial demands in view.
For a considered approach to South Florida branded-residence ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationSeparate association assessments, property taxes, unit insurance, mandatory service charges, private staffing, usage-based hospitality services, and an irregular-assessment contingency.
Annualize the applicable unit assessment using the property's budget and identify any mandatory charges billed separately. Do not substitute a broad branded-residence cost range for unit-specific figures.
Do not assume they are included. Confirm availability, written service schedules, and inclusions before budgeting housekeeping, dining, valet, spa treatments, or transportation.
Do not use it as a forecast of future liability. Ask advisers to estimate taxes using projected taxable value and applicable millage, accounting for reassessment, assessment limits, municipality, and confirmed exemptions.
No automatic eligibility should be assumed. Confirm the proposed arrangement with advisers before budgeting homestead savings, particularly for a non-primary residence.
No. Compare the master policy with proposed owner coverage to identify responsibility for finishes, improvements, contents, deductibles, and exclusions.
Obtain employment-cost estimates or vendor proposals based on the household's requirements. Keep private staffing separate from association-funded staff and separately billed hotel services.
No. Association reserve contributions may already be included in dues, while an owner's liquidity buffer is additional cash retained for irregular obligations.
Use the building's documented financial position and the owner's funding capacity rather than an unsupported percentage of dues. Budget known assessments and identified capital needs separately.
Review the declaration, bylaws, current association budget, financial statements, reserve studies, applicable inspection reports, and pending assessment notices. Obtain unit-specific insurance quotes and written service terms as well.