A buyer-oriented review of Bay Harbor Towers resale planning, with a focus on separating document delivery from estoppel deadlines, reconciling association charges, and negotiating approval protections before closing.
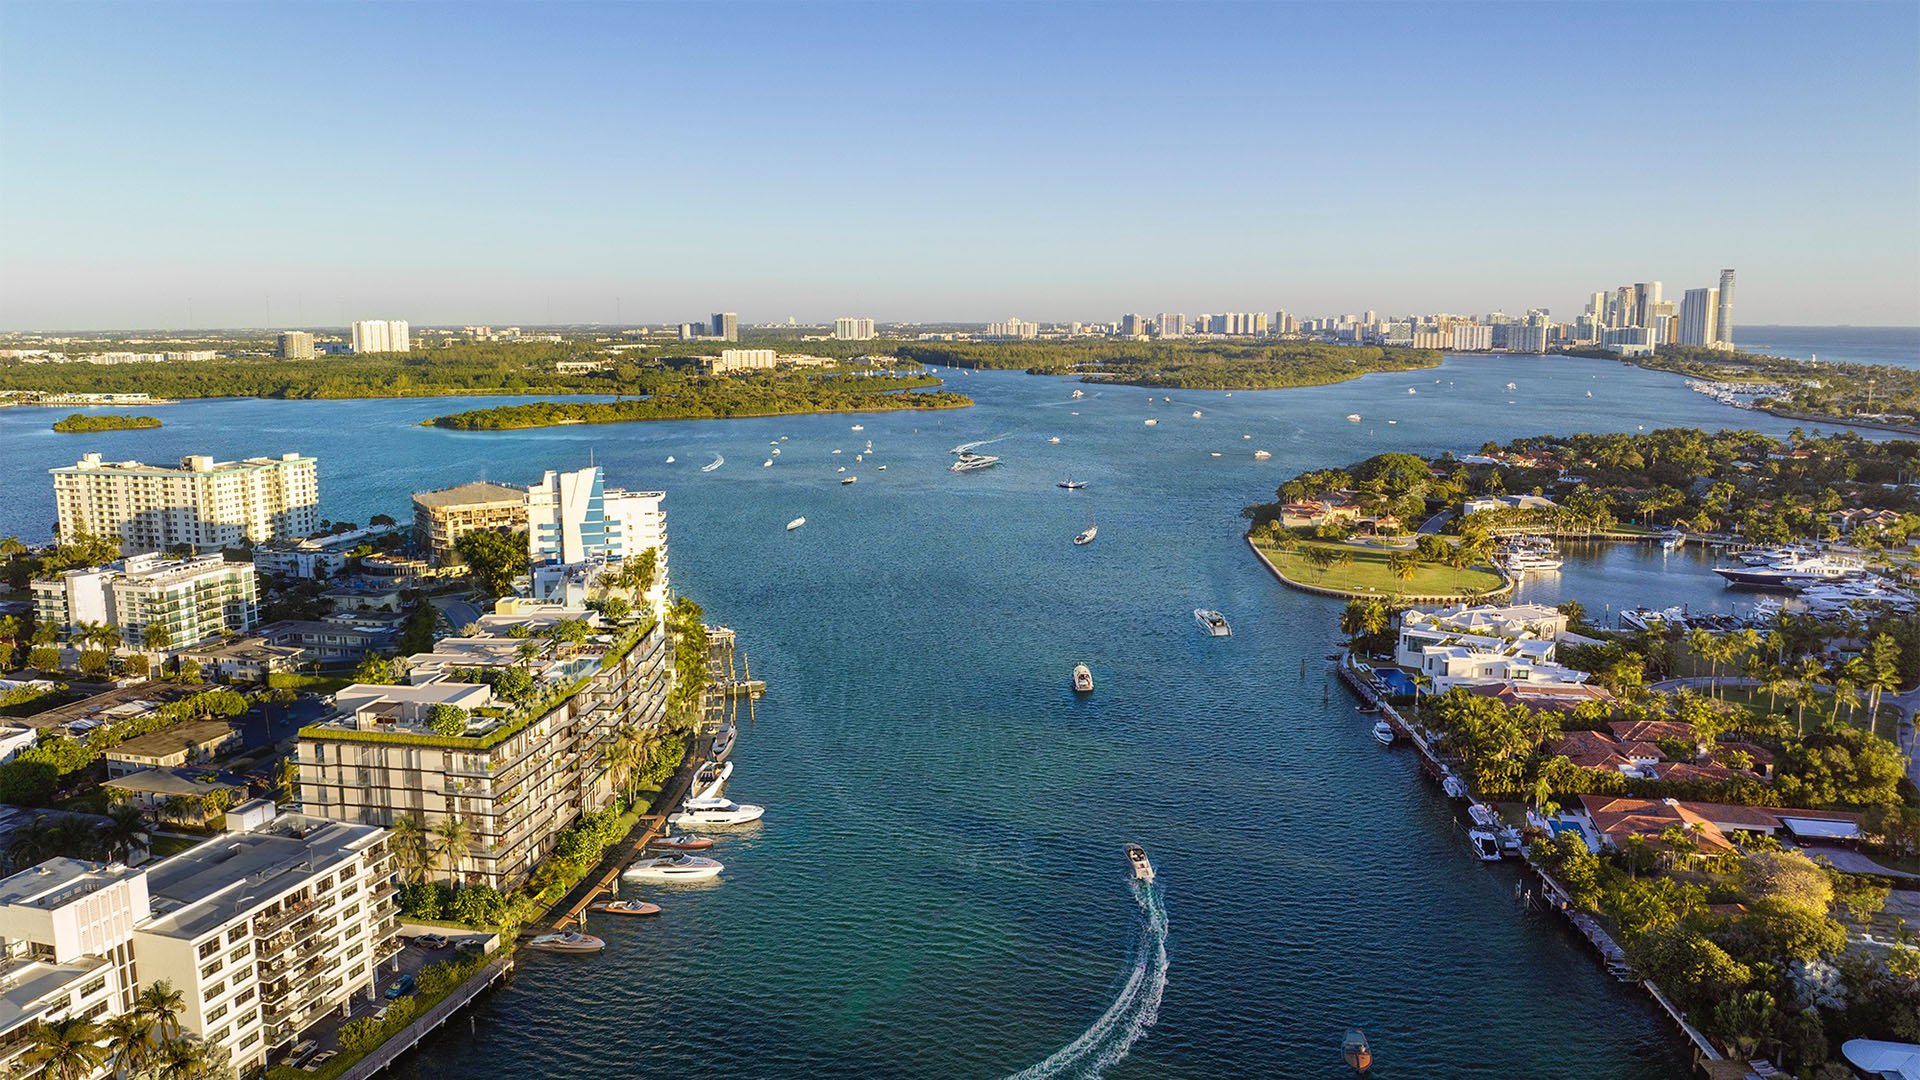
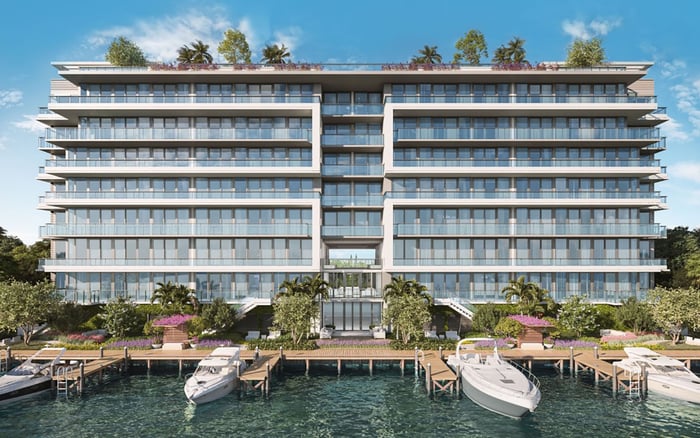
At Bay Harbor Towers, a boutique waterfront development with 44 private residences, purchase due diligence should extend beyond the residence itself. For a prospective resale buyer, the operational questions are precise: which documents must arrive, who receives each request, what the association says is owed, and whether transfer approval is required before closing.
The address is 10141 E Bay Harbor Drive, Bay Harbor Islands, FL 33154. Confirming that identity is straightforward. Building a reliable transaction calendar requires more care: the resale package, statutory estoppel certificate, and any association approval process are separate workstreams.
A well-managed purchase keeps those workstreams aligned without treating them as interchangeable. The objective is not simply to collect paperwork, but to ensure each document answers the right question while there is still time to act.
Begin with the broader condominium-document review. Request the governing documents, applicable ownership restrictions, transfer instructions, and any application requirements early in the contract period. Obtain written confirmation of the current contact, requested package contents, and anticipated delivery schedule. Do not assume a quoted package turnaround also covers approval.
The second calendar concerns the estoppel certificate. A condominium association must issue the certificate within 10 business days after receiving a qualifying written or electronic request. That statutory deadline does not set a delivery deadline for the entire resale package or a completion date for board review.
The third calendar covers any required transfer approval. Confirm whether approval applies, what constitutes a complete submission, and how the association communicates its decision. For a buyer also considering Alana Bay Harbor Islands, the same questions belong in a separate property file-not under an assumed neighborhood-wide timetable.
Assign responsibility for each request. A simple transaction schedule should track submission, acknowledged receipt, expected response, and the contractual deadline each response supports.
Eligible requesters include the unit owner, the owner's designee, the unit mortgagee, or the mortgagee's designee. Buyers should coordinate with the seller and closing team to establish who will submit the qualifying request and in what capacity.
Each association must designate on its website a person or entity, with a street or email address, to receive estoppel requests. Confirm that designated recipient rather than relying solely on a contact from an earlier transaction. A local condominium-association registry can help identify contacts, but the request should reach the designated recipient.
Retain the request and evidence of receipt. Sending and receipt are not interchangeable: the statutory issuance period runs after receipt of the qualifying request. Ask the closing team to calendar the business-day deadline separately from the proposed closing date.
Review an estoppel as a transaction document, not merely a balance statement. Start with the owner's name, unit designation, and address. Check any applicable parking or garage-space number against the transaction documents, and resolve discrepancies before relying on the certificate.
Next, reconcile regular assessments and itemized amounts owed. The certificate's financial disclosures include unpaid assessments, interest, late fees, attorney fees, and other association charges. A single bottom-line figure is no substitute for reviewing its components.
The certificate must also itemize additional assessments, special assessments, and other amounts scheduled to become due during its effective period. Review those entries against the proposed closing date and ask counsel to address their allocation under the purchase contract. If a delinquent account has been referred to collection counsel, the certificate must provide that attorney's name and contact information.
For buyers comparing Onda Bay Harbor with Bay Harbor Towers, consistency should come from the review checklist-not an assumption that separate associations have identical charges or procedures.
An estoppel delivered by hand or electronically has a 30-day effective period from issuance. A certificate sent by regular mail has a 35-day effective period from issuance. Both are distinct from the 10-business-day issuance requirement.
Ordering early can reveal discrepancies sooner, but the closing team must also ensure the certificate remains effective for the intended closing. Ordering late leaves less time to reconcile amounts or clarify an approval entry. Work backward from closing while preserving time for review.
If the closing date moves, revisit the certificate immediately. Ask whether an amendment or a newly issued certificate is appropriate rather than assuming the original remains usable. An association may not charge for preparing and delivering an amended estoppel certificate; that rule does not establish a blanket fee exemption for every later request.
The estoppel must address whether association approval is required for the transfer and, if so, whether approval has been granted. It must also address whether a right of first refusal applies and, if so, whether it has been exercised. Review these as separate questions.
Do not wait for the final certificate to discover either issue. Ask counsel to review the governing provisions during the contract period and confirm the applicable submission requirements in writing. A submitted application is not a documented approval.
Where approval is required, consider negotiating a contingency that specifies the buyer's submission obligations, the evidence needed to establish approval, and a deadline compatible with closing. Counsel should also address what happens if the association requests more information, declines approval, or has not decided by the agreed date.
Any extension, cancellation, or deposit-return protection should be expressly evaluated in the contract. Ordering an estoppel does not itself create those protections, and the statutory issuance deadline does not guarantee a board decision within the same period.
For a second-home buyer coordinating travel or a broader search that includes Bal Harbour, administrative certainty deserves attention alongside the residence's setting. Before committing to a closing calendar, confirm document delivery, application completeness, the certificate's effective period, and any required approval or right-of-first-refusal status.
The final review should reconcile the certificate with the closing figures and the transaction's approval requirements. Resolve conflicting names, amounts, dates, or status entries with the appropriate professionals rather than relying on informal assurances. This is a planning framework, not a substitute for transaction-specific legal advice.
For a discreet perspective on South Florida residential ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationBay Harbor Towers is a boutique waterfront development with 44 private residences.
The property is at 10141 E Bay Harbor Drive, Bay Harbor Islands, FL 33154.
The association must issue it within 10 business days after receiving a qualifying written or electronic request. This is not a deadline for the full resale package or board approval.
Eligible requesters include the unit owner, the owner's designee, the unit mortgagee, or the mortgagee's designee.
Send it to the person or entity designated on the association's website to receive estoppel requests. Confirm the street or email address and retain evidence of receipt.
An estoppel delivered by hand or electronically is effective for 30 days from issuance. One sent by regular mail is effective for 35 days from issuance.
Review regular assessments, itemized amounts owed, and additional assessments or other amounts scheduled to become due during the effective period. Reconcile those entries with the proposed closing figures.
Not necessarily. The certificate must state whether association approval is required and, if required, whether it has been granted.
No. Approval contingencies, extensions, cancellation rights, and deposit protections should be evaluated with counsel under the purchase contract.
An association may not charge for preparing and delivering an amended estoppel certificate. That rule should not be assumed to govern every subsequent request for a newly issued certificate.