A buyer-focused framework for evaluating operating budgets, contract escalators, staffing coverage, and unit-specific assessments at The Ritz-Carlton Residences® Pompano Beach, with a clear distinction between advertised services and verified financial obligations.
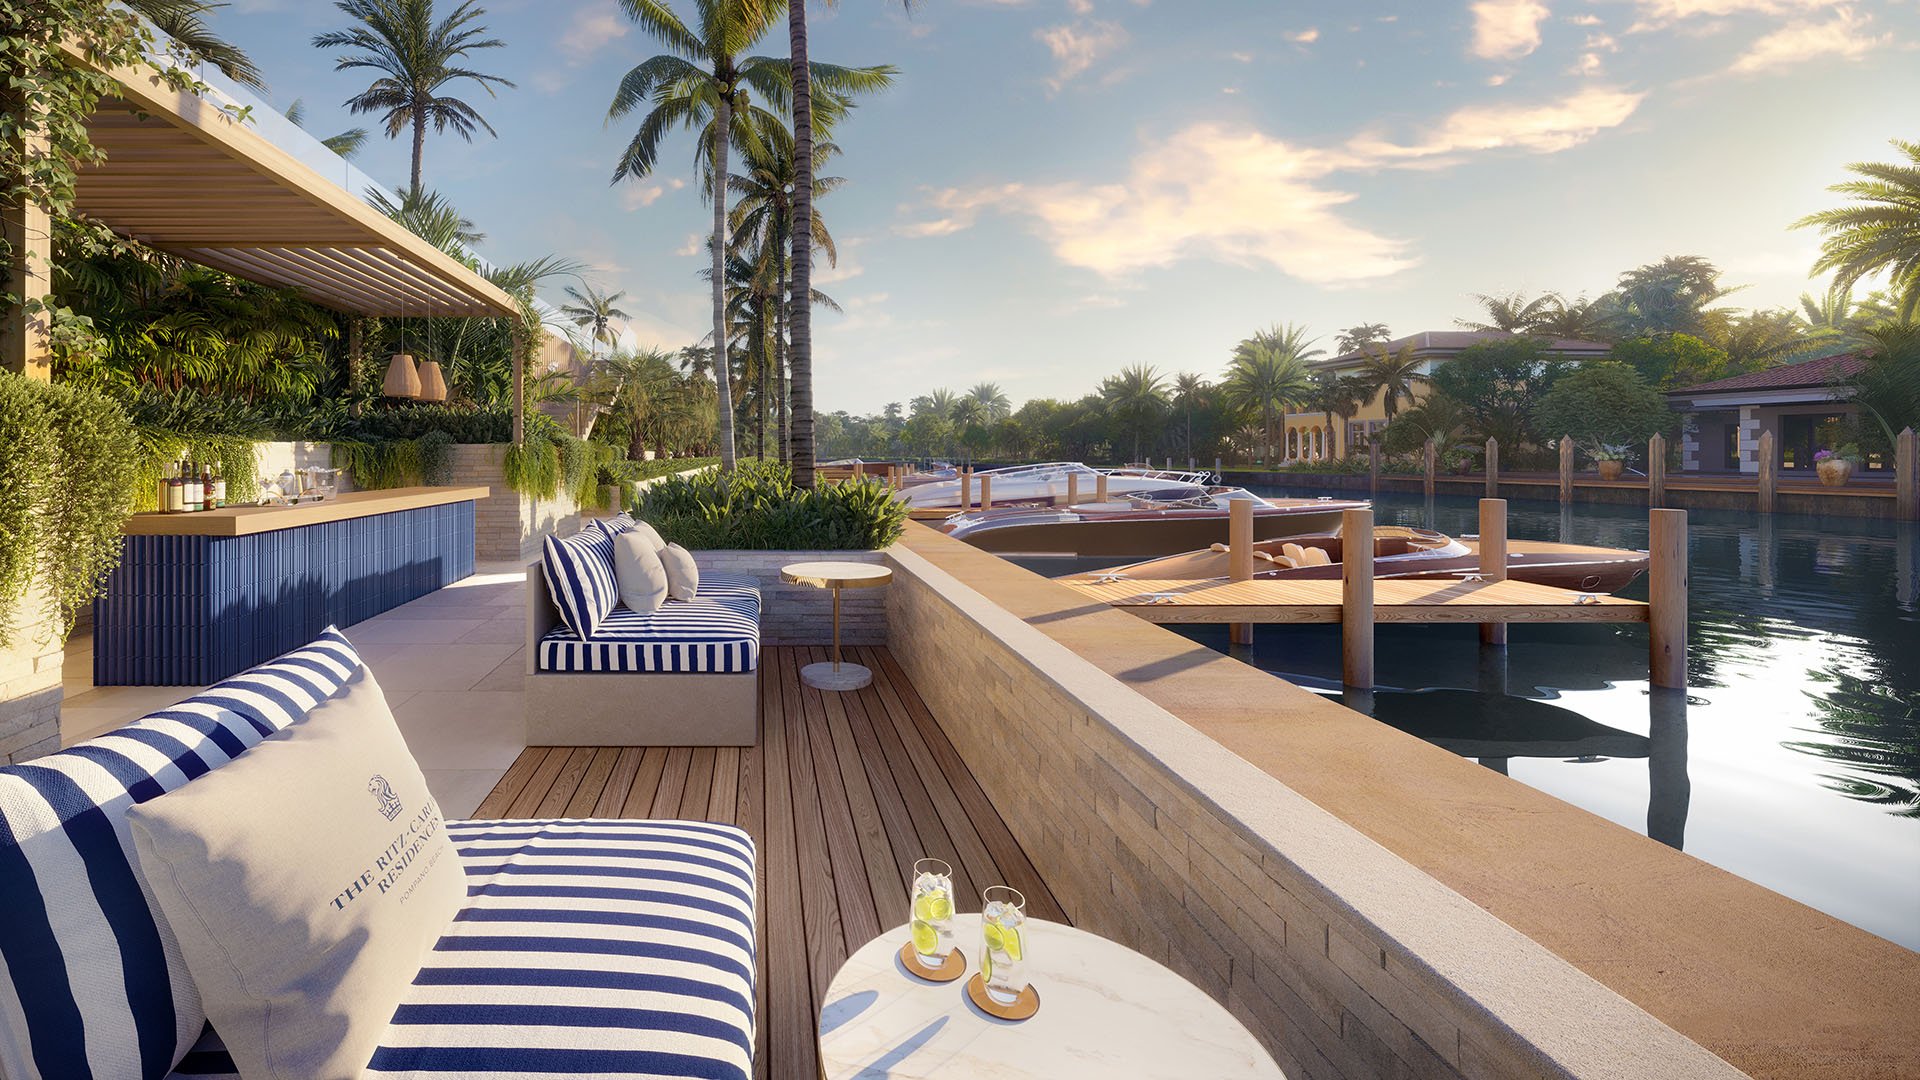
At The Ritz-Carlton Residences® Pompano Beach, ownership combines a waterfront setting with a branded residential service model. Located at 1380 S. Ocean Blvd., Pompano Beach, FL 33062, the development comprises two towers developed by Fortune International Group and Oak Capital, extending from the Atlantic Ocean to the Intracoastal Waterway. The advertised residence count is 204.
For a discerning buyer, the operating question is not whether concierge assistance or an elegant arrival sequence has value. It is whether the budget, staffing plan, and executed agreements explain how that experience will be delivered and funded. The distinction between an advertised service and an enforceable financial obligation is central to ownership underwriting.
This review does not verify a line-by-line association budget, audited financial statements, historical budget variances, or executed escalation formulas. That does not establish that these documents do not exist. The purchase decision should depend on obtaining and reviewing them-not translating marketing language into assumed expenses.
Advertised services include concierge, valet, arrival assistance, security, package handling, guest assistance, and housekeeping coordination. Amenities include pools, fitness and wellness facilities, lounges, event areas, business facilities, and beach-related services. Each deserves a defined operating scope, funding allocation, and service schedule.
Request a written distinction between services funded through common assessments and those billed to individual owners. Housekeeping coordination is not equivalent to included housekeeping. Likewise, in-residence dining, dry-cleaning coordination, and other personal services should not be treated as prepaid benefits simply because they appear in a service description.
A buyer also considering The Ritz-Carlton Residences® Sunny Isles should apply the same document-based questions independently. A shared brand name does not establish identical management fees, service inclusions, or expense allocations.
Request the developer’s initial budget, the first association-approved annual budget if available, and the latest forecast and actual results. Confirm the period and operating stage each document represents. Differing delivery descriptions do not establish completion, turnover, or stabilized operations.
Compare payroll, insurance, utilities, maintenance, reserves, and management charges. For each category, show the original provision, current budget, actual spending for the corresponding period, and expected full-year outcome. Ask management to explain both the dollar difference and its underlying cause.
An unfavorable variance requires interpretation, not an automatic verdict. Distinguish timing differences and one-time costs from recurring obligations. Conversely, spending below budget should prompt questions: Was the planned service level delivered? Did staffing remain incomplete? Was expenditure deferred? These are review questions, not findings about this development.
Keep reserve contributions visible rather than burying them within a headline monthly figure. Ask whether the forecast reflects the intended service scope and occupancy assumptions. A budget is most useful when its assumptions can be traced to contracts, staffing schedules, and documented expense allocations.
Obtain the executed management, brand, and major service agreements, together with amendments and relevant operating schedules. Identify the payer, covered services, fee basis, renewal dates, termination rights, and minimum service obligations. Advertised services do not establish these terms.
For every recurring agreement, ask whether increases are fixed, index-linked, subject to a minimum, or triggered by changes in scope. Check for caps and anniversary dates, and determine whether an increase applies to the entire charge or only selected components. These are possible contractual structures to investigate, not disclosed terms at Pompano Beach.
Review reimbursable expenses, surcharges, and change-order provisions separately from the base fee. Ask whether staffing costs are included in a management charge or billed in addition, and whether administrative charges apply to reimbursements. The objective is to avoid counting the same service twice or overlooking a separate obligation.
For buyers comparing Waldorf Astoria Residences Pompano Beach, a consistent contract checklist is more useful than assuming similarly positioned residences have comparable cost structures. Evaluate each agreement on its own terms.
A 24/7 concierge service is advertised, but that promise does not establish employee headcount, shift coverage, or payroll expense. Request a staffing matrix by function, employer, operating hours, shift, and relief coverage. Distinguish association employees, management-company personnel, and third-party contractors.
For every role, ask how the budget accounts for benefits burden, absences, relief staffing, and any overtime assumptions. Confirm which positions are dedicated to a tower and which support shared operations. The service schedule should explain how simultaneous needs are handled, without assuming one employee can cover multiple locations at once.
Occupancy assumptions deserve equal attention. Ask whether staffing is modeled for initial occupancy, seasonal demand, or the intended long-term service level. If coverage changes as occupancy increases, obtain the trigger and associated cost treatment in writing. The objective is not to maximize headcount, but to match the promised experience to a credible operating plan.
The ocean-to-Intracoastal configuration makes expense allocation an essential review item. Advertised marina or dock-related services do not establish staffing requirements or how their costs are assigned.
Review the governing documents to identify common, tower-specific, and any master-association expenses. Confirm the treatment of beach services, parking, marina operations, and shared amenities. Do not assume a residence benefits from, or pays for, every facility in the same proportion.
For a particular purchase, reconcile the allocation schedule with the current assessment notice. Then identify separately billed services, reserve contributions, and any pending special assessments. A complete ownership-cost picture should distinguish mandatory recurring charges from optional personal expenditure.
This review does not establish an association-verified monthly assessment for a particular residence. Request a current, unit-specific assessment schedule rather than treating an unverified estimate as a financial obligation.
A per-square-foot comparison is useful only when the underlying charges, area measurements, and included expenses are confirmed. It does not establish uniform charges across residences or replace the governing allocation schedule.
Before committing, seek a coherent set of documents: the budget and variance explanation, executed agreements, staffing matrix, expense allocations, and assessment schedule. The strongest ownership decision makes the service experience and its financial obligations equally clear.
For a discreet perspective on South Florida residential opportunities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe development is located at 1380 S. Ocean Blvd., Pompano Beach, FL 33062, with two towers extending from the Atlantic Ocean to the Intracoastal Waterway.
The advertised collection comprises 204 residences. That figure does not establish the allocation of operating expenses among owners.
Request the developer’s initial budget, the first association-approved annual budget if available, and the latest forecast and actual results. Compare matching periods and clarify the operating stage each document represents.
This review does not verify historical budget variances or audited financial statements. Buyers should request the relevant financial documents directly.
Review executed agreements for escalation formulas, renewal and termination provisions, minimum service levels, reimbursable expenses, surcharges, and change orders. Separate base fees from additional obligations.
No; advertised round-the-clock availability does not establish headcount, shift coverage, employer arrangements, or payroll expense.
They should not be assumed included merely because they appear in service descriptions. Request a written schedule distinguishing assessment-funded services from individually billed services.
This review does not establish an association-verified monthly assessment for a particular residence. Obtain the current, unit-specific assessment schedule before relying on an estimate.
Confirm the underlying charges, area measurements, and included expenses before comparing figures. A per-square-foot calculation does not replace the governing expense-allocation schedule.
Review governing documents and operating agreements to confirm staffing responsibilities and common, tower-specific, or other expense allocations. Reconcile those obligations with the assessment schedule for the residence being purchased.