A disciplined first-year cash-flow plan for a multigenerational move from Sydney to West Palm Beach separates association obligations, personal services, insurance, property taxes, and the cost of making a residence ready for arrival.
Moving a multigenerational household from Sydney to West Palm Beach is as much about sequencing as selecting a residence. Parents may arrive before adult children; furniture may follow later; personal support may be needed immediately. A useful first-year plan shows when money leaves the account, not simply what ownership costs over twelve months.
Begin with three dates: closing, household arrival, and the end of the first twelve months of ownership. Establish who will occupy the home, which services each generation needs, and which purchases must be complete before arrival. Keep acquisition costs and financing separate from the ownership-and-settlement budget discussed here.
A defensible total rests on property-specific documents and household-specific quotations. A generic allowance cannot establish association dues, personal insurance premiums, care costs, or furnishing expenditure for a particular family.
Organize the plan into recurring ownership expenses, optional household services, one-time settlement costs, and contingency liquidity. These are budgeting categories, not necessarily separate bank accounts.
For each line, record the quoted amount in US dollars, payment frequency, first due date, included services, and the person responsible for approving changes. If funding comes from Australian dollars, record a separate conversion assumption and obtain transfer-cost quotations rather than treating the exchange rate as fixed.
Use a monthly ledger with these fields:
Association dues and any separately payable assessment installments.
Owner insurance payments and property-tax payments or escrow contributions.
Selected household services, with their actual start dates.
Furnishing deposits, balances, shipping, storage, delivery, and installation.
Contingency transfers, distinguished from money actually spent.
Total scheduled payments to calculate anticipated outflow. Show unspent contingency separately to establish the liquidity required. Where a lender collects taxes or insurance through escrow, reconcile those contributions against direct payments so the same obligation is not counted twice.
For a condominium purchase, distinguish the association assessment-often called HOA dues-from services purchased directly by the household. Request the current budget, the unit’s payment schedule, reserve information, insurance declarations, inspection findings, and details of pending assessments.
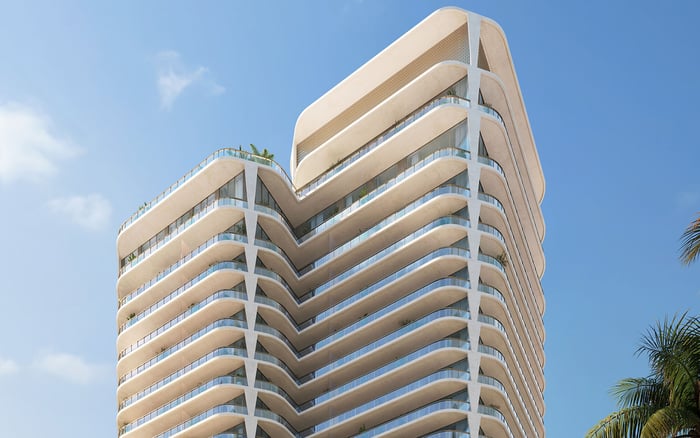
When evaluating Alba West Palm Beach, make the same request you would for any shortlisted residence: a written account of what the quoted dues cover, what remains separately payable, and when each payment begins. Do not infer inclusions from an amenity description.
Florida has milestone-inspection and structural-integrity reserve requirements for condominiums. Establish which requirements apply to the building and how inspection findings and reserve funding affect its financial plan. Reviewing these documents is due diligence, not a guarantee that dues will remain unchanged.
Record any disclosed assessment installments on their actual payment dates. A smooth monthly average can conceal a concentrated cash requirement shortly after closing.
A multigenerational household needs a service plan with distinct scopes. Request separate quotations for housekeeping, transportation, companion care, home-health services, and skilled nursing. Do not fold these into a single convenience allowance.
Specify hours, frequency, start dates, cancellation terms, and any additional charges in each request. Separate essential support from discretionary preferences, and ask how the quotation changes if the household needs more hours after arrival.
For buyers considering Mr. C Residences West Palm Beach, the practical question is which desired services are included, which can be arranged separately, and which require an independent provider. Confirm those distinctions in writing; do not assume a residential service offering includes personal care.
Budget each generation’s requirements first, then identify genuine opportunities to share services. Shared transportation may suit one household; separate schedules may be essential for another.
Review association insurance and the household’s own coverage together. Ask an insurance adviser to identify the boundary between them, applicable deductibles, and any protection needed for the residence’s interiors, furnishings, or particular household circumstances. Obtain quotations before committing to a final operating budget.
In Florida, condominium association insurance replacement values must be established through a new or updated appraisal at least every three years. Request the relevant appraisal date and current insurance documentation when reviewing association finances.
Flood insurance is available to condominium unit owners as well as homeowners. Properties in high-risk flood areas with mortgages from federally regulated or insured lenders generally must carry it. Have the adviser determine the property’s requirements rather than assuming condominium ownership resolves the question.
For Forté on Flagler West Palm Beach, apply the same property-specific review. Schedule quoted premiums by payment date and distinguish deductible liquidity from premium expenditure.
Palm Beach County ad valorem property taxes are calculated using taxable value-assessed value less applicable exemptions-and the applicable millage rates. The bill combines levies from several authorities, including the county, school district, municipality, and relevant local districts. Valuation and rate-setting are separate functions.
A purchase can trigger reassessment. The seller’s capped assessment or current tax bill should therefore not become the buyer’s long-term assumption. Properties are assessed at market value in the first year they receive homestead exemption.
Buying a home does not automatically establish homestead eligibility. Permanent-residence requirements matter, including January 1 ownership and residency considerations and supporting documentation such as a Florida driver’s license or vehicle registration. The regular application deadline is March 1 of the year for which the exemption is sought.
For a household relocating internationally, confirm eligibility before budgeting any savings. The first twelve months after closing are not necessarily the first reassessed tax year. Have the closing and tax advisers distinguish closing adjustments, subsequent cash payments, and a forward-looking reassessed estimate. A TRIM notice shows proposed estimates, not the final amount payable.
Divide furnishing into arrival essentials and later purchases. Start with each generation’s sleeping arrangements, practical seating, lighting, and everyday dining needs. Let the more expressive layers of the interior follow a confirmed installation plan.
For a residence under consideration at Shorecrest Flagler Drive West Palm Beach, request delivery and installation requirements before scheduling shipments. Do not assume access arrangements or that a preferred arrival date aligns with possession.
Compare shipping selected Sydney furnishings with buying locally through separate quotations. Itemize storage, delivery, installation, and applicable taxes. Enter deposits and final balances in the cash calendar, then revisit the ledger whenever arrival dates, service needs, or specifications change. The goal is a home ready for every generation, without mistaking one-time settlement spending for the enduring cost of ownership.
For a discreet conversation about your West Palm Beach residence search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationYou can establish the structure, but a defensible total requires property-specific dues, insurance quotations, tax estimates, service scopes, and furnishing proposals.
That may estimate ordinary dues if the amount stays unchanged, but it does not capture separately payable assessments or other costs. Use the actual payment schedule and review association documents.
Request the current budget, reserve information, insurance declarations, inspection findings, and details of pending assessments. Confirm the payment obligations for the specific unit.
Do not assume they are included. Confirm inclusions in writing and obtain separate quotations for housekeeping, companion care, home-health services, and skilled nursing as needed.
Yes. Properties in high-risk flood areas with mortgages from federally regulated or insured lenders generally must carry flood insurance; confirm the requirements for the specific property.
Not necessarily, because a purchase can trigger reassessment. Do not assume the seller’s capped assessment or current bill will carry over.
No. Eligibility depends on permanent-residence requirements, including relevant January 1 ownership and residency considerations.
The regular deadline is March 1 of the year for which the exemption is sought. Confirm eligibility and supporting documentation before including savings in the budget.
No. It shows proposed property-tax estimates based on property values and proposed rates, rather than the final amount payable.
Separate arrival essentials from later purchases and obtain itemized shipping, storage, delivery, installation, and applicable-tax estimates. Schedule deposits and balances by payment date rather than averaging the entire cost across the year.