A discreet planning framework for families moving from Hong Kong to Fisher Island, connecting homestead restrictions, beneficiary alignment, title-insurance questions and residence-specific operating budgets.
For a multigenerational family moving from Hong Kong to Fisher Island, the acquisition is only one part of establishing a lasting home. The more consequential questions concern continuity: who will own the residence, who is intended to inherit it, and how its expenses will be paid if the person funding the household can no longer do so.
Start with a family brief that separates occupancy, ownership and financial responsibility. Identify which generations will live together, who will contribute to expenses and who should coordinate advisers. Document these decisions rather than treating them as shared assumptions.
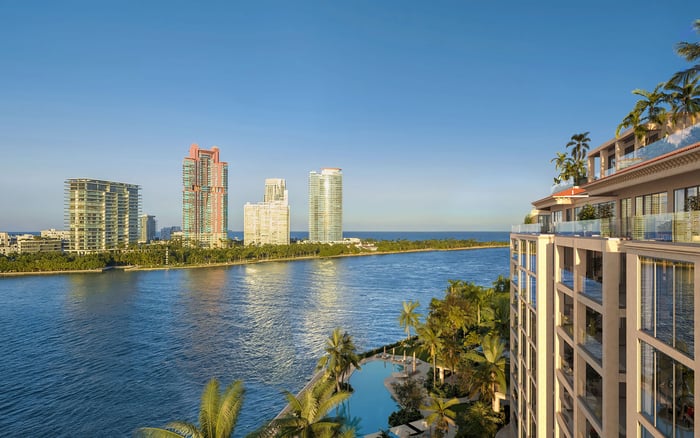
When considering Palazzo del Sol Fisher Island, bring that brief into the purchase discussion alongside the residence requirements. The aim is to align the home with the family’s intended arrangements before they become closing instructions.
Florida homestead is a threshold legal question, not a label to apply casually to a new primary residence. Before finalizing succession documents, ask Florida counsel whether the proposed Fisher Island home will qualify as the owner’s homestead and how that determination affects the intended transfer.
Florida’s homestead devise restrictions generally prohibit an owner from leaving homestead by will when a spouse or minor child survives. The principal exception permits a devise to the spouse when there is no minor child. The family’s preferred division among generations must therefore be reviewed against the applicable restrictions.
For a Hong Kong household, the next step is coordinated advice from qualified Florida and Hong Kong advisers. Ask them to consider the proposed owner, relevant succession documents and applicable tax treatment together. Do not select personal, trust or entity ownership on the assumption that one structure automatically resolves every concern.
The practical deliverable is a written explanation of whether the intended succession arrangement works for this family and this residence.
A will is not the only document that can direct wealth at death. Life insurance, retirement accounts, payable-on-death accounts and annuities may pass directly to named beneficiaries. Those designations require a separate review alongside the estate plan.
Prepare an inventory of each relevant asset, its owner, its named beneficiaries and its intended purpose. Then ask advisers whether the designations support the family’s wishes, including the proposed funding for ongoing residence expenses.
This distinction matters when one family member is expected to inherit or occupy the home while another is named to receive financial assets. Ask whether the proposed arrangements provide for the intended expense sharing. A family understanding should not substitute for professional review.
For a household evaluating Palazzo della Luna Fisher Island, beneficiary coordination belongs beside the operating budget. The essential question is whether the intended funding recipient and the person responsible for residence bills are appropriately aligned.
Discuss estate-plan liquidity in terms of usable funds, not simply aggregate family wealth. Ask advisers what money would be available for the residence following a death or incapacity, who could authorize payments and what documentation would be required.
Rather than adopting a generic reserve multiple, request a family-specific review built around the actual annual budget. Which expenses would continue? Could the designated person access the intended accounts? Would moving funds between Hong Kong and the United States require additional planning? What alternatives should be considered if the expected funding route were unavailable?
These are questions for a coordinated legal, tax and financial review, not conclusions about cross-border access or estate obligations. The objective is a documented payment plan, with responsibilities clearly assigned and unresolved assumptions identified before closing.
Title insurance deserves its own discussion with Florida real-estate counsel and the title professional. Ask them to explain the proposed coverage, the intended insured owner, the exclusions and exceptions, and any matters requiring resolution before closing.
If the estate plan contemplates a later ownership change, ask how that transfer would interact with the policy and whether additional review or coverage would be needed. Do not assume that a title-insurance policy answers succession questions or implements the family’s inheritance wishes.
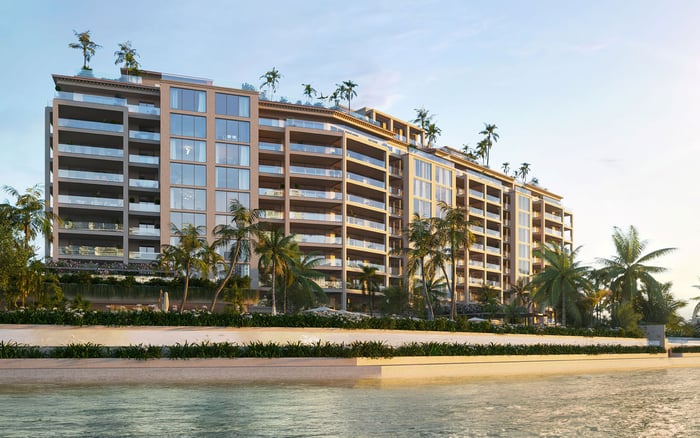
A purchase review for The Residences at Six Fisher Island should align three points: who counsel recommends should take title, how the closing documents identify that owner, and what the title professional confirms about coverage. Seek transaction-specific answers rather than general assurances.
Fisher Island budgeting requires distinct categories. Condominium or building assessments, Fisher Island Community Association assessments, property taxes and club charges should not be treated as one interchangeable fee.
Condominium assessments typically cover building staff, common-area utilities, elevators, landscaping, pools, common-element insurance, management and reserve contributions. FICA assessments fund shared services and infrastructure, including ferry operations, public safety, public works and landscaping.
Indicative monthly HOA figures range from approximately $3,000 to more than $12,000, depending on the building and residence size. These provide orientation, not current quotations for a particular purchase. Similarly, indicative annual club dues of approximately $19,260 to $53,378 vary by membership category, with potential initiation or equity-related charges in addition. Confirm the applicable terms directly.
Billing frequency warrants particular care. Indicative figures for 1004 Fisher Island Drive, Miami Beach, are $102,944 in annual property taxes and $12,452 in quarterly HOA fees. The HOA amount is quarterly, not annual, and neither figure is a verified post-purchase cost.
Before combining estimates, establish whether each assessment includes or excludes FICA, reserves, insurance or other charges. Otherwise, even a carefully prepared spreadsheet can double count expenses or omit important items.
The final budget should draw on actual assessments, tax bills, insurance quotations, club status, utilities and household staffing requirements. Include insurance considerations such as wind and flood coverage rather than assuming common-element insurance completes the household’s protection.
If The Links Estates at Fisher Island is also under consideration, request its own property-specific schedule. Do not transfer a condominium cost estimate to another residence without confirming the applicable obligations.
Organize the schedule by annual amount, payment frequency, inclusions and responsible payer. Keep recurring costs separate from any applicable one-time charges. Alongside it, maintain the adviser-approved ownership instructions, beneficiary inventory and proposed continuity arrangements.
For a multigenerational move, that is the quieter measure of readiness: a residence chosen with care, supported by arrangements the family understands and qualified advisers have reviewed.
Explore Fisher Island residences with MILLION to begin a considered search for your family’s next home.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationDocument intended occupants, proposed ownership, inheritance wishes and responsibility for expenses. Use that brief to coordinate the purchase and adviser reviews.
Florida generally restricts devising homestead when a spouse or minor child survives, with an exception allowing a devise to the spouse if there is no minor child. Counsel should determine whether the residence qualifies and how the restrictions apply.
No. Life insurance, retirement accounts, payable-on-death accounts and annuities may transfer directly to named beneficiaries and need separate coordination.
Ask advisers which funds would be accessible after death or incapacity, who could authorize payments and what documentation would be needed. Build the discussion around the residence’s actual operating budget.
The choice requires family-specific advice from qualified Florida and Hong Kong advisers. Do not assume personal, trust or entity ownership automatically resolves succession and tax concerns.
Ask about the insured owner, proposed coverage, exclusions, exceptions and unresolved closing matters. If a later ownership transfer is contemplated, request advice on its implications for coverage.
Fisher Island Community Association assessments fund shared services and infrastructure, including ferry operations, public safety, public works and landscaping.
Club charges are a separate expense category. Confirm membership terms and the inclusions of every quoted assessment before combining costs.
No. The listing labels it quarterly and separately identifies $102,944 in annual property taxes; neither is a verified post-purchase cost.
Include applicable building and FICA assessments, property taxes, club charges, insurance, utilities and household staffing requirements. Verify billing frequency and inclusions to avoid omissions or double counting.