For an estate retaining or transferring a South Florida condominium, insurance diligence should connect the association’s master deductible, unit-level replacement costs, valuable-articles inventory, and liability arrangements before ownership or occupancy changes.
A South Florida residence can be both a family retreat and a significant estate asset. Retaining or transferring it requires more than a review of title and market value. Insurance diligence should connect the building’s protection, the unit’s interiors, its contents, and the parties who need coverage throughout the transition.
For condominiums, four questions require coordinated attention: what the master policy leaves to owners, whether HO-6 limits reflect the residence, how valuable articles are documented, and whether liability arrangements remain appropriate. A substantial limit on one policy does not establish that every exposure has been addressed.
This framework principally concerns South Florida condominiums. Do not automatically apply condominium master-policy allocation rules to a detached residence or an HOA. Those properties require their own document and policy review.
A condominium’s master policy generally covers the building structure, roof, common elements, and insured property as originally installed. It does not replace the owner’s HO-6 policy, which addresses unit-level building property, improvements, belongings, and personal liability, subject to its terms.
Start by reading the condominium declaration alongside the master policy. Identify responsibility for finishes, fixtures, improvements, and interior damage. “Walls-in” is too imprecise to resolve those questions for a residence with substantial customization.
For an estate evaluating a Brickell residence such as Una Residences Brickell, the review should be document-led: establish what the association insures, then identify what the owner must protect. A project’s identity is no substitute for reviewing its applicable insurance documents.
A percentage-based master deductible can represent substantial exposure. Ask which value the percentage applies to, what dollar amount it produces, and how the applicable allocation rules translate that amount into the unit’s potential share.
Master-policy deductibles and covered-loss shortfalls can become common condominium expenses allocated to owners, subject to statutory exceptions and applicable rules. Do not assume that every owner pays equally or that every deductible necessarily becomes an assessment.
Request the current master-policy deductibles, allocation provisions, and replacement-cost valuation. Florida condominium associations must maintain adequate property insurance regardless of declaration requirements and redetermine replacement cost at least every three years. An outdated valuation can leave the association underinsured and owners exposed to additional assessments after a loss.
The objective is a dollar-denominated exposure estimate that can be compared with actual unit-owner coverage-not a reassuring percentage viewed in isolation.
Florida unit-owner residential property policies must include at least $2,000 in property loss-assessment coverage for assessments resulting from the same direct property loss. The statutory deductible for that coverage generally cannot exceed $250 per direct property loss.
That minimum is a starting point, not proof of adequate protection for a luxury condominium. Coverage depends on policy wording, covered causes of loss, exclusions, and sublimits. An association’s decision to impose an assessment does not, by itself, make that assessment insured.
Before choosing a limit, ask whether the endorsement covers assessments attributable to the association’s deductible and whether a separate deductible-assessment sublimit applies. Compare those answers with the unit’s potential allocated exposure.
For a Miami Beach residence such as The Perigon Miami Beach, these are diligence questions, not statements about the project’s insurance. Verify legal requirements and transaction-specific coverage with Florida counsel and a licensed insurance professional.
The HO-6 building-property limit should reflect the cost of replacing the improvements and finishes for which the unit owner is responsible. Do not assume that the association covers every interior component or substitute the residence’s sale value for an interior replacement-cost review.
Ask the insurance adviser to reconcile the declaration’s allocation of responsibility with the residence’s actual interior specifications. The review should distinguish owner-responsible building property from personal belongings and identify the applicable limits and endorsements.
The same discipline applies when considering Ocean House Surfside in Surfside: evaluate the particular residence and its governing documents rather than relying on a general impression of finish quality. The estate must establish what needs to be replaced, who is responsible, and which policy responds.
Valuable-articles diligence should begin with an inventory, not an assumption about what a contents limit includes. Ask whether the residence’s inventory matches the estate’s records, whether appraisals remain current, and which items or categories require closer review.
Have the adviser identify applicable category sublimits and discuss whether particular articles should be scheduled. If schedules already exist, reconcile their descriptions and values with the articles actually retained, transferred, or removed from the residence.
Do not assume that an appraisal, inventory entry, or schedule establishes coverage for every circumstance. Obtain carrier confirmation of the relevant terms and insured ownership. The goal is a documented review, not a generalized promise of valuable-articles protection.
Umbrella coordination requires carrier confirmation. Ask who must be insured, what underlying liability limits are required, and how the proposed ownership and occupancy arrangements should be reflected across the policies.
If title will pass to an estate, trust, LLC, or beneficiary, confirm how the particular policies treat that arrangement. Ask the same questions about death, vacancy, and any change in occupancy. Do not presume that existing coverage continues unchanged or that a title update alone resolves insurance requirements.
For a Sunny Isles Beach residence such as Jade Signature Sunny Isles Beach, the estate should obtain clear answers before implementing its ownership plan. Property limits and liability arrangements require separate, coordinated review.
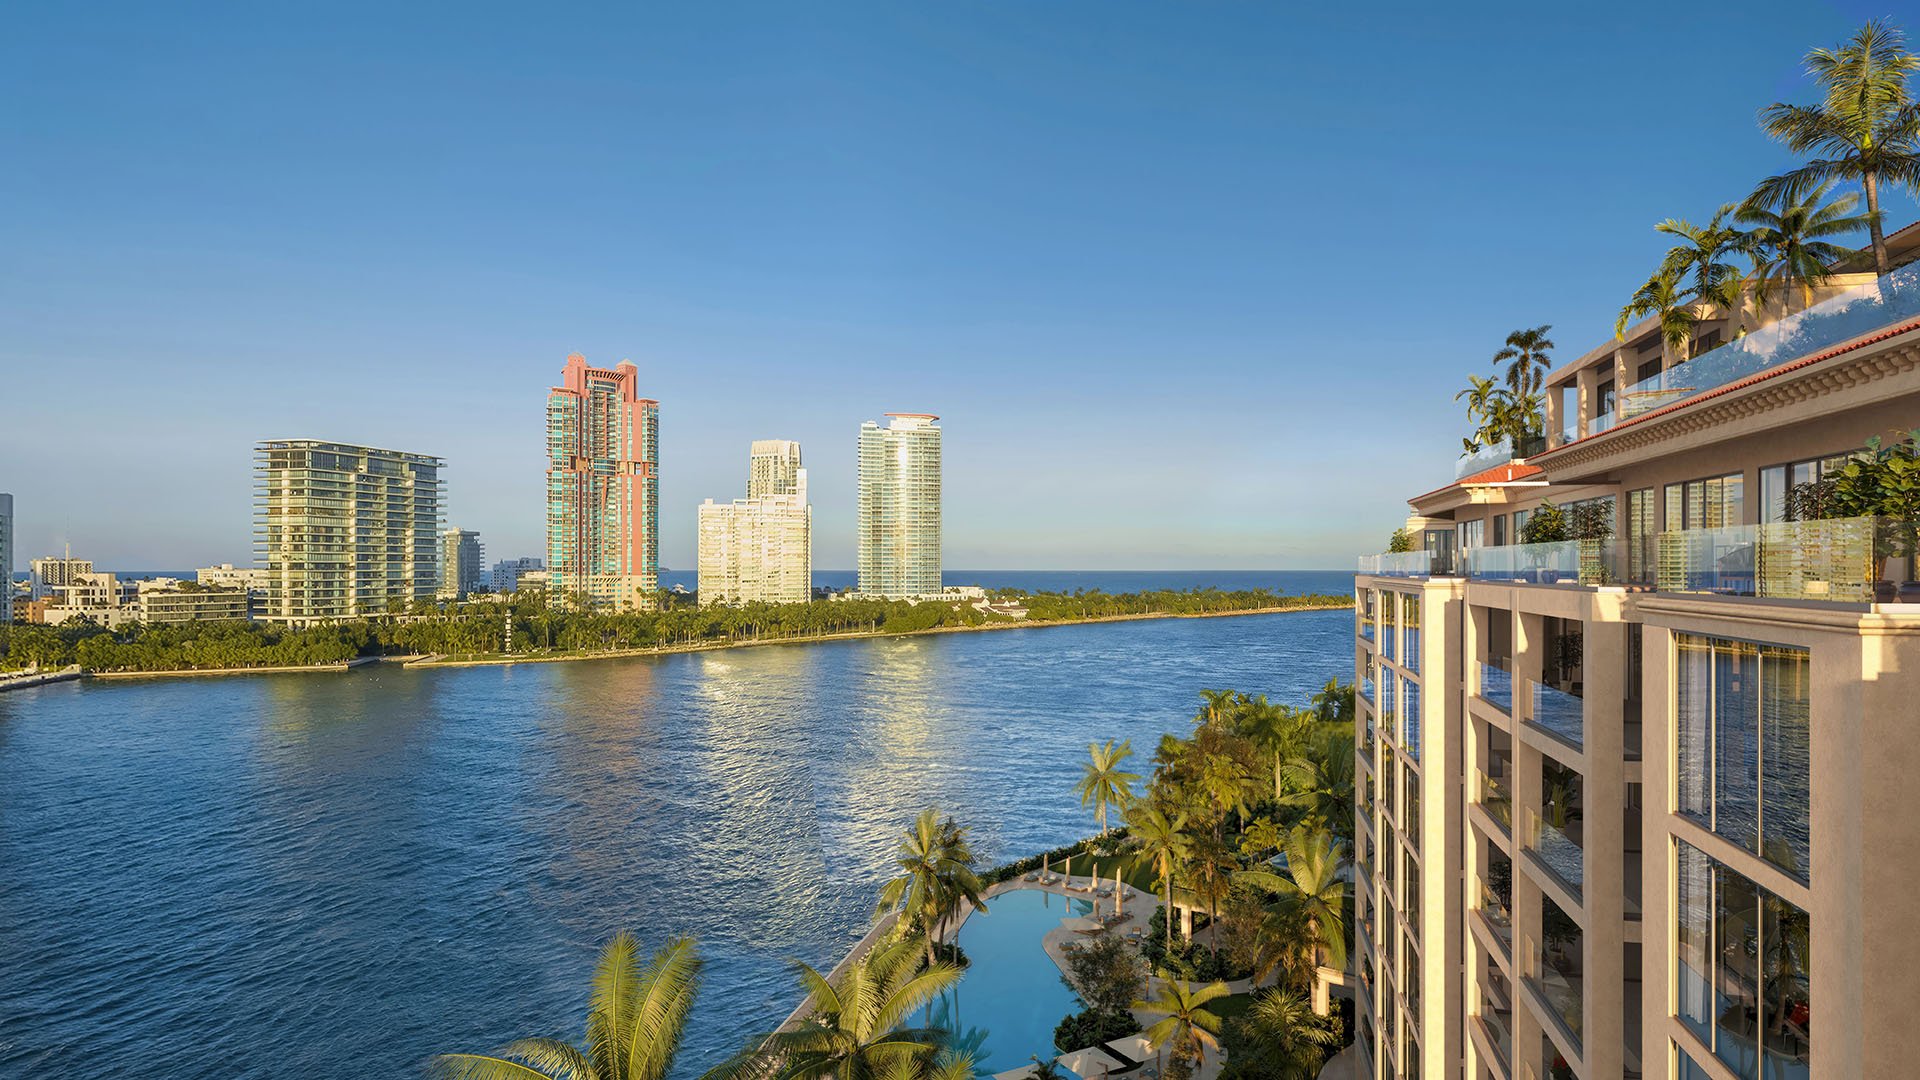
Waterfront ownership warrants a distinct wind and flood review. Master-policy wind protection does not establish that flood damage, unit contents, or improvements are insured. Ask the adviser to identify which policies address each exposure and where limitations remain.
Second-home planning should also include carrier confirmation of the intended occupancy status. If the transfer involves financing, check the lender’s applicable master-deductible and HO-6 requirements and their effective dates. Mortgage underwriting can demand more than statutory minimums; thresholds should not be treated as universal across loan programs.
Before retention or transfer, assemble the declaration, master policy, deductible information, replacement-cost valuation, HO-6 forms and endorsements, inventory, valuable-articles schedules, and umbrella documents. Request written answers on allocation, limits, insured parties, and proposed changes.
The objective is continuity supported by documents: an identifiable exposure, a reviewed policy response, and a deliberate decision about any remaining risk.
For a considered approach to South Florida residential ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The master policy generally covers building-level property, while HO-6 addresses unit-level exposures such as improvements, belongings, and personal liability, subject to its terms.
The declaration and master policy help identify responsibility for finishes, fixtures, improvements, and interior damage. The shorthand walls-in does not resolve those responsibilities.
Master-policy deductibles and covered-loss shortfalls can become common expenses allocated to owners, subject to statutory exceptions and applicable allocation rules.
Florida unit-owner residential property policies must include at least $2,000 for assessments resulting from the same direct property loss. The statutory deductible for that coverage generally cannot exceed $250 per direct property loss.
No. Coverage depends on the policy’s covered causes of loss, exclusions, endorsements, and sublimits, including any separate limit for assessments attributable to an association deductible.
Compare the limits with the replacement cost of the actual improvements and finishes for which the owner is responsible. Do not assume the master policy covers every interior component.
Replacement cost must be redetermined at least every three years. Outdated valuations can leave the association underinsured and expose owners to additional assessments after a loss.
Reconcile inventories, current appraisals, applicable category sublimits, and existing schedules. Ask the adviser and carrier whether scheduling or ownership updates are appropriate for the articles involved.
Confirm insured parties, required underlying limits, and how the carrier treats the proposed title and occupancy arrangements. Do not assume an estate, trust, LLC, vacancy, or death leaves coverage unchanged.
No. Wind and flood require separate review, including protection for unit contents and improvements.