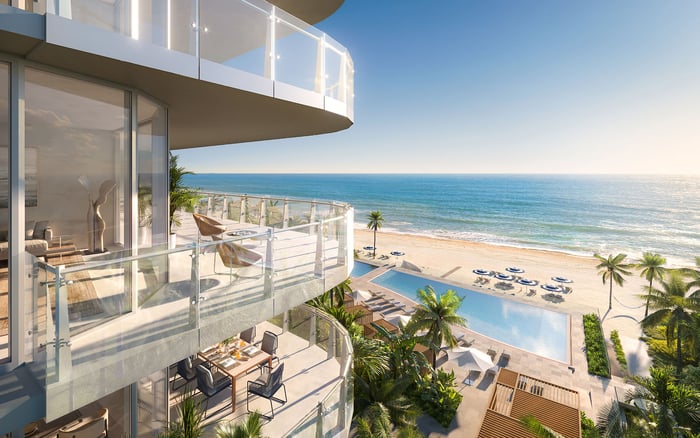
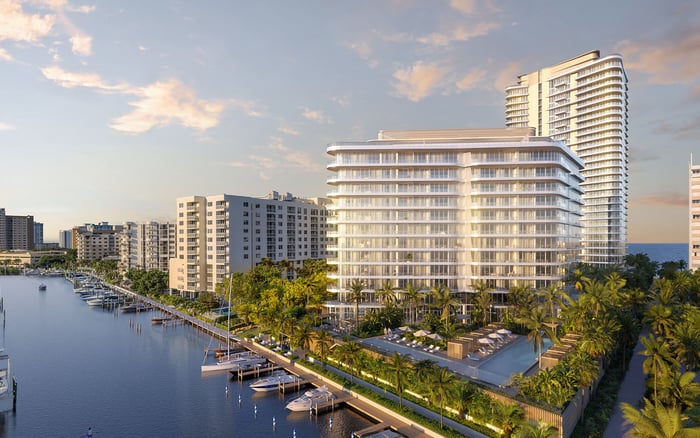
A considered move from Hong Kong to Pompano Beach begins with transaction sequencing: separating expected sale proceeds from usable liquidity, confirming primary-residence financing, and aligning the purchase with permanent-residence requirements.
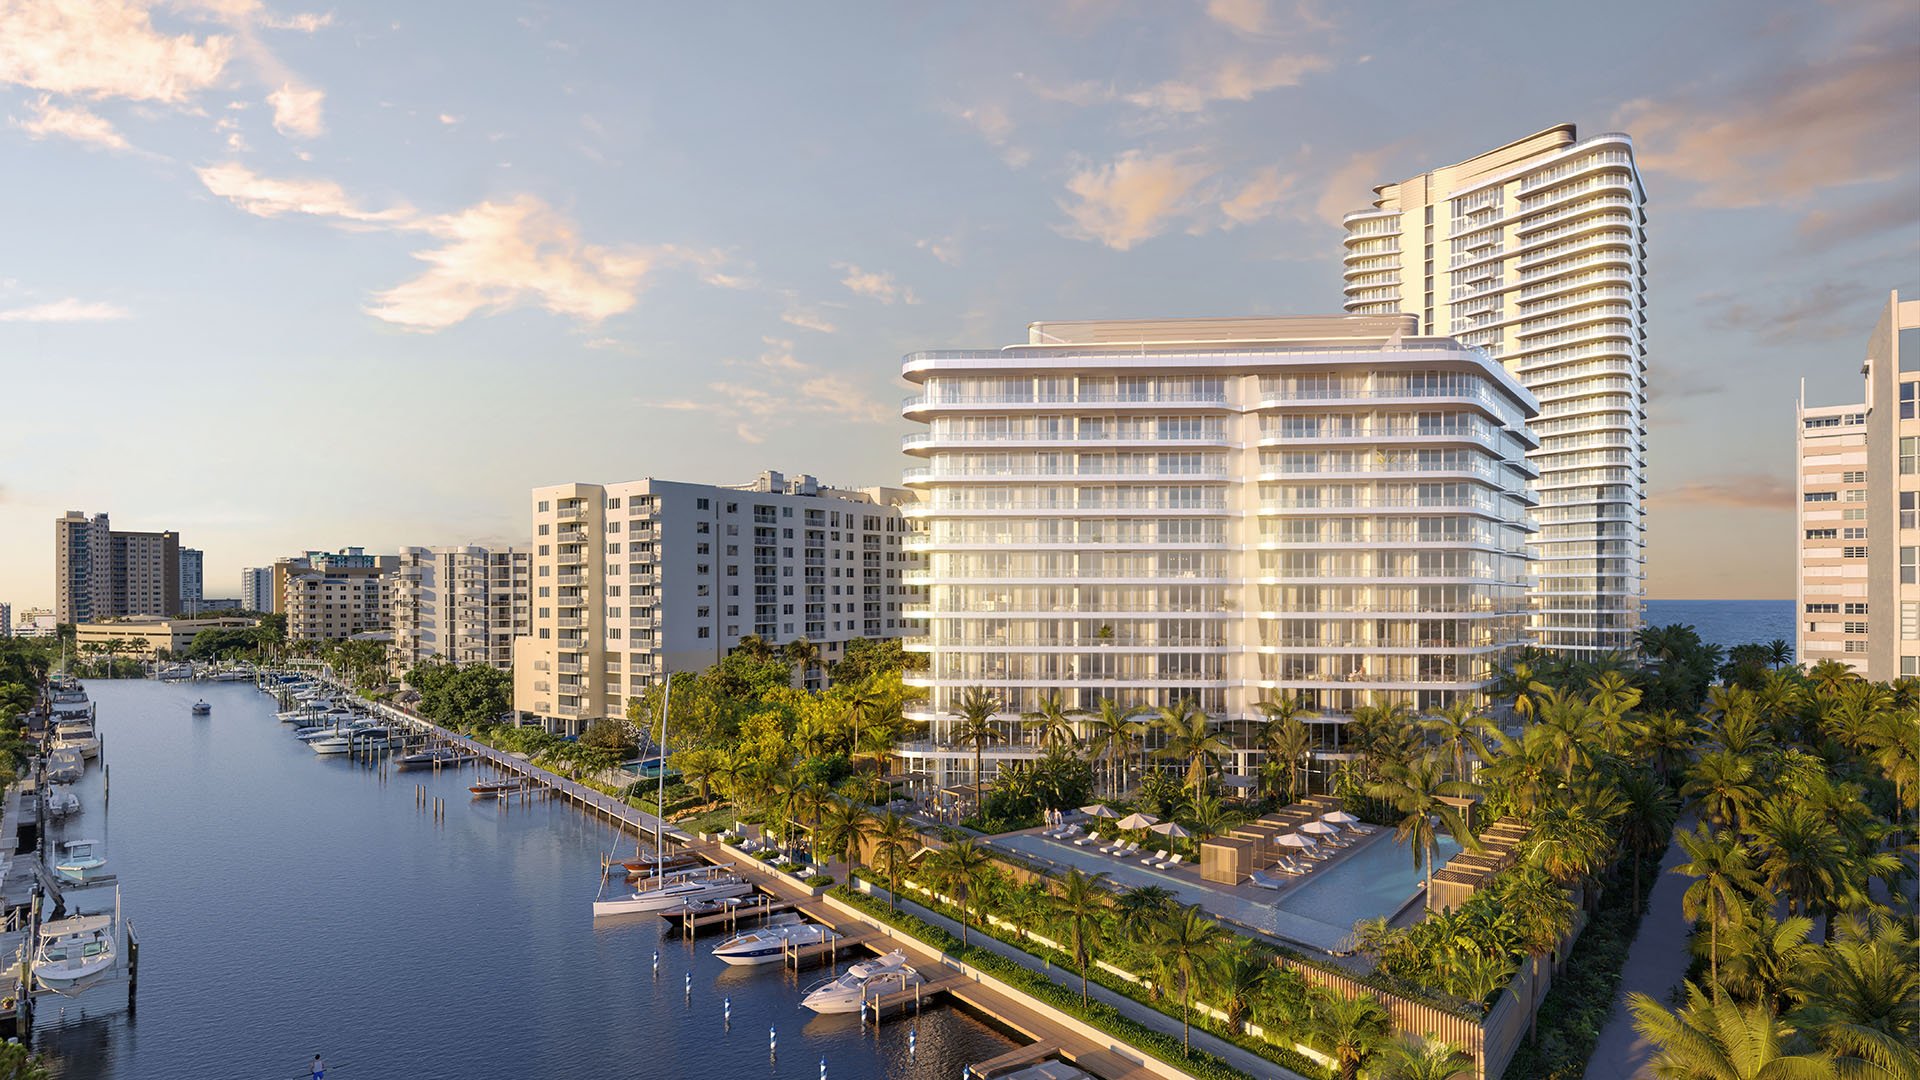
Making Pompano Beach the primary residence after Hong Kong is more than a change of address. It is a handover between two properties, two banking environments, and deadlines that may not align. The essential distinction is between wealth tied to the Hong Kong home and liquidity available to complete the Florida purchase.
For a buyer considering The Ritz-Carlton Residences® Pompano Beach, the purchase decision should advance alongside a funding plan, not ahead of it. Before committing to a closing date, establish estimated net sale proceeds, financing requirements, reserve needs, and the intended date of permanent residence. A compelling property does not resolve an uncertain funding sequence.
Expected sale proceeds are not cleared cash or formally committed financing. Keeping those categories separate makes the purchase timetable more credible and helps prevent relocation expenses from consuming funds needed at closing.
The conservative approach is to obtain a Hong Kong net-proceeds estimate and confirm U.S. financing requirements before completing the sale. Once the sale closes, document the proceeds, the movement of funds, and any currency conversion before completing the Pompano Beach purchase.
Work from the amount expected to remain after the mortgage payoff and applicable transaction deductions, not the headline sale price. Treat that estimate as provisional until completion documents and bank records establish the actual balance.
This sequence reduces dependence on an unfinished sale. The trade-off is scheduling: the preferred Florida purchase may need to accommodate the sale, transfer, and lender review. Ask the receiving bank and lender what they require before fixing dates. There is no universal cross-border transfer timetable for every transaction.
When evaluating Ocean 580 Pompano Beach, apply the same discipline. Separate the property's appeal from the proposed closing schedule, and assess whether that schedule is compatible with documented, accessible funds.
A bridge loan can cover the interval between purchasing a new home and selling the existing one, provided financing is approved. It can preserve flexibility, but only when the lender has accepted the collateral, repayment obligations, and exit plan.
Bridge underwriting varies. Lenders may assess collateral value, credit history, and debt-to-income ratio. Some place primary emphasis on collateral value, established through an appraisal or broker price opinion. Neither approach means the Hong Kong property will automatically qualify as security for a U.S. loan.
Obtain written confirmation that the proposed lender accepts Hong Kong collateral before relying on that structure. A general willingness to lend to foreign nationals does not answer that question.
Ask how overlapping obligations will be assessed. Where applicable agency bridge-loan rules govern the mortgage, the lender must document the ability to carry payments on the existing home, new home, bridge loan, and other obligations. Under those rules, the bridge cannot be cross-collateralized against the new property. Confirm the rules governing the actual loan rather than treating them as universal.
Model a delayed Hong Kong sale as well as an on-time completion. The question is not simply whether the bridge supplies the purchase money, but whether the household can sustain the overlap without exhausting its reserves.
Foreign-national financing is not a single product category. Documentation can include a passport, visa or visa-waiver evidence, identification, and foreign credit or bank references. Eligibility depends on the individual program.
An investor or debt-service-coverage loan offering does not establish that an owner-occupied primary-residence mortgage is available. State the intended use clearly at the outset and obtain confirmation that the proposed product fits it.
For a purchase under consideration at Armani Casa Residences Pompano Beach, the underwriting conversation should begin with occupancy intent and borrower eligibility, not merely the desired loan amount. Request the documentation checklist and funding conditions before treating the financing as dependable.
Keep the purchase contribution distinct from reserves. Some foreign-national programs require evidence of both, so an account balance sufficient for the down payment may still fall short of the lender's total liquidity requirement. Ask which funds must remain available after closing.
Proof of funds should explain both the available balance and its origin. Bank statements and documented sale proceeds can form part of acceptable evidence, subject to lender requirements. Traceability matters: unexplained cash deposits should not be treated as substitutes for a documented funding history.
Prepare one coherent file containing the Hong Kong sale agreement, completion statement, mortgage-payoff evidence, relevant bank statements, currency-conversion records, and wire confirmations. The file should allow the reviewer to trace the proceeds from sale to receiving account without unexplained gaps.
Ask separately what evidence is needed at offer, underwriting, and closing. An anticipated sale may explain the funding plan, but it should not be described as cash already available. Likewise, distinguish a financing discussion from a formal commitment and confirm any outstanding conditions.
Seasoning also requires a specific answer. Some foreign-national programs describe moving funds into a U.S. account 30-60 days before closing. That is neither a universal mortgage requirement nor proof that the same period applies to a primary-residence loan. Obtain the selected lender's exact account-location, seasoning, and documentation requirements before arranging transfers.
The funding calendar and the homestead calendar are separate. In Broward, eligibility turns on ownership and whether the property is the owner's permanent home, or an eligible dependent's permanent home, as of January 1. Purchasing the residence alone does not establish eligibility.
The standard application deadline is March 1 of the tax year for which the exemption is sought. The seller's exemption does not automatically transfer. The purchaser must apply independently through the county property appraiser and supply the required documentation.
If ownership and permanent residence are not established by January 1, the buyer generally cannot claim homestead for that tax year. Do not substitute a broad assumption about spending most of the year in Florida for the permanent-residence requirement.
When considering Waldorf Astoria Residences Pompano Beach, verify the actual ownership and occupancy timetable rather than assuming a purchase commitment establishes either. Keep financing approval, legal ownership, and permanent-residence eligibility as distinct milestones.
For a considered Pompano Beach property search aligned with your relocation priorities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationConfirm estimated Hong Kong net proceeds and U.S. financing requirements, complete the sale, then document cleared proceeds and transfers before closing the Pompano Beach purchase.
A bridge loan can cover the gap between purchases and sales when approved. Confirm collateral eligibility, repayment capacity, and the exit plan before relying on it.
Do not assume it will. Obtain written confirmation from the proposed lender before building the purchase plan around that collateral.
Applicable agency bridge-loan rules require documented capacity to carry the existing home, new home, bridge loan, and other obligations. Confirm which rules apply to the selected financing.
No. An investor or debt-service-coverage program does not establish that an owner-occupied mortgage is available; confirm intended occupancy and program eligibility separately.
Some foreign-national programs describe that seasoning period, but it is not universal. Obtain the selected lender's exact timing and account requirements.
Retain the sale agreement, completion statement, mortgage-payoff evidence, bank statements, currency-conversion records, and wire confirmations. Confirm the lender's specific documentation requirements.
Not necessarily. Some foreign-national programs require evidence of reserves as well as the down payment, so confirm what must remain available after closing.
They generally must be established by January 1 of the relevant tax year. Buying the property without establishing permanent residence is not enough.
No, the purchaser must apply independently through the Broward County Property Appraiser. The standard application deadline is March 1 of the tax year for which the exemption is sought.