A buyer-focused guide to separating purchase deposits from ownership assessments at Bahia Mar, evaluating seller credits, and defining any negotiated escrow holdback without assuming unpublished protections.
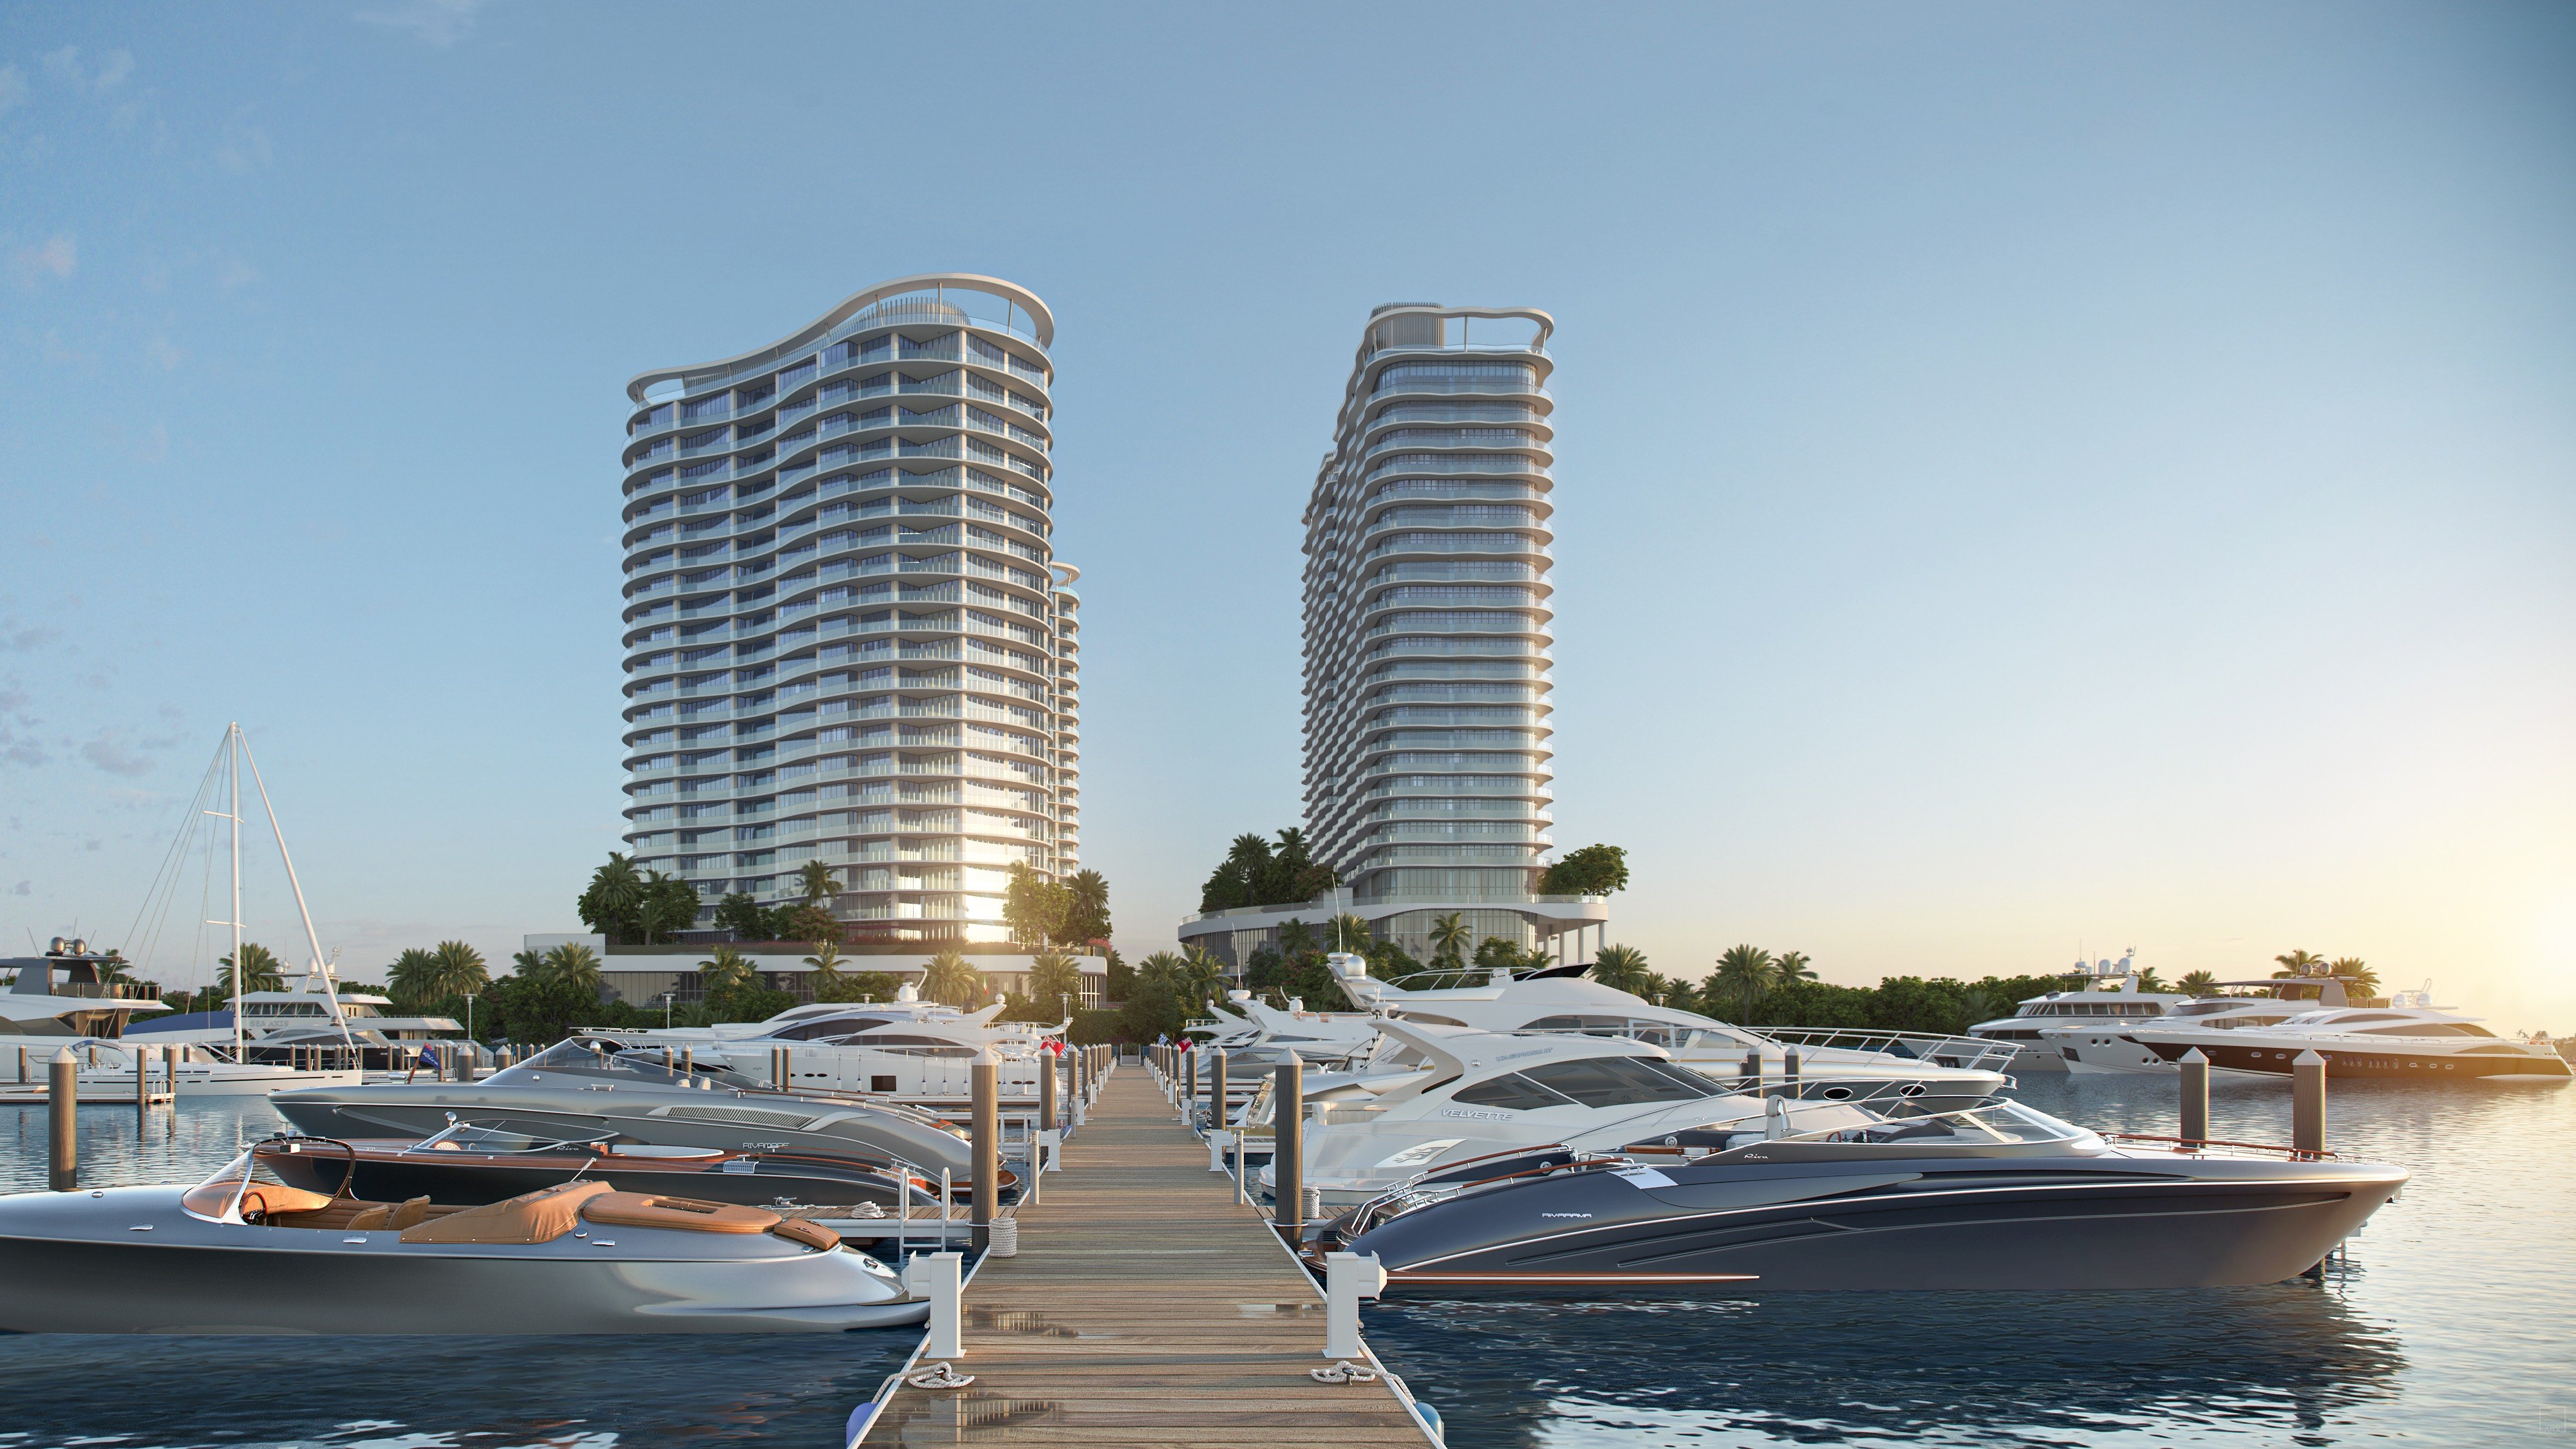
At St. Regis® Residences Bahia Mar Fort Lauderdale, long-term ownership deserves the same scrutiny as the residence itself. Bahia Mar is a planned $2 billion, multiphase redevelopment combining residences, a hotel, marina, and commercial uses across roughly 40 acres of land and water. That scale makes clarity about financial responsibilities essential.
Three distinctions should guide a purchase: purchase-price deposits are not association assessments; a seller credit does not necessarily offset future dues; and an escrow account is not, by itself, a completion guarantee. No fixed project-wide special-assessment schedule, universal closing-credit schedule, or uniform buyer escrow-holdback program is publicly identified. Those disclosure gaps establish neither a prohibition nor a promise.
The objective is to establish what the buyer owes, when payment is due, and what contractual protection applies if obligations or delivery conditions change.
The initial private-residence offering comprises two planned 23-story towers with 80 residences each, featuring three- and four-bedroom-plus-den layouts of approximately 2,600-3,550 square feet. The broader development encompasses four planned condominium towers totaling 320 units, plus 79 furnished hotel residences. These figures describe different scopes, not interchangeable versions of the initial offering.
Private Residences and the Resort Collection are also distinct product categories. Buyers should request the budget and governing documents for their specific residence rather than assume both categories share an ownership-cost structure.
For a purchaser also considering Four Seasons Hotel & Private Residences Fort Lauderdale, the useful comparison rests on the documents: identify each property's applicable charges and contractual obligations independently. Brand recognition does not establish equivalent financial terms.
The advertised HOA estimate for the boutique towers is $2.00 per square foot. Treat that figure as provisional, not as a verified final association budget. Both the billing period and included charges require confirmation.
If the figure is monthly, a 3,000-square-foot residence would imply $6,000 per month. That is an illustration, not a quoted carrying cost. Before using it in a purchase model, obtain written confirmation of the applicable area measurement, payment frequency, and included expenses.
The Master Association's formation and operation require payment of assessments. The central question is whether the advertised HOA estimate already incorporates a master-association allocation. Adding a separate master charge without checking could overstate the budget; assuming it is included could understate it.
Request a consolidated schedule separating residence-level assessments, master-association obligations, and separately charged amenities. Any unresolved amount should remain an open diligence item, not silently become zero in the ownership model.
Beach-club use and access may require fees beyond regular assessments. This establishes neither universally included access nor a universally mandatory extra charge. Request the terms applicable to the selected product and intended use.
Marina slip leases require payment beyond regular association assessments and are available on a first-come, first-served basis. A residence purchase therefore confirms neither a slip nor its price.
The planned shared setting also includes approximately 88,000 square feet of waterfront commercial space, an Intracoastal public park, and a 25-foot-wide pedestrian promenade. How each feature's costs are allocated to residential owners is not publicly established. Request the allocation provisions rather than infer responsibility from proximity or access.
No fixed project-wide special-assessment schedule is publicly identified. That does not mean future special assessments are prohibited or unnecessary.
Request written confirmation of any assessment applicable to the residence, including its purpose, amount, approval status, installment dates, and unpaid balance. Keep regular assessments, supplemental amenity charges, and any special assessment separately identified.
One critical contract question concerns an assessment approved before closing but payable afterward. Ask counsel to identify who bears that obligation and whether responsibility follows approval, a payment date, or another expressly negotiated trigger. No project-specific allocation rule is established here.
If a seller offers an offset, document whether it covers the entire obligation or only specified installments. Address the closing adjustment separately from the obligation to pay the association, so the buyer understands both the credit received and the payments still due.
The advertised purchase schedule calls for 15% at contract execution, 15% at groundbreaking, and 10% at top-off, with the remaining balance due at closing. That schedule is subject to change and must be confirmed against the executed contract.
Those installments total 40% before closing. They are purchase-price deposits, not recurring dues or a capital special assessment. Track them in a cash-flow schedule separate from ongoing ownership expenses.
Request the escrow agreement and deposit-release provisions. Establish where funds are held, when release is permitted, and which contractual conditions govern it. The advertised percentages alone do not answer those questions.
No project-wide schedule of closing-cost credits, interest-rate buydowns, or association-fee credits is publicly identified. Potential reimbursement of qualifying buyers' air travel and hotel accommodation does not establish a universal closing credit or assessment waiver.
For any proposed concession, request written terms specifying the amount, eligible expenses, payment timing, qualification conditions, and treatment if eligible costs fall below the offered credit. Clarify whether it offsets an assessment or simply reduces closing costs.
Keep a one-time concession distinct from the ongoing ownership budget. It may improve acquisition economics without changing future assessments.
No uniform buyer escrow-holdback program for punch-list work, marina completion, or amenity delivery is publicly described. Buyers should not assume the developer accepts requested holdbacks.
If a holdback is available through negotiation, counsel should define the amount retained, the precise work or delivery obligation covered, the escrow holder, and objective release conditions. The agreement should also address a completion deadline, evidence required for release, partial releases if permitted, and a dispute procedure. These are proposed negotiating points, not established Bahia Mar terms.
A deposit escrow and a negotiated completion holdback serve different purposes. Establish which protection is documented before assigning it value in the purchase decision.
Even when comparing Bahia Mar with St. Regis® Residences Sunny Isles, keep the review property-specific. A shared brand is not evidence of shared assessment, credit, or escrow provisions.
The final file should reconcile the applicable budget, master charges, amenity terms, assessment allocation, written concessions, and any accepted holdback. For long-term ownership, precision is part of the luxury.
For a discreet discussion of your South Florida residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationPublic-facing materials do not identify a fixed project-wide special-assessment schedule. That does not establish that future special assessments are prohibited or unnecessary.
No verified final association budget is established by that advertised estimate. Buyers should confirm the billing period, applicable area measurement, and included charges.
If the $2.00-per-square-foot figure is monthly, it would imply $6,000 per month. This is illustrative and requires confirmation of the billing period and inclusions.
Master Association assessments are required, but buyers should confirm whether an allocation is already included in the advertised HOA estimate. Do not add a separate charge without checking.
Beach-club use and access may involve additional fees. Marina slip leases require additional payment and are available on a first-come, first-served basis.
The advertised schedule is 15% at contract execution, 15% at groundbreaking, and 10% at top-off, with the balance due at closing. It is subject to change, and these payments are purchase deposits rather than assessments.
No published project-wide schedule of closing-cost, interest-rate buydown, or association-fee credits is identified. Potential qualifying travel reimbursement should not be treated as a universal closing credit.
No project-specific allocation rule is established here. Buyers should have counsel identify the applicable contract language and document responsibility for later installments.
The public materials do not establish a uniform holdback program or that the developer accepts buyer-requested holdbacks. Any accepted arrangement needs written amounts, release conditions, deadlines, and dispute procedures.
They are distinct product categories, and a common cost structure should not be assumed. Request the budget and governing documents applicable to the selected residence.