Shorecrest’s $157 million construction financing is a documented milestone, not a substitute for ownership diligence. Buyers should distinguish contractual dispute provisions from actual litigation, investigate insurance assumptions, and obtain separate guidance on purchaser financing.
A waterfront residence should offer more than a compelling arrival. For the long-term owner, its appeal also rests on clear obligations, carefully structured governance, and a firm distinction between what is promised and what is documented. At Shorecrest Flagler Drive West Palm Beach, those distinctions are central to evaluating a purchase.
The information provided here does not establish a Shorecrest-specific lawsuit, active insurance-renewal negotiation, or lender response to either. These subjects should therefore remain diligence questions, not presumed events. That distinction does not establish that litigation, claims, or insurance issues are absent. It defines what a buyer should investigate without turning uncertainty into an allegation.
The documented lender action is substantial: the closing of a $157 million construction loan, announced on February 18, 2026, with GoldenTree Asset Management providing the financing. Understanding what that facility does-and does not-establish is the starting point for a measured ownership decision.
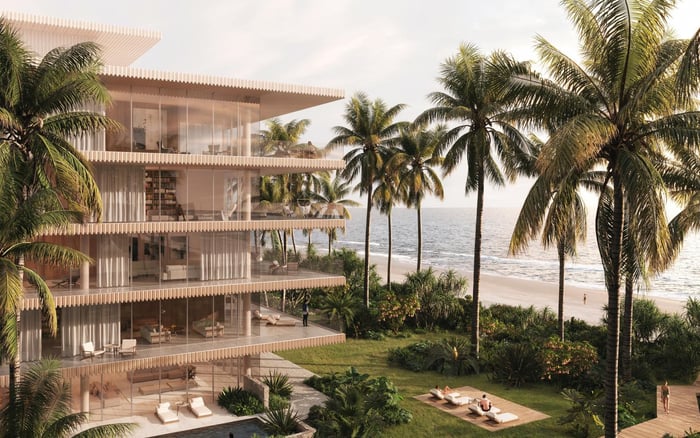
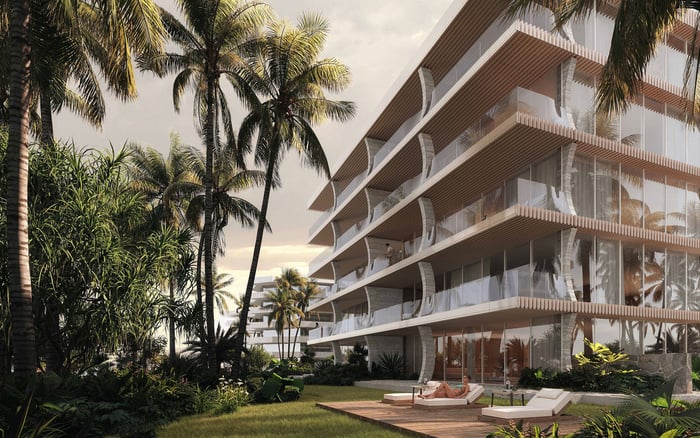
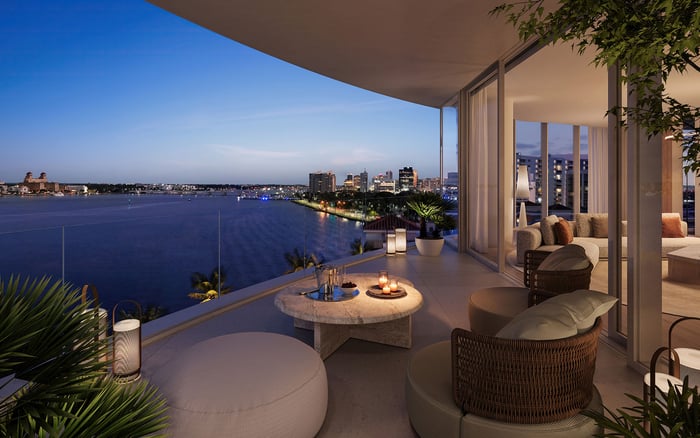
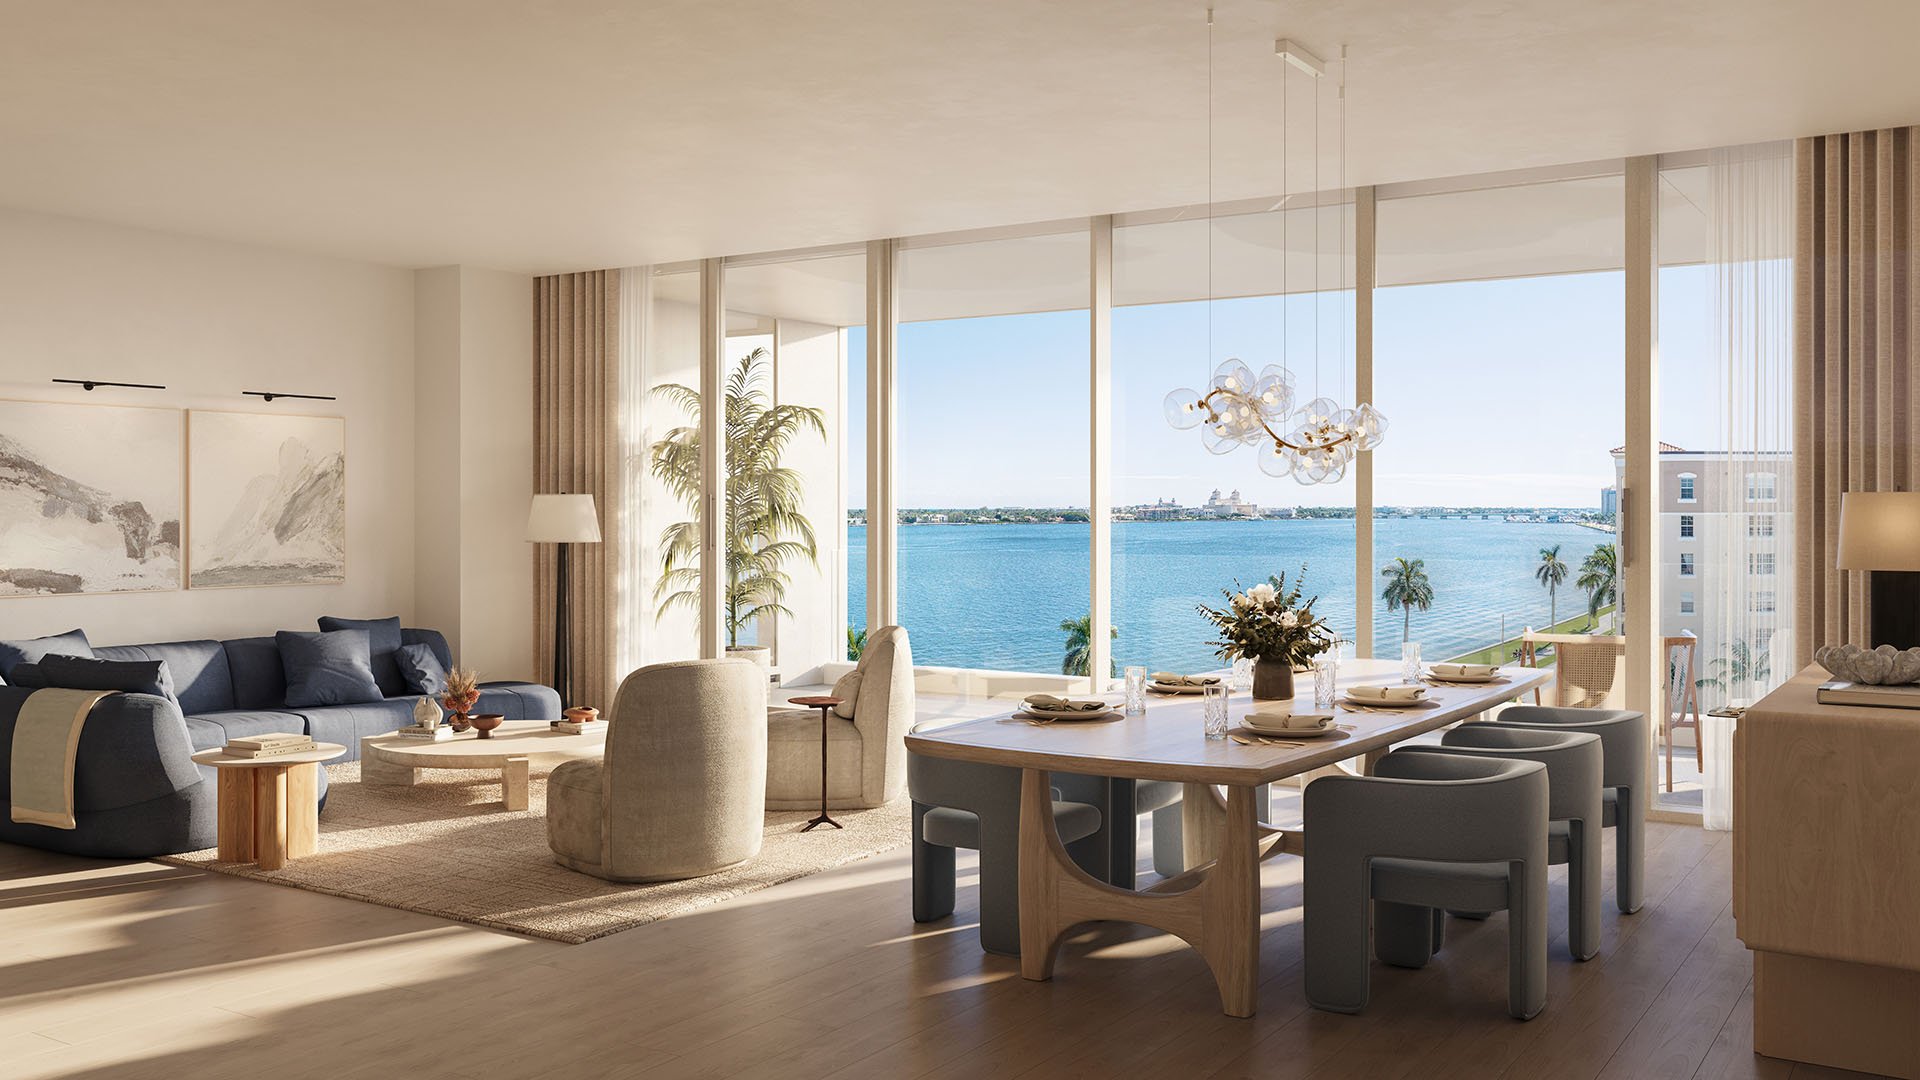
Shorecrest is a Related Ross waterfront condominium development on North Flagler Drive in West Palm Beach, planned as a 28-story tower with 98 residences. The architecture is by Roger Ferris + Partners, with interiors by Rottet Studio. Planned amenities and services include a partnership with Equinox.
Before moving from architectural appeal to legal commitment, reconcile the property’s identifying details. Both 1865 North Flagler Drive and 1901 North Flagler Drive appear in project descriptions. Buyers should not assume that either address identifies the sales gallery or the development parcel without confirmation. Ask counsel to reconcile the legal description, parcel identification, contract address, and seller identity.
The website terms identify 1901 N Flagler LLC for certain website-related matters. That reference is no substitute for identifying the parties to the purchase agreement and their contractual responsibilities. Establish who owes each obligation and which executed document governs it.
Shorecrest’s website terms contain arbitration and class-action-waiver provisions with an opt-out mechanism. They also provide for Palm Beach County courts for matters not subject to arbitration. These are contractual provisions, not evidence of an actual construction dispute.
The purchase agreement requires a separate legal review. Ask counsel to identify its dispute-resolution process, notice requirements, applicable deadlines, remedies, and any limitations on claims. Do not assume the website’s opt-out mechanism applies to the residential purchase contract or that the two documents allocate rights identically.
For litigation diligence, request current written disclosures concerning the relevant seller, development entity, project, and association, as applicable. If a matter is disclosed, ask what it concerns, which parties are involved, what relief is sought, and whether any financial exposure or insurance response has been identified. Counsel can then assess its relevance to the purchase rather than treating every dispute as equivalent.
A useful response is specific and dated. Broad reassurance cannot replace a review of the underlying documents, and an absence of disclosure is not conclusive proof that no issue exists.
Insurance-renewal negotiations should not be described as an established Shorecrest event based on the information provided here. Buyers should instead ask which coverage arrangements exist today, which are contemplated for completed operations, and which figures in the proposed ownership budget remain estimates.
Request the applicable master-policy documents or proposed coverage terms, along with premiums, limits, deductibles, exclusions, and renewal dates. Ask the insurance adviser to distinguish construction-period coverage from coverage intended for the operating condominium. Where policies have not yet been placed, request the assumptions behind the budget rather than treating an estimate as a binding quote.
The practical questions extend beyond the annual premium. How would a deductible be funded? Which responsibilities would fall to the association, and which to an individual owner? What claims history is available and relevant? What happens to the ownership budget if renewal pricing or coverage terms differ from initial assumptions? These are questions to resolve through the governing documents and insurance professionals, not established Shorecrest liabilities.
A buyer also considering Alba West Palm Beach should apply the same document-based review. The comparison should test the completeness of each ownership-cost picture without assuming equivalent coverage or any particular insurance difficulty at either property.
The $157 million facility is intended to enable construction to proceed. It marks a construction-financing milestone, not approval of individual purchasers’ mortgages or confirmation of eligibility for end-loan programs.
The distinction matters even to a cash buyer contemplating future refinancing or resale. GoldenTree’s commitment does not guarantee future insurance costs, assessments, construction quality, or resale liquidity. Nor does it demonstrate a lender reaction to litigation or insurance negotiations that have not been substantiated here.
Required presales, loan-to-cost ratio, interest rate, maturity, extension options, completion guaranties, and lender remedies are not specified in the financing details provided here. Do not infer those terms from the loan amount alone. Ask counsel which financing-related protections or disclosures are relevant to the purchase agreement and available for review.
For a financed purchase, obtain written guidance from the intended mortgage lender on its project-review requirements, necessary insurance documentation, outstanding conditions, and approval timing. Ask whether its response concerns the borrower, the condominium project, or both. A preliminary conversation is not a final commitment.
Long-term ownership diligence should connect insurance, reserves, services, and governance rather than examine each in isolation. Request the proposed operating budget, reserve assumptions, maintenance responsibilities, and any provisions addressing the transition from developer control to owner governance. Ask which costs remain estimates and how owners would be informed of changes.
The planned Equinox partnership belongs in that review as well as in the lifestyle assessment. Buyers should ask how the associated amenities and services are documented, funded, and governed, including what the purchase documents say about changes. The announcement alone does not establish every service obligation or future charge.
For households weighing Shorecrest against Forté on Flagler West Palm Beach, a consistent document request offers a more useful comparison than an assumed ranking of financial security. This is a diligence framework, not a claim that either project faces a particular dispute or cost pressure.
The objective is not certainty about every future expense. It is clarity about known commitments, unresolved assumptions, and who must answer the remaining questions before the buyer proceeds. Architectural distinction and financial discipline should support the same ownership decision.
For a discreet perspective on South Florida residences and long-term ownership priorities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe information provided here does not establish a Shorecrest-specific lawsuit. Buyers should request current written disclosures and obtain legal review rather than infer either a dispute or its absence.
The information provided here does not establish an active insurance-renewal negotiation. Coverage terms, premiums, deductibles, and renewal assumptions should be investigated through project documents and insurance advisers.
GoldenTree Asset Management provided the $157 million construction financing. The closing was announced on February 18, 2026.
No. The construction facility does not establish approval of individual mortgages or project eligibility for end-loan programs.
No. The financing does not guarantee future insurance costs, assessments, construction quality, or resale liquidity.
Project descriptions use both 1865 North Flagler Drive and 1901 North Flagler Drive. Buyers should reconcile the address with the legal description, parcel identification, and purchase agreement.
No. Arbitration, class-action-waiver, and court-venue provisions are contractual terms, not evidence of an actual dispute; the purchase agreement requires separate review.
Request applicable or proposed master-policy terms, premiums, limits, deductibles, exclusions, and renewal dates. Ask which ownership-budget figures are estimates and how deductible obligations would be allocated.
Shorecrest is planned as a 28-story tower with 98 residences, architecture by Roger Ferris + Partners, and interiors by Rottet Studio. Planned amenities and services include an Equinox partnership.
Review the proposed operating budget, reserve assumptions, maintenance responsibilities, and provisions addressing the transition to owner governance. Ask how owners would be informed of changes to costs or services.