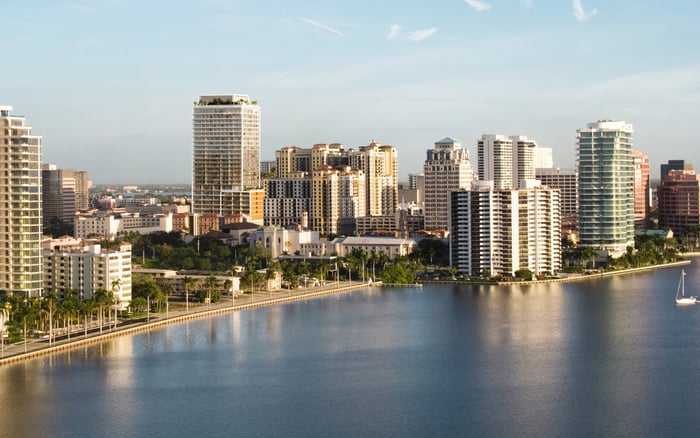
For a family office comparing Palm Beach with West Palm Beach, the disciplined decision begins with intended occupancy, a realistic homestead timetable, property-specific insurance, and a first-year budget that separates recurring costs from acquisition cash needs.
For a family office choosing between Palm Beach and West Palm Beach, the most consequential comparison begins before the architectural shortlist. Will the residence become the family’s permanent home, a seasonal retreat, a guest residence, or a managed asset? The answer should anchor the insurance discussion, homestead strategy, and operating budget-without treating them as interchangeable exercises.
The better acquisition is the one whose ownership plan, coverage, and carrying costs support the family’s actual use. A prestigious address does not resolve a residency question, and a seller’s tax bill does not establish the buyer’s future liability. Nor can a universal Palm Beach premium or West Palm Beach discount defensibly replace property-level underwriting.
A shortlist that includes Palm Beach Residences should therefore begin with the same written brief used for any West Palm Beach alternative: intended occupants, periods of absence, staffing expectations, and the proposed transition to permanent residency, if applicable.
Prepare one occupancy brief for Florida counsel, the specialist insurance broker, and the property manager. Ask each adviser to assess the same intended use, rather than allowing separate conversations to produce inconsistent assumptions.
The broker should confirm how the proposed insurer treats that use and explain the relevant terms, limitations, and obligations during absences. Counsel should assess the homestead position separately. An insurance description does not establish compliance with permanent-residence requirements, and a homestead goal should never dictate an inaccurate account of how the home will be occupied.
For a buyer considering Mr. C Residences West Palm Beach, the practical question is not whether the address suits a seasonal lifestyle. It is whether the planned pattern of use has been accurately presented to the advisers responsible for coverage and eligibility.
Before committing, have unresolved occupancy questions documented. This creates a clear decision point before the family assumes either coverage or tax savings.
Palm Beach and West Palm Beach share the same county exemption administration. Homestead eligibility requires ownership and occupancy as a permanent residence on January 1 of the relevant tax year. Ownership alone is insufficient; occasional visits or belongings kept at the property do not establish permanent residence.
Homestead is not automatic after purchase. Eligible owners must apply with supporting documentation establishing their qualifications. The normal application deadline is March 1, using Form DR-501. Applications may be submitted online, in person, or by mail.
The family office should work backward from these dates. Confirm the intended residency transition, assemble documentation, and review any residency-based exemption claimed elsewhere by the applicant or spouse. Such an exemption can conflict with Florida eligibility and warrants attention before filing-not after savings have entered the budget.
Treat anticipated homestead savings as conditional until eligibility and filing requirements have been addressed. A seasonal acquisition can still be the right lifestyle decision; it should simply be underwritten on its actual circumstances, not an assumed exemption.
A buyer generally does not inherit the seller’s assessed value or homestead benefit. The seller’s bill is useful background, not a basis for the family office’s recurring tax forecast.
Model the acquisition-year bill and the subsequent reassessed tax year separately. Do not assume reassessment changes the bill immediately at closing. Ask the tax adviser to identify the assumptions for each period and distinguish estimated liability from the timing of cash payments.
Save Our Homes limits annual assessment increases on qualifying homesteaded property. It does not eliminate the need to account for reassessment following a purchase.
Municipal and other taxing-authority components also matter. Compare the specific parcel’s taxable value and applicable millage rather than relying on a generic citywide estimate. This is where the Palm Beach versus West Palm Beach comparison becomes useful: two identifiable properties, each with its own tax assumptions, rather than two broad market labels.
Request property-specific quotes using roof age, construction, opening protection, replacement cost, flood zone, elevation, claims history, and actual occupancy. Review coverage limits and deductibles alongside premiums. A lower quoted premium does not establish a like-for-like comparison if the retained exposure differs.
Standard homeowners insurance generally excludes flood damage. Consider flood coverage separately through the NFIP or a private insurer, and have the broker explain how the proposed policies fit together. Keep homeowners, wind, flood, and liability costs visible in the budget while checking how each quoted program packages coverage.
For a condominium under consideration at Alba West Palm Beach, request the association’s master policy and deductibles alongside the proposed unit-owner policy. Review reserve information and special-assessment history as separate diligence items. Resolve these questions through the actual documents, not assumptions drawn from a building’s presentation.
The first layer is recurring ownership cost. Separate property taxes; homeowners, wind, flood, and liability insurance; utilities; landscaping; pool and waterfront maintenance; security; housekeeping; staffing; repairs; and HOA charges where applicable. Obtain quotes or operating records for the relevant line items rather than applying mass-market averages to a luxury residence.
For a residence at Forté on Flagler West Palm Beach, ask which expenses are included in association charges and which remain the owner’s responsibility. Perform the same reconciliation for every condominium candidate to avoid omissions or double counting.
The second layer is acquisition and activation cash: immediate repairs, insurance prepayments, utility deposits, security activation, and specialist inspections. Show these separately from recurring annual expenses, and distinguish payment timing from the underlying cost. Do not count an insurance prepayment again as an additional annual premium.
The third layer is reserves. Set aside a separately identified allowance for repairs and contingencies, informed by inspections and the property’s condition. Keep funded reserves distinct from expenses already committed, so the family can see both expected spending and liquidity retained for uncertainty.
Evaluate each candidate against the same occupancy brief, two-period tax model, insurance review, and first-year cash schedule. Mark unresolved figures as estimates and assign an adviser to resolve each material question.
This approach does not predetermine which city wins. It makes the choice more durable: the family can select the residence it prefers while understanding the obligations attached to it. Lifestyle remains central, but neither projected homestead savings nor an incomplete operating budget should quietly make the decision.
For a discreet exploration of Palm Beach residences and West Palm Beach homes, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The Palm Beach County Property Appraiser administers property-tax exemptions for both cities.
Eligibility requires ownership and occupancy as a permanent residence on January 1 of the relevant tax year. Ownership alone does not establish eligibility.
No. Eligible homeowners must apply and provide supporting documentation establishing their qualifications.
The normal deadline is March 1, using Form DR-501. Online, in-person, and mailed application options are available.
Yes. A residency-based exemption claimed elsewhere by the applicant or spouse can conflict with Florida eligibility and should be reviewed before filing.
Not without adjustment. Buyers generally do not inherit the seller’s assessed value or homestead benefit, so acquisition-year and subsequent reassessed-year taxes should be modeled separately.
No. It limits annual assessment increases on qualifying homesteaded property but does not remove the need to account for reassessment following a purchase.
Standard homeowners insurance generally excludes flood damage. Flood coverage should be considered separately through the NFIP or a private insurer.
Request the association’s master policy and deductibles alongside the proposed unit-owner policy. Review reserve information and special-assessment history as part of the same diligence exercise.
Separate recurring ownership expenses, acquisition and activation cash needs, and reserves. Track prepayments carefully to avoid counting the same expense twice.