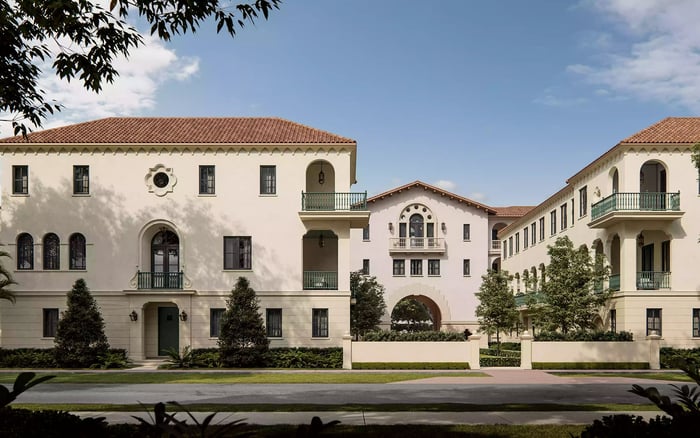
A considered move from Melbourne to Coral Gables begins with more than a down payment. Coordinate closing reserves, property-specific insurance, substantive title review, and financing deadlines to keep the purchase aligned with your relocation plans.
Leaving Melbourne for Coral Gables calls for a financial plan as considered as the residence itself. The purchase price is only one part of that plan. Closing expenses, insurance arrangements, title requirements, and financing conditions must stay aligned, particularly when relocation decisions depend on a predictable completion date.
For a relocation of this scale, buyer's guides are most useful when they distinguish attractive properties from the obligations of purchasing them. A shortlist that includes Ponce Park Coral Gables should therefore come with a transaction checklist, not simply a preferred floor plan. The relevant questions concern the actual contract, the property being acquired, and the lender's requirements-not assumptions about a project's closing arrangements.
The objective is straightforward: keep funds available, identify unresolved conditions early, and prevent the moving schedule from outrunning the purchase agreement.
A substantial down payment does not cover the other expenses of buying. Buyer-side costs can include appraisal and survey charges, recording fees, lender charges, mortgage taxes, and lender's title insurance. Where financing is involved, documentary stamp tax on the note and intangible tax on the mortgage also commonly enter the calculation.
Set aside a dedicated closing-cost allocation alongside the down payment. Request an itemized estimate from the lender and closing agent, then distinguish confirmed figures from estimates and amounts that depend on contract negotiations. This is more useful than treating a broad percentage of the purchase price as a final cash-to-close figure.
A general 2%-5% planning range offers an initial reference, not a transaction-specific calculation. For a luxury purchase, even a modest percentage difference can materially change the required liquidity. Replace that preliminary range with actual charges as the transaction progresses.
Keep any desired post-closing cushion separate as well. No universal reserve amount applies here, and that cushion should not be confused with closing expenses or reserves the lender may require. Ask the lender to clarify its requirements rather than assuming that cash available for closing answers every liquidity question.
In Miami-Dade, buyers commonly pay the owner's title insurance premium. That is a local convention, not an automatic contractual obligation. Read the allocation in the purchase agreement before building the budget around it.
Florida sets title insurance premium rates, so comparing closing proposals requires more than looking for the lowest policy premium. Examine title-agency fees and other quoted charges separately. Ask each provider to identify the coverage amount and what the total includes.
For illustration, the base schedule of $5.75 per $1,000 on the first $100,000 and $5 per $1,000 on the next $900,000 produces a $5,075 base premium for $1 million of coverage. That figure is not an all-inclusive closing quote; other applicable charges still need to be considered.
The owner's policy protects the buyer's interest; the lender's policy protects the mortgage lender. When both are issued together, simultaneous issuance can reduce the lender-policy charge. The party paying the premium generally has first choice of title or closing agent, subject to lender approval, although buyer and seller may agree to separate agents.
Whether considering The Village at Coral Gables or another residence, confirm these allocations and approvals for the specific purchase rather than carrying expectations from a previous transaction.
Title review does more than confirm that a policy can be purchased. A title examination addresses ownership, use restrictions, easements, defects, and claims that may require action to establish marketable title.
The title commitment identifies requirements and policy exceptions. Ask your attorney or title professional to distinguish items that must be resolved from matters that will remain outside coverage. A policy does not eliminate every property-related risk, and identifying an issue does not mean the eventual insurance automatically covers it.
For a residence under consideration at Cora Merrick Park, the discipline is the same: review the documents for the actual interest being purchased. A project name cannot substitute for property-specific examination.
Request the commitment early enough for meaningful questions and follow-up. This is a practical scheduling recommendation, not a universal deadline. The contract should guide any required objections, responses, or other actions.
Treat insurance as a distinct part of the closing process, not a final-week reminder. Ask the lender what coverage and evidence it requires, and ask the insurance professional what information is needed to quote and bind the appropriate policy. Then align the proposed effective date and delivery of evidence with the closing requirements.
A preliminary quote does not confirm that every binding condition has been satisfied. Request written clarification of what remains outstanding and who is responsible for resolving it. No single homeowners premium or binding deadline applies to every purchase discussed here.
Flood coverage requires separate attention. For federally regulated mortgages on properties in designated flood zones, flood insurance is required. Confirm the property's zone and the lender's requirements rather than inferring them from the neighborhood or the residence's appearance.
Flood insurance is available through private insurers or the National Flood Insurance Program. NFIP coverage is available for structures throughout Coral Gables, not only those within a Special Flood Hazard Area. Availability and mandatory purchase requirements are distinct questions; address both when evaluating protection.
A financing contingency should specify the required loan amount and financing terms, along with relevant property and appraisal conditions. Review those provisions before signing-not after a lender raises a concern.
The lender may require an appraisal supporting the purchase price. Discuss how the contract handles the appraisal condition and what steps are required if financing cannot be obtained within the contingency period. Termination and return of the deposit may be possible, but only as the agreement's language and requirements allow.
If the search broadens to Coconut Grove and The Lincoln Coconut Grove, carry over the review discipline, not assumptions about another property's financing terms.
Maintain a shared calendar of contractual dates, lender milestones, and unresolved items. Address any notice or extension through the appropriate professionals and the actual agreement. An informal expectation is no substitute for contractual protection.
The proposed settlement statement brings together credits, debits, prorations, closing costs, and other charges. Reconcile it against the contract and earlier estimates, requesting explanations wherever figures or allocations have changed.
Before treating the closing as ready, seek confirmation that title requirements, insurance evidence, and financing conditions have been addressed. The strongest relocation plan keeps each part of the closing process in view until the transaction is ready to complete.
For a considered approach to your Coral Gables residential search, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationYes. Appraisal, survey, recording, lender, mortgage-tax, and title-related expenses can require funds in addition to the down payment.
It can serve as an initial reference, but it is not a transaction-specific cash-to-close calculation. Replace it with itemized estimates and reconcile the proposed settlement statement.
Buyers commonly pay the premium, but the purchase contract determines the allocation. Local custom is not itself a contractual obligation.
It represents the base premium for $1 million of coverage under the stated rate schedule. It excludes other applicable charges and is not an all-inclusive closing quote.
No. The owner's policy protects the buyer, while the lender's policy protects the mortgage lender; simultaneous issuance can reduce the lender-policy charge.
Review its requirements and policy exceptions with the appropriate professional. Identify what must be resolved and what will remain outside coverage.
Flood insurance is required for federally regulated mortgages on properties in designated flood zones. Confirm the property's zone and the lender's specific requirements.
Yes. NFIP coverage is available for structures throughout Coral Gables, and flood insurance is also available through private insurers.
Begin early enough to clarify coverage, outstanding conditions, and the lender's evidence requirements. Confirm the effective date and timing for the specific transaction rather than assuming a universal deadline.
No. Termination and return of the deposit depend on the financing contingency's language and compliance with the contract's requirements.