A hurricane-season closing requires more than a confirmed signing appointment. Align deed ownership, succession objectives, insurance treatment, and signing authority before weather introduces pressure into the transaction.
A South Florida residence may be selected for its architecture, setting, and privacy. Its closing deserves an equally considered approach. During hurricane season, the essential question is not simply whether everyone can sign on the scheduled date. It is whether ownership, insurance, succession objectives, and signing authority remain aligned when weather compresses the timetable.
These are separate decisions. The deed establishes ownership. Estate-planning documents address beneficiary objectives. Property insurance defines coverage under its terms. Signing authority determines who may execute particular documents. None automatically resolves the others.
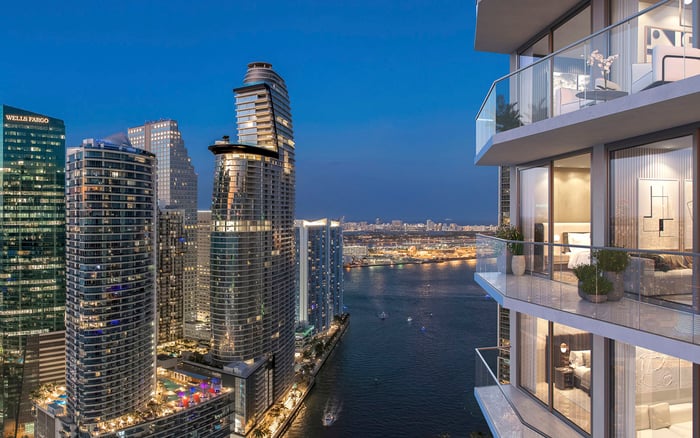
For a buyer considering The Residences at 1428 Brickell, the discipline is the same as for any substantial acquisition: settle the legal structure before the transaction becomes a scheduling exercise. That distinction is especially important when a closing must remain workable through changing weather conditions.
Confirm every grantee's legal name and the intended form of ownership before the deed is prepared. Depending on the circumstances, the structure may involve individual ownership, tenancy by the entireties, joint tenancy with right of survivorship, tenancy in common, or a trust. Entity ownership also requires coordination with the applicable organizational and closing documents.
These choices are not interchangeable labels. Florida recognizes tenancy by the entireties for married owners, but marital status and deed language must support the intended arrangement. Have Florida counsel explain the proposed vesting rather than relying on a familiar structure from another jurisdiction.
Then reconcile the deed with the title commitment and applicable trust, entity, and lender documents. Consistency means accurately reflecting the intended legal owner, not merely repeating a buyer's preferred shorthand. Resolve discrepancies while changes can still receive proper review.
A succession plan and a closing signature answer different questions. Survivorship ownership concerns what happens to an ownership interest. Estate-planning beneficiary designations address succession through the relevant planning documents. Signing authority determines who can act in the transaction now.
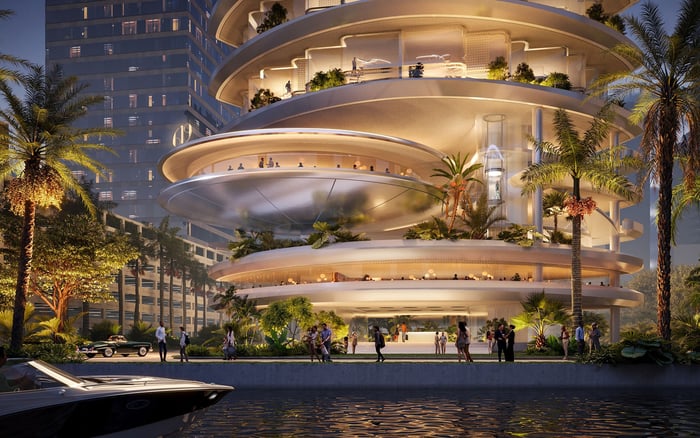
For buyers evaluating Four Seasons Residences Coconut Grove, the acquisition is an opportunity to review these distinctions with counsel. Test a beneficiary objective against the proposed Coconut Grove deed rather than assuming it overrides the deed.
If a trust will own the residence, confirm both the ownership structure and the trustee's authority to sign. Being a beneficiary does not, by itself, authorize someone to execute closing documents. Ask counsel to confirm how the proposed vesting affects succession and who has authority to act, particularly when family members hold different roles.
Homestead can introduce a signing requirement that is not apparent from the title names alone. A married owner generally needs the spouse to join in a homestead conveyance or mortgage, even when that spouse is not a titled owner. Counsel and the closing agent should determine the requirements that apply to the transaction.
This matters when travel plans or storm disruptions could leave a required signer unavailable. Ask counsel whether a proposed power of attorney can support the required homestead documents and what execution formalities apply; a generic document should not be presumed sufficient.
Send any proposed power of attorney to the closing agent and title underwriter early. Request confirmation of its execution formalities, granted authority, and acceptance requirements, along with any lender review. Trust and entity arrangements may require additional scrutiny.
Title insurance and homeowners insurance require separate checks. The title commitment identifies the proposed insured and sets out the requirements and exceptions governing issuance of the title policy. Read it before closing and resolve questions about the intended owner.
Separately, ask the property insurer how actual ownership should be reflected in the homeowners policy. Spouses, a trust, or an entity may require particular treatment. Do not assume that every deed owner must appear in an identical policy capacity or that deed vesting itself establishes coverage.
For a Miami Beach purchase such as The Perigon Miami Beach, the question should be specific: how will this ownership arrangement be insured under this policy? Confirm the lender's required evidence of coverage and mortgagee information before the scheduled closing. A quote or application is no substitute for confirmation that coverage is bound.
Insurers may temporarily stop writing new policies or making certain coverage changes when tropical weather threatens. Confirm binding triggers and geographic restrictions with the particular insurer; buyers should not assume a universal rule applies to every closing.
Request a binder or other lender-approved evidence that coverage is actually bound. If required coverage cannot be secured, review the purchase contract's treatment of weather-related delays with counsel. Obtain a written amendment when necessary rather than relying on an informal understanding that the closing can move.
Do not treat emergency protections for existing policyholders as confirmation of coverage for a newly purchased property or as an automatic extension of the closing date. Keep the buyer's coverage review and contractual timing review separate.
For a second-home acquisition, the execution plan should work even if the buyer cannot travel. Confirm whether each signer will act individually, as trustee, as an entity representative, or under a power of attorney. The signature capacity must match the authority supporting it.
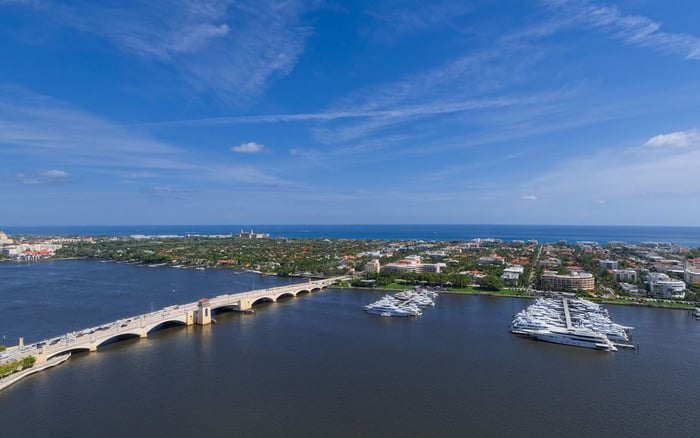
A purchaser considering Alba West Palm Beach should settle the proposed remote-signing process before weather complicates access to the closing appointment. Electronic signing does not eliminate applicable notarization requirements. Ask the closing agent and lender which documents may be signed electronically and which require notarization.
Obtain the lender's and title underwriter's acceptance of the proposed process in advance. Confirm, too, that recordable instruments satisfy applicable requirements and that the closing agent can complete recording and issue the required title coverage. Signed documents alone do not resolve those remaining questions.
If a storm intervenes, recheck the property's condition, document new damage, and resolve the contractual consequences before proceeding. Keep that review distinct from the insurance and title checks; approval in one area does not settle the others.
Before funding, confirm the intended vesting, counsel's succession review, required spousal participation, insurer-approved ownership treatment, evidence of bound coverage, accepted signing authority, and the recording plan. The objective is not speed at any cost. It is a closing whose documents and protections reflect the purchase the buyer intended.
Explore South Florida residences with a considered acquisition perspective at MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationConfirm each grantee's legal name and the intended ownership structure before the deed is drafted. Florida counsel should review the arrangement and its succession implications.
Florida recognizes tenancy by the entireties, but marital status and deed language must support the intended arrangement. Buyers should obtain Florida-specific advice.
Survivorship vesting and estate-planning beneficiary designations are distinct. Counsel should confirm how they interact with the proposed ownership.
Beneficiary objectives and signing authority are separate matters. The closing agent should confirm the signer's capacity and the documents establishing authority.
A married owner generally needs the spouse to join in a homestead conveyance or mortgage, even when the spouse is not a titled owner. Counsel should confirm the requirements for the transaction.
Do not assume it is. The closing agent, title underwriter, and applicable lender should review its formalities, authority, and acceptance requirements in advance.
Ask the insurer how spouses, trusts, or entities should be treated under the particular policy. Deed vesting does not automatically establish insurance coverage.
Request a binder or other lender-approved confirmation that coverage is actually bound. A quote or application alone is not that confirmation.
Review the purchase contract to determine whether it allows additional time when weather prevents binding required insurance. Obtain a written amendment if necessary.
Recheck the property's condition, document new damage, and resolve its contractual consequences before proceeding. Reconfirm coverage, signing arrangements, and the recording plan.