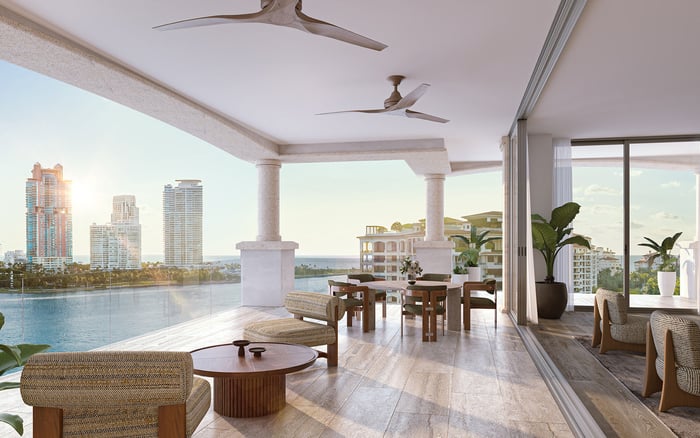
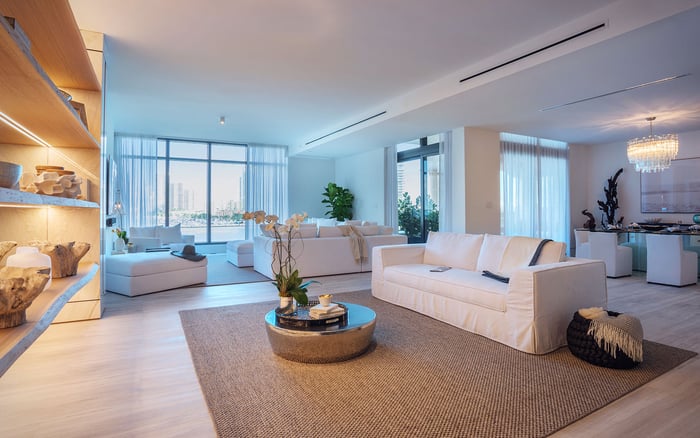
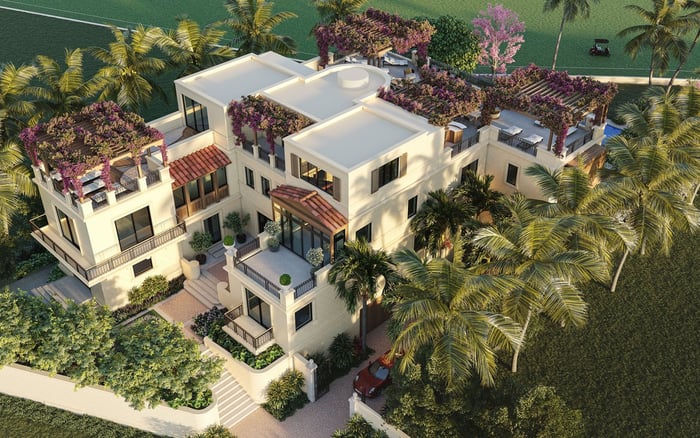
A Boston-to-Fisher Island move calls for more than a change of address. Coordinate federal tax residency, ownership structure and future resale withholding before acquiring a residence, with counsel aligned on both tax exposure and access to sale proceeds.
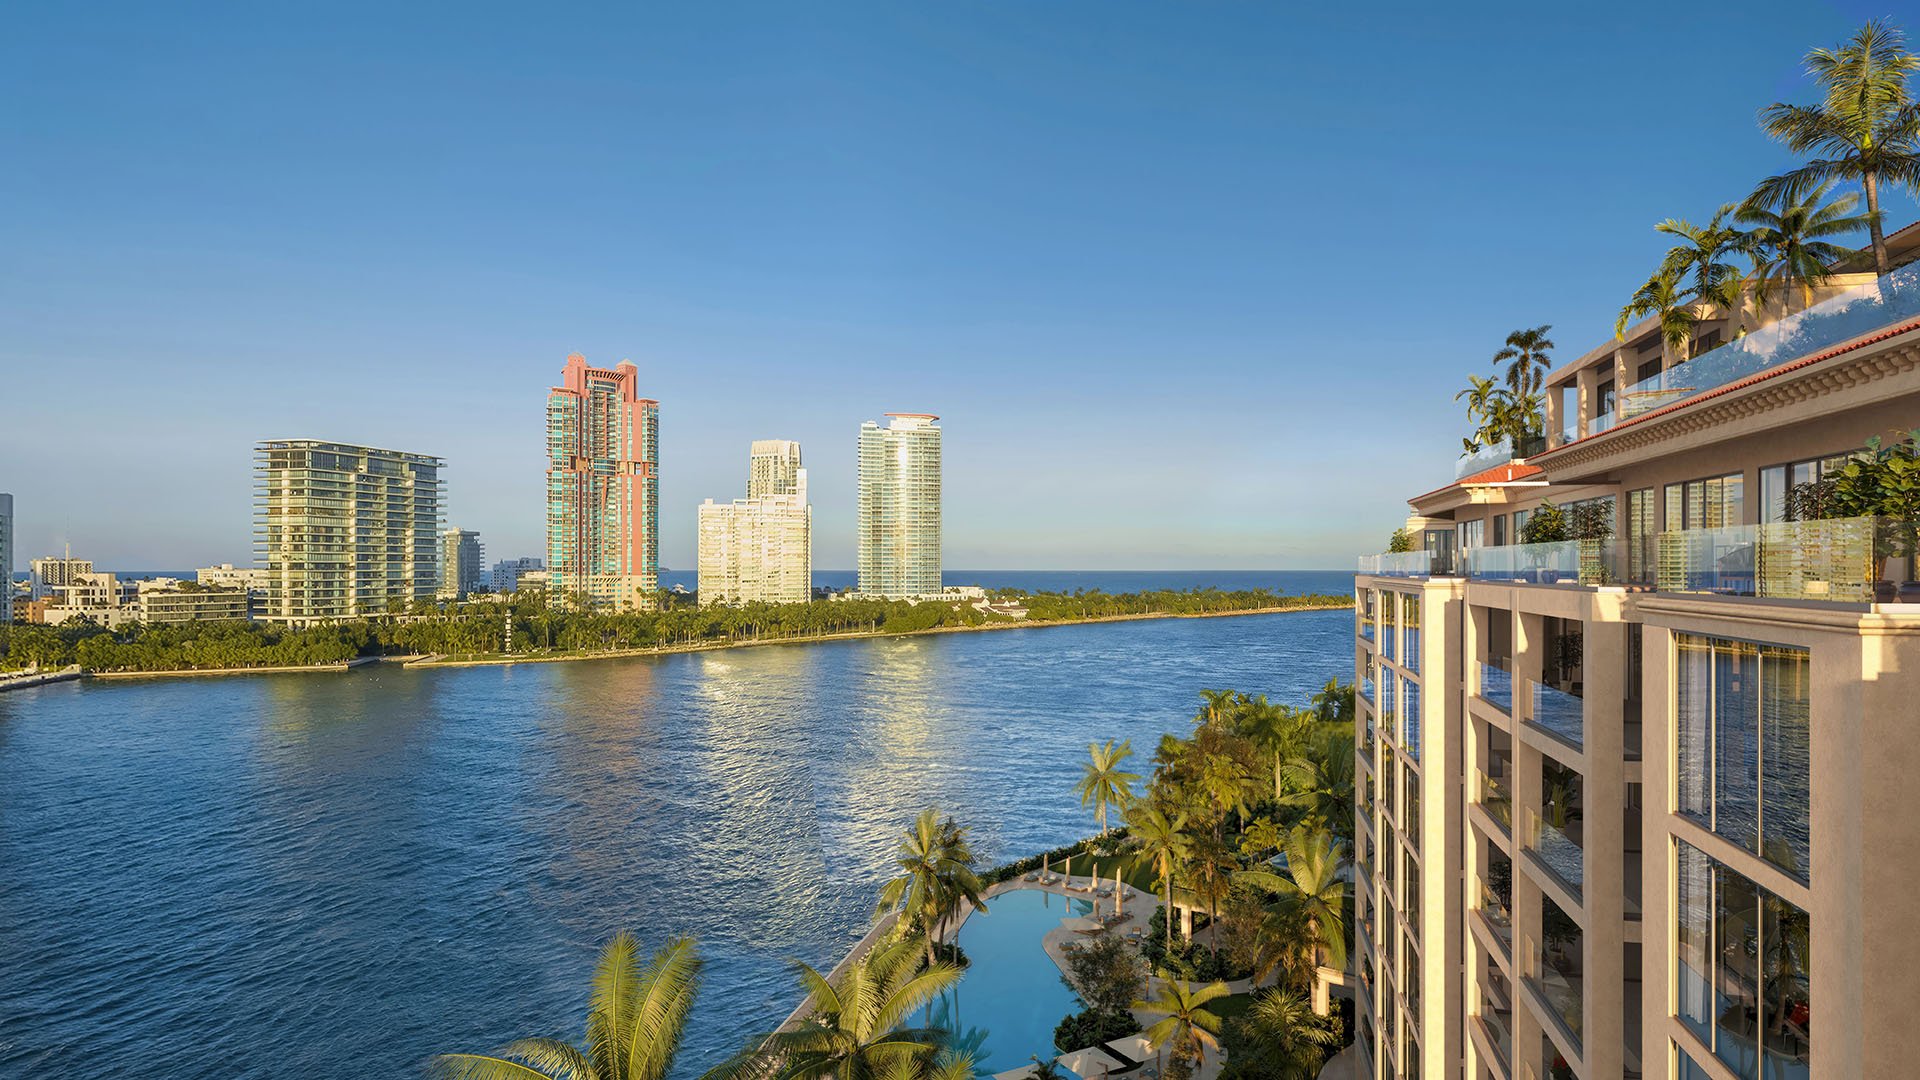
For a household leaving Boston for Fisher Island, choosing a residence is only part of the transition. The ownership decision should anticipate a future sale: who will be the seller, what federal tax status will apply, and how much of the proceeds might be withheld at closing?
Moving between Massachusetts and Florida does not itself determine FIRPTA status. The central question is whether the seller is a foreign person for federal tax purposes when the property is sold. A domestic relocation is neither a FIRPTA trigger nor a solution on its own.
Whether the search centers on Palazzo del Sol or another Fisher Island residence, separate four questions from the outset: state domicile, federal tax residency, buyer-side withholding and the seller’s final tax liability. They intersect, but they are not interchangeable.
A sale by a U.S. person generally does not require FIRPTA withholding. A properly prepared non-foreign certification can establish that status for the buyer. For a straightforward U.S.-person seller, the practical task is documenting status-not assuming that international connections create withholding exposure.
A noncitizen may qualify as a U.S. resident alien under the green-card test or substantial-presence test, subject to exceptions and special rules. The substantial-presence calculation generally counts qualifying U.S. days in the current year, one-third of the preceding year’s days and one-sixth of the second preceding year’s days. It is not simply a count of nights spent in Florida.
Counsel should review the applicable tests and exceptions rather than equate citizenship, immigration status and federal tax residency. Ending long-term U.S. residency or expatriating can introduce separate federal tax and reporting rules. A status change during ownership belongs in the resale plan, even when no sale is imminent.
FIRPTA generally applies when a foreign person disposes of a U.S. real-property interest, including a condominium or residence. Unless an exception or reduced rate applies, the buyer or other withholding agent generally must withhold 15% of the amount realized.
The distinction matters: amount realized is not merely profit, equity or net closing proceeds. It can include cash, other property received and liabilities assumed by the buyer or remaining attached to the property. The seller’s expected cash distribution is not necessarily the withholding base.
For someone considering Palazzo della Luna, the acquisition-stage question extends beyond whether a future sale will produce a gain. Withholding could also temporarily constrain funds intended for the next purchase or another capital commitment.
Withholding and final tax liability are separate. A sale at a loss does not automatically prevent withholding; a certificate or subsequent tax filing may be needed to recover excess withholding. Build the resale liquidity analysis around that distinction.
Certain qualifying buyer-residence transactions receive different treatment. When the amount realized is $300,000 or less, withholding may be eliminated. Above $300,000 and up to $1 million, the rate may be reduced to 10% if the purchase qualifies.
Above $1 million, the standard 15% rate generally applies even when the buyer intends to occupy the property as a residence. These thresholds concern the transaction’s amount realized, not the seller’s gain or equity.
The buyer’s intended residential use is not a universal exemption. Counsel should confirm eligibility before a seller relies on a reduced rate in a proceeds forecast. The contract and closing calculations should reflect the applicable treatment, not an informal assumption that a personal residence falls outside FIRPTA.
A U.S. LLC is not automatically a FIRPTA solution. Its tax classification, ownership and the transaction being undertaken determine the analysis. Domestic formation alone does not answer the withholding question.
Other structures require equally careful review. A buyer acquiring a U.S. real-property interest from a foreign partnership generally must withhold 15% of the amount realized. Stock in a domestic corporation can also fall within FIRPTA when the corporation is a U.S. real property holding corporation, subject to applicable exceptions.
For a purchase at The Links Estates at Fisher Island, ask advisers to explain how the proposed structure would function at acquisition, during ownership and at disposition. Evaluate a structure across its life cycle rather than select it solely for its name or perceived simplicity.
Coordinate U.S. international-tax counsel, estate-planning counsel, a CPA and Florida real-estate counsel before choosing ownership. Their shared task is to identify the taxpayer, clarify classification and align the eventual transaction documents with the tax analysis.
Renting the property can create additional U.S. income-tax and filing obligations, particularly for a nonresident owner. A change from personal use to rental use should prompt a fresh review, not remain solely an operational decision.
If The Residences at Six Fisher Island is under consideration, distinguish the household’s intended use from the proposed ownership structure. Preserve closing records, improvement invoices and any rental depreciation records so advisers have the relevant history when assessing a later disposition.
Federal tax planning does not establish condominium approvals, lender requirements or Massachusetts domicile compliance. Those questions require separate review; an answer in one area is not clearance in another.
An IRS withholding certificate may reduce or eliminate withholding when expected U.S. tax liability is below the otherwise required amount. Form 8288-B is the principal application for requesting that relief on a foreign person’s disposition of U.S. real property.
Consider the application before closing. Processing and escrow arrangements can affect when proceeds become available. A certificate adjusts the withholding obligation; it does not resolve every substantive question about final tax liability.
Before signing a resale contract, coordinate the withholding agent, application responsibilities, escrow handling and treatment of a delayed certificate. Keep residency evidence, entity documents and tax identification information alongside the property’s financial records. Revisit the plan when ownership, federal residency or rental use changes.
The objective is a documented path from purchase to resale, with fewer assumptions about status and fewer surprises over available proceeds. For a Boston household establishing its next chapter on Fisher Island, that preparation belongs beside the architectural and lifestyle decisions-not after them.
Explore Fisher Island residences and refine your South Florida property search with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe move itself does not determine FIRPTA status. The relevant question is whether the seller is a foreign person for federal tax purposes when the property is sold.
A sale by a U.S. person generally does not require FIRPTA withholding. A properly prepared non-foreign certification can establish that status for the buyer.
Yes, a noncitizen may qualify under the green-card test or substantial-presence test. Exceptions and special rules require individual review.
The buyer or other withholding agent generally must withhold 15% of the amount realized unless an exception or reduced rate applies.
No, withholding is based on amount realized rather than profit, equity or net closing proceeds. That amount can include cash, other property and certain liabilities.
Not automatically: qualifying purchases at $300,000 or less may receive an exemption, and those above $300,000 through $1 million may qualify for 10% withholding. Above $1 million, the standard 15% rate generally applies even with residential use.
No, a U.S. LLC is not an automatic solution. Tax classification, ownership and the transaction being undertaken determine the analysis.
Yes, a loss does not automatically prevent withholding. A withholding certificate or subsequent tax filing may be needed to recover excess withholding.
It is the principal application for requesting reduced or eliminated withholding on a foreign person’s disposition of U.S. real property. A certificate changes the withholding obligation, not every aspect of final tax liability.
Coordinate U.S. international-tax counsel, estate-planning counsel, a CPA and Florida real-estate counsel. Review ownership before purchase and revisit it when residency, use or resale plans change.