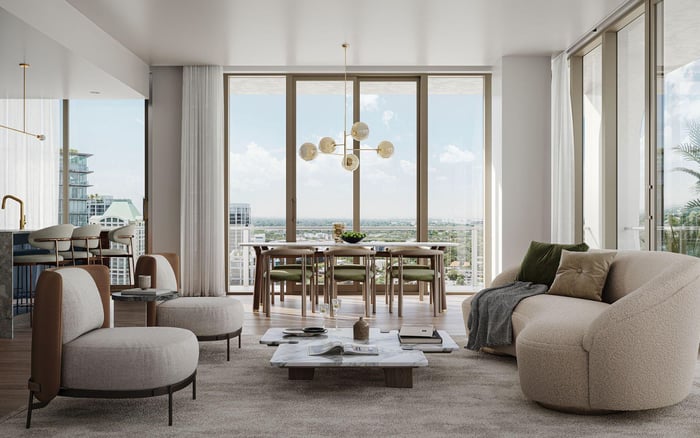
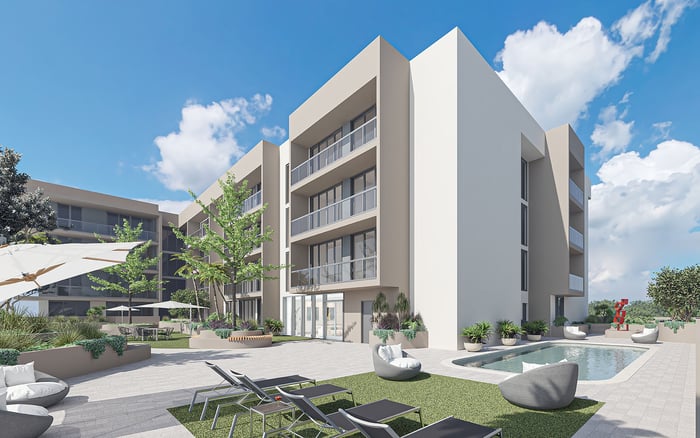
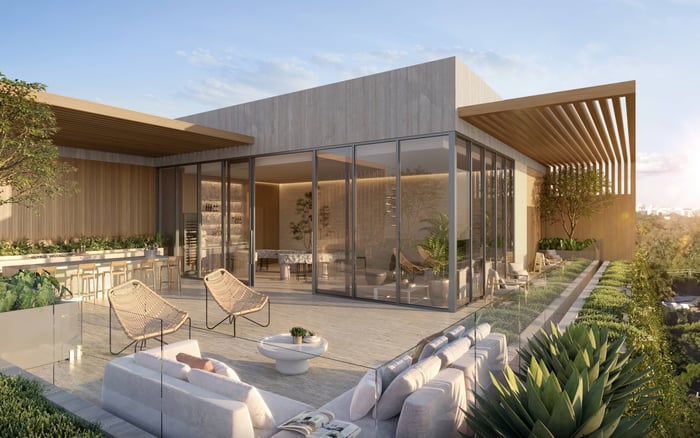
The Lincoln Coconut Grove’s boutique condominium offering invites a closer look at ownership documents, association authority and management economics. Related-party management is a question to investigate, not an established condition at the project.
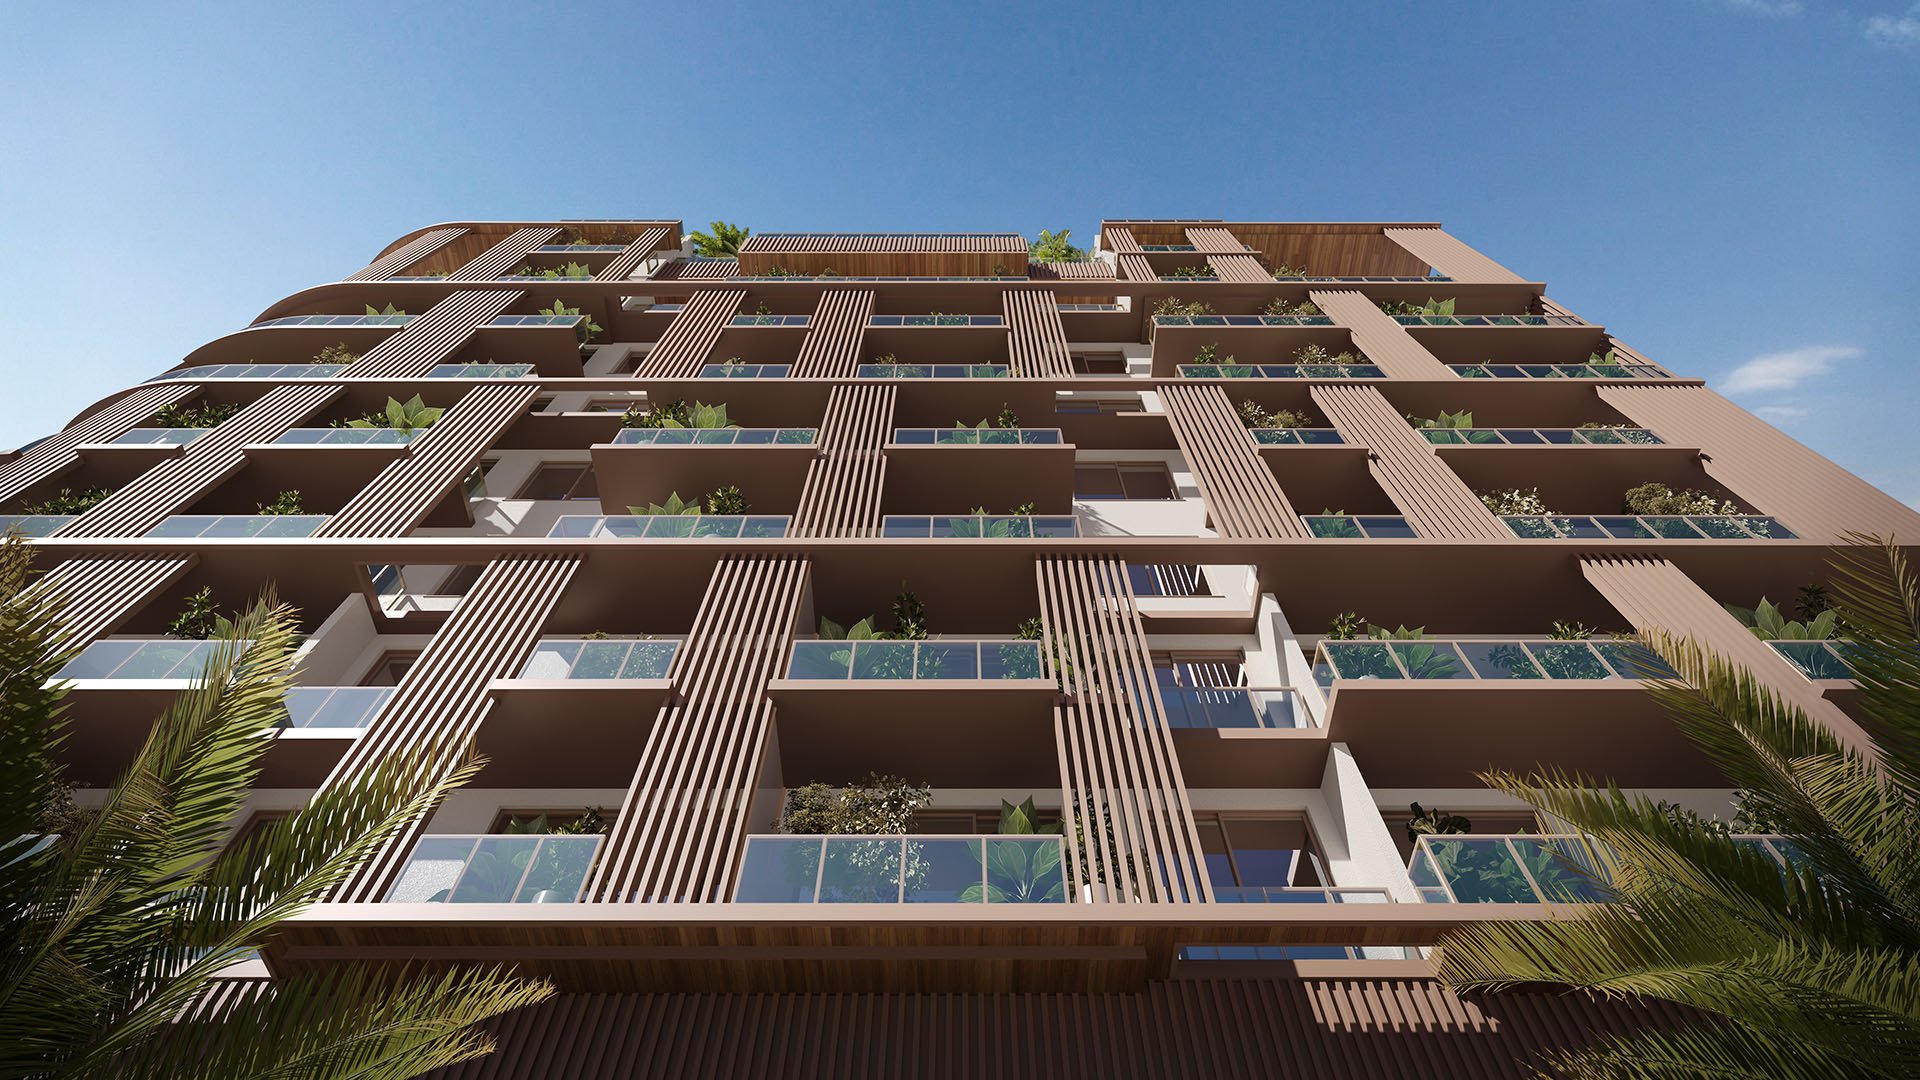
A luxury condominium purchase has two dimensions: the private residence and the arrangements that govern its shared environment. At The Lincoln Coconut Grove, marketed as an eight-story, 48-residence boutique condominium, both deserve attention before capital is committed. The floor plan defines personal space; the governing documents and service agreements help define the ownership experience.
The essential distinction is straightforward: a related-party management arrangement at The Lincoln should not be assumed. The developer lineup does not establish that a future management company is affiliated with the developer. Nor would a confirmed affiliation, on its own, establish unfavorable terms. The buyer’s task is to understand who appoints the manager, who receives payment and what authority owners will ultimately have.
Where possible, that review should begin before signing-not in the final approach to closing.
The Lincoln is marketed as a condominium rather than a condo-hotel product. That distinction matters, but it does not establish the precise ownership estate, rental restrictions or absence of every possible hospitality arrangement. Those questions belong in the transaction documents.
The development site is identified as 3151 SW 27th Avenue, while the completed building is intended to use 2650 Lincoln Avenue. Buyers should have counsel reconcile those identifiers with the legal description, rather than treat an address difference as evidence of a problem.
LORE Development Group and Element Development are the developers. LORE combines Leste Group and Brazil’s Opportunity Fundo de Investimento Imobiliário. The publicly identified entity name, 3151 SW 27AVE PROPCO LLC, provides another point of comparison with the seller named in the purchase agreement. It is not proof of the identity of the association, manager or every contractual counterparty.
Begin with an entity map: the contracting seller, condominium association, proposed manager and material service providers. Request each party’s legal name and a written explanation of any common ownership, control or financial relationship.
The relevant question is not whether names sound connected, but whether the party recommending or approving a contract has an economic interest in the recipient. Ask who negotiates the arrangement, who approves it and how any relationship is disclosed. These are review questions, not findings about The Lincoln.
A buyer also considering Arbor Coconut Grove can apply the same framework without assuming the projects share management structures. Compare documentary answers, not the impression of operational simplicity that boutique positioning may create.
Evaluate a management contract alongside the declaration, bylaws and association provisions. A seemingly reasonable fee is only one part of the bargain. The allocation of authority matters just as much: who selects the manager, who can amend the agreement and who can approve additional services.
Ask counsel to identify the initial association-control structure, the conditions for owner turnover and the treatment of contracts after turnover. These matters cannot be inferred from sales progress or construction milestones. A change in board control should not be assumed to end an existing agreement automatically.
Distinguish the initial term from renewal periods, then examine notice deadlines, termination rights, cure periods and any exit charges. Ask whether termination requires cause and whether assignment can change the service provider without fresh approval. The objective is to understand the actual agreement and applicable law-not to presume that any particular clause exists here.
For a luxury buyer, management value rests on cost, service and accountability. Request an itemized fee schedule rather than rely on a single management line in a proposed budget. Ask whether staffing, administrative services, purchasing, technology or special projects are included or charged separately.
If an affiliation is disclosed, request a clear explanation of compensation and any payments involving connected vendors. Ask how pricing was evaluated, what approvals govern additional spending and what records the association can inspect. A related-party label is no substitute for that economic analysis.
Without the relevant terms, there is no basis to assign The Lincoln a project-specific management premium, contract duration or termination penalty. Equally, a low introductory figure is not evidence of durable savings. Review the budget assumptions and proposed scope of service together.
The advertised payment schedule allocates 10% at contract, 10% after 60 days, 10% at groundbreaking, 10% at top-off and 60% at closing. Under that schedule, 40% of the purchase price falls due before closing. These advertised terms are not a substitute for the buyer’s executed agreement.
That structure makes early document review especially important. Before each payment milestone, ask counsel what documents have been delivered, what has changed and what review or contractual rights apply. Do not assume an unanswered question permits withholding a scheduled deposit.
Launch-era starting prices were approximately $1.5 million; they are not a current availability quote. Completion is estimated around Q3 2028, not contractually guaranteed for that period. Purchase price, delivery obligations and remedies should each be checked separately from management arrangements.
Request the proposed or executed management agreement, including exhibits and amendments; the declaration and bylaws; the association budget; and material service contracts. Seek written clarification of affiliations, selection rights, approval procedures and obligations that could continue after turnover.
If an agreement is not yet finalized, ask how the manager will be chosen and how buyers will receive the eventual terms. Counsel should distinguish an open question from a contractual protection. A sales assurance is not equivalent to an enforceable commitment.
For buyers weighing Opus Coconut Grove alongside The Lincoln, a consistent checklist makes the comparison more useful: identify the obligation, the cost, the decision-maker and the exit mechanism. That approach presumes nothing about either project’s contracts.
The most useful conclusion is not that affiliated management is inherently undesirable. It is that ownership quality depends partly on understandable service obligations, defined spending authority and practical accountability.
At The Lincoln, the prudent position is neither suspicion nor reassurance by association. Confirm the parties, read the operative terms and have Florida condominium counsel assess the buyer’s rights. A well-considered purchase should pair confidence in the residence with clarity about the arrangements supporting daily life.
For a discreet perspective on Coconut Grove ownership opportunities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIt is marketed as an eight-story, 48-residence boutique condominium rather than a condo-hotel. Buyers should still verify the ownership estate and use restrictions in their transaction documents.
An affiliated management arrangement is not established here. The developer lineup alone does not demonstrate a relationship with a management company.
LORE Development Group and Element Development are the developers. LORE combines Leste Group and Brazil’s Opportunity Fundo de Investimento Imobiliário.
3151 SW 27AVE PROPCO LLC is a publicly identified project entity. Buyers should have counsel compare it with the contracting seller rather than assume it represents every party.
The site is identified as 3151 SW 27th Avenue, while the completed building is intended to use 2650 Lincoln Avenue. Counsel should reconcile these identifiers with the legal description.
The advertised schedule is 10% at contract, 10% after 60 days, 10% at groundbreaking, 10% at top-off and 60% at closing. The executed agreement governs the buyer’s obligations.
Review selection and approval authority, compensation, renewal periods, termination rights, assignment and additional charges. Evaluate these alongside the governing documents and applicable law.
Buyers should not assume that it does. Counsel should assess the agreement, governing documents and applicable law to determine how turnover affects contractual obligations.
Approximately $1.5 million was a launch-era starting price, not a current quote, and Q3 2028 is an estimated completion period. Contractual pricing and delivery obligations require separate confirmation.
Begin before signing where possible and revisit unresolved terms before deposit milestones and closing. Ask counsel to distinguish unanswered questions from rights expressly provided by the contract or law.