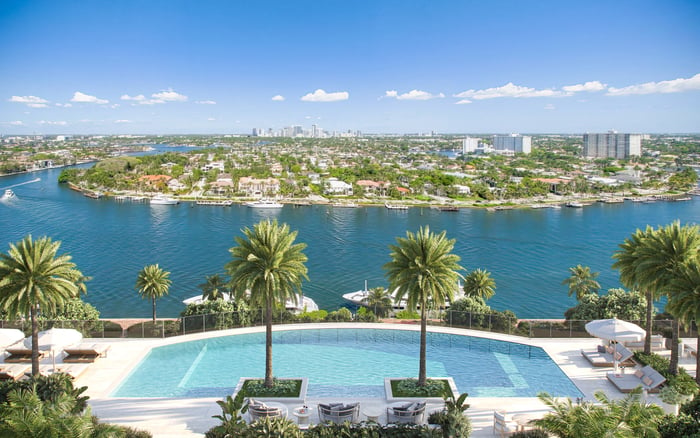
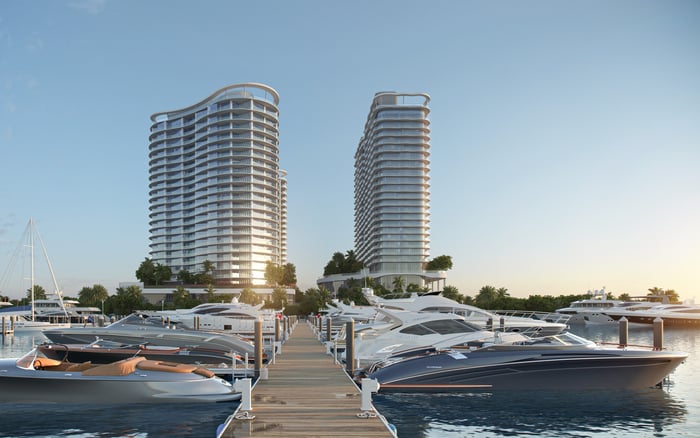
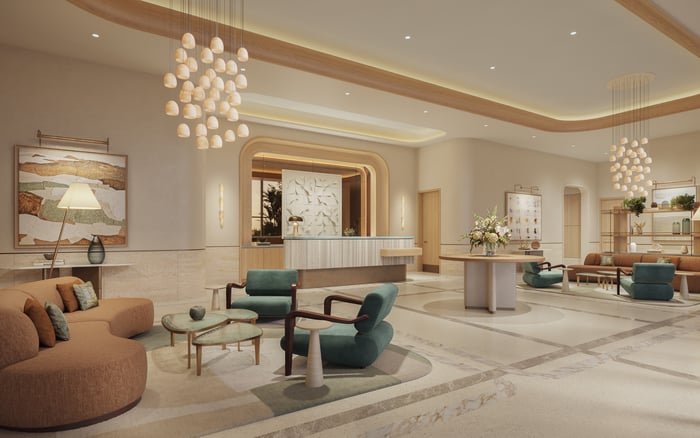
At Bahia Mar, the ownership calculation extends beyond advertised monthly dues to tower and master-association obligations, service inclusions, and separate amenity charges. An initial HOA subsidy is not established, but buyers should understand how any temporary developer support would affect long-term costs.
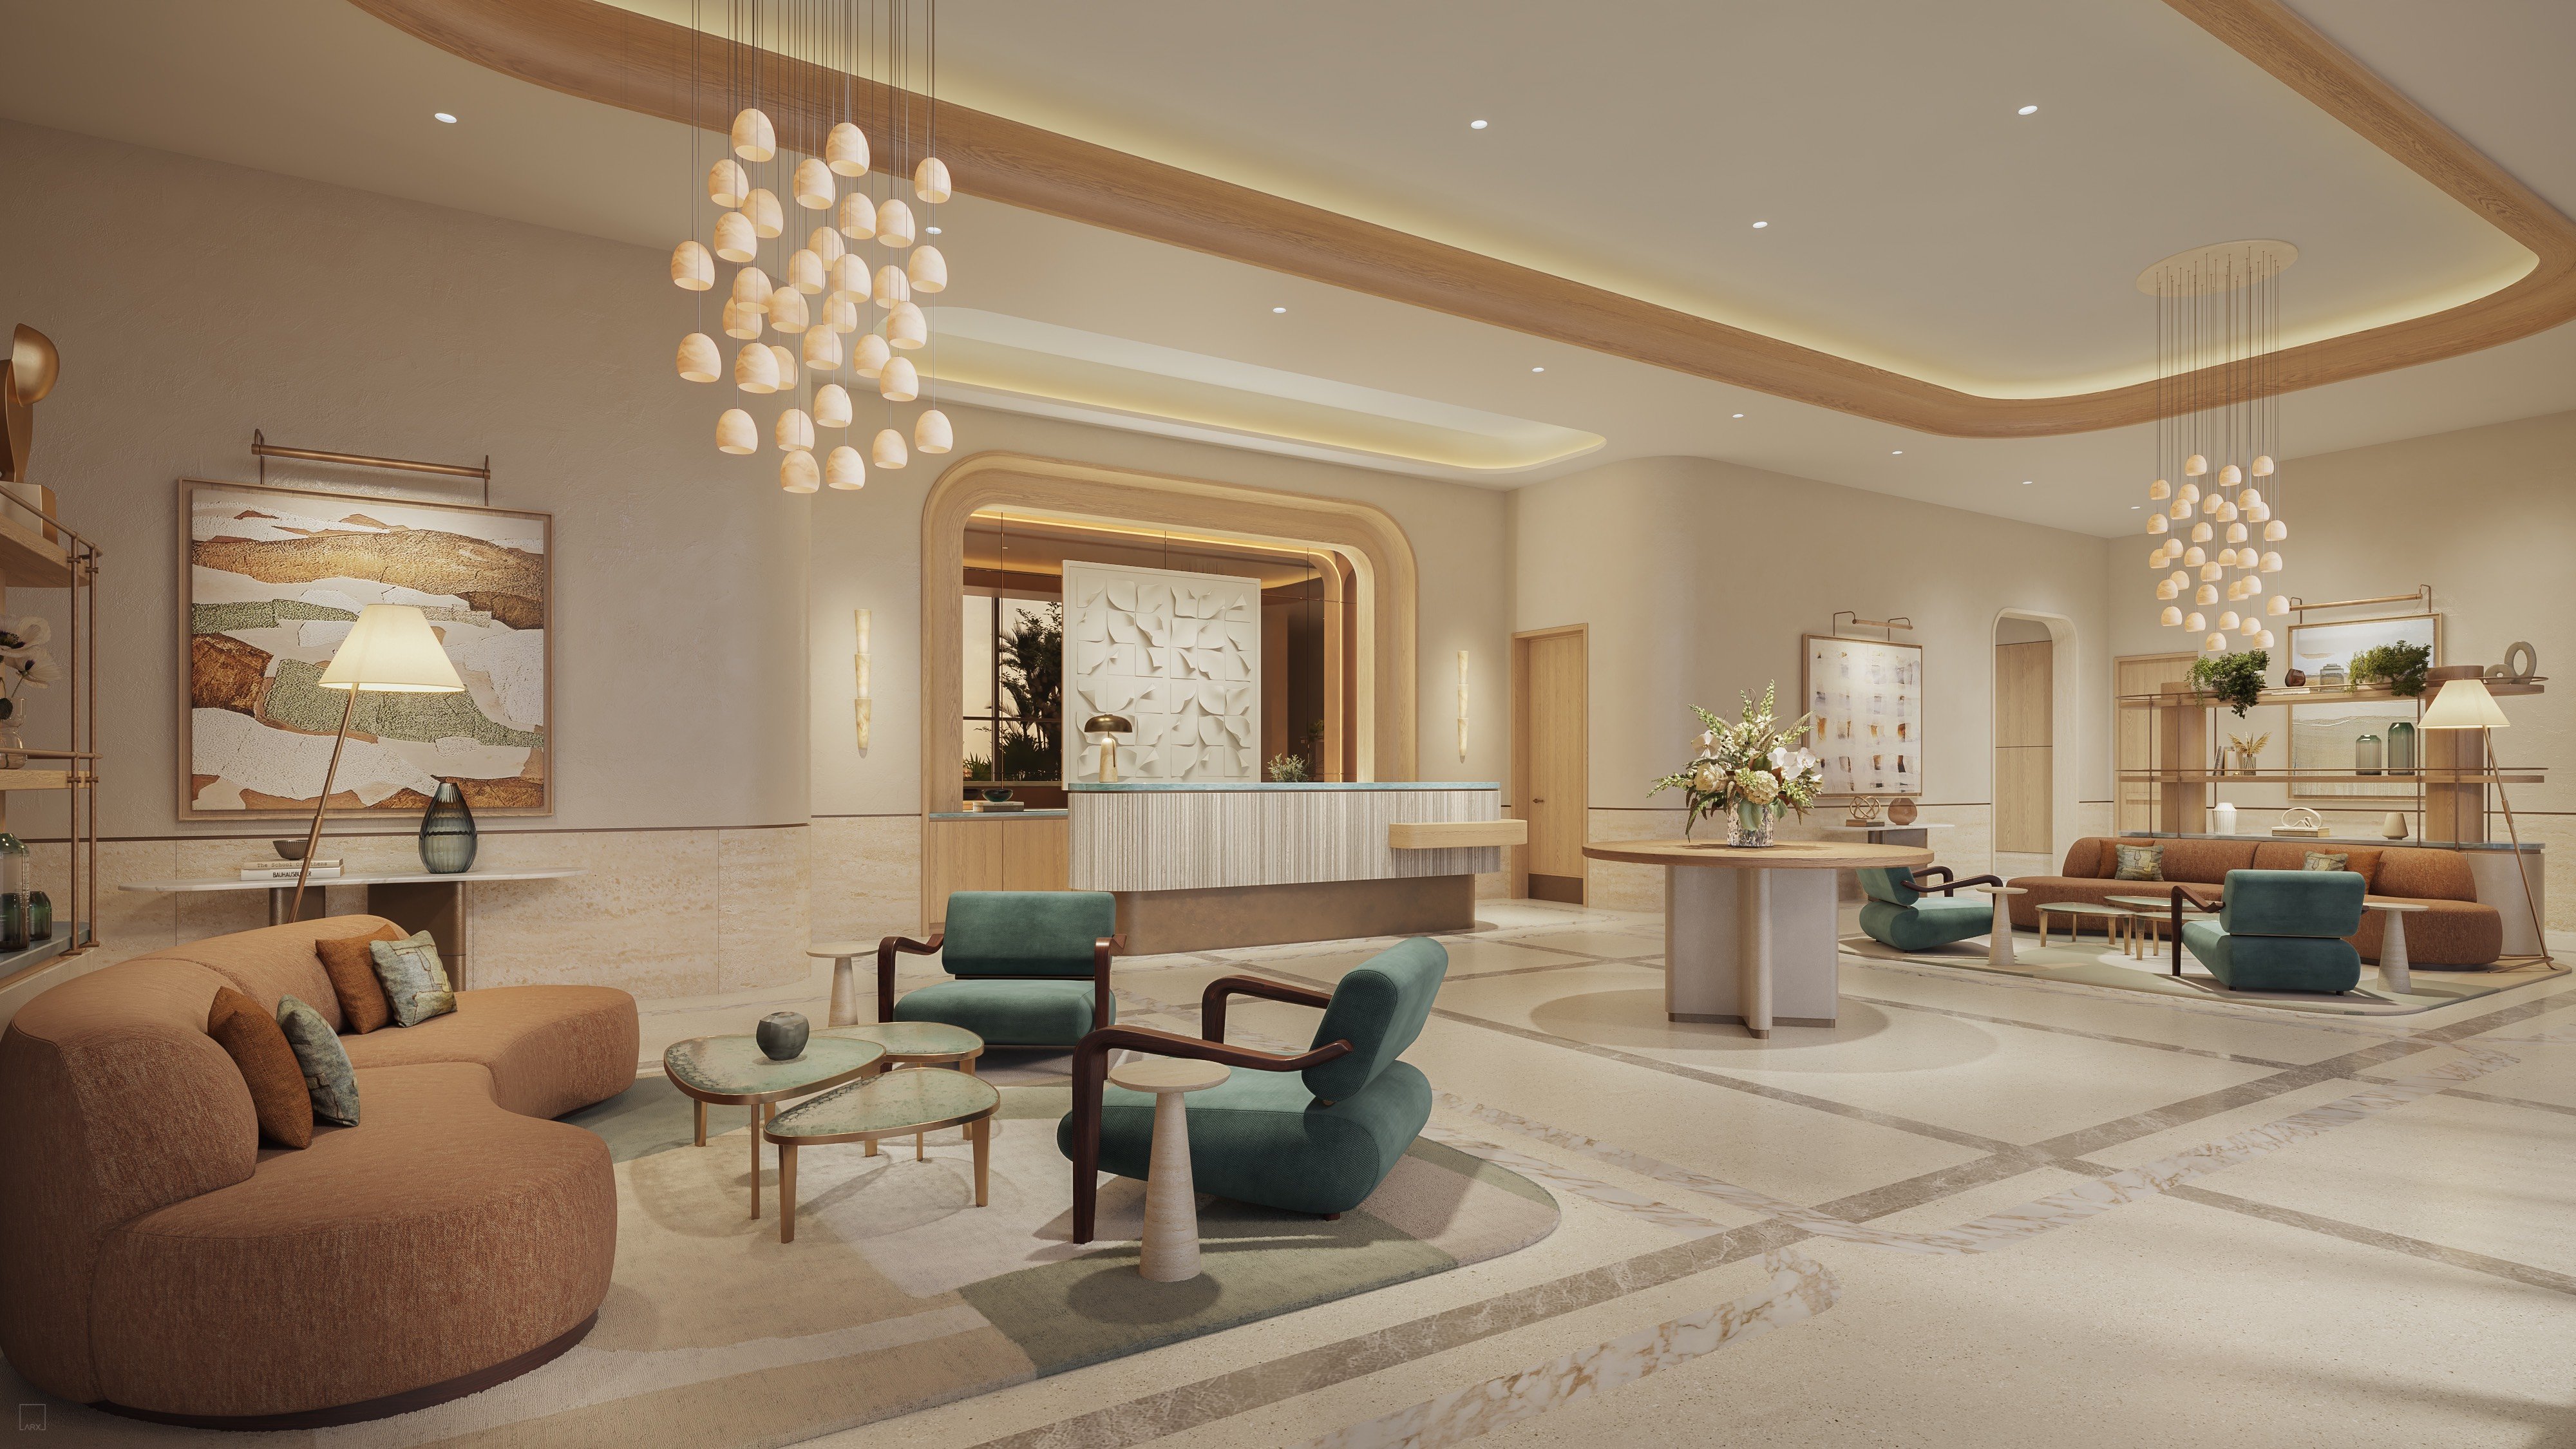
At St. Regis® Residences Bahia Mar Fort Lauderdale, the appeal is a residence conceived around hospitality, with advertised 24/7 concierge service and a setting that brings residential, resort, beach-club, and marina interests into the ownership equation. For a buyer considering 801 Seabreeze Boulevard, Fort Lauderdale, FL 33316, the financial question is not simply the size of the monthly assessment. It is what that assessment actually funds.
The essential qualification comes first: an initial HOA subsidy at Bahia Mar is not established. No subsidy amount, expiration date, or replacement assessment is confirmed. The concern is conditional. If temporary developer support funds part of association operations, an opening assessment could understate the cost owners would otherwise bear once that support ends.
A lower opening payment does not necessarily mean a lower long-term cost. Equally, a substantial advertised assessment is not proof that every service, shared obligation, or optional experience is included.
The community comprises Tower 1 condominium residences, Tower 2 condominium residences, and Resort Tower 3. Each tower's association will belong to a master association, adding a community-wide governance layer alongside the individual tower associations. Forming and operating that master association requires assessments.
For an owner, the task is reconciliation, not simple addition. Do not assume a quoted HOA figure excludes the master association, or add a second charge without establishing whether it is already incorporated. Request a unit-specific schedule showing the tower obligation, how master-association costs are treated, and the total payable by the owner.
The ownership offerings also warrant separate treatment. Private tower residences are distinguished from fully serviced St. Regis resort residences, with the resort component described as 79 fully serviced residences. That distinction does not establish identical assessment structures or service entitlements. Identify the exact offering attached to the contract before comparing dues across residences.
Two unit-specific advertised figures offer reference points, not a project-wide operating benchmark. Unit R 1501 has displayed monthly HOA dues of $4,096. Unit 1802 has displayed monthly HOA dues of $5,265. Those figures should remain tied to those units rather than serve as shorthand for the community's carrying costs.
The first figure does not establish what is included. The second does not establish that it reflects stabilized operations. Neither establishes a developer subsidy, a guaranteed future payment, or a forecast increase. Without matching budget periods, assessment allocations, and service inclusions, a comparison of the two amounts reveals little about relative value.
For underwriting purposes, stabilized cost should mean a budget for the intended ongoing level of service, with any temporary funding identified separately. Here, it is a planning concept, not a verified Bahia Mar assessment. The next step is to obtain the relevant budget and reconcile it to the exact residence under consideration.
If developer support exists, it could reduce the amount collected from owners without reducing the underlying expense of providing service. When that support ends, more of the expense could shift to owners, depending on the agreement and operating budget. This is the mechanism behind the title's concern, not a documented account of Bahia Mar's financing.
Temporary assistance is not inherently unfavorable. It may offer value to an early purchaser. The analytical mistake is treating it as a permanent reduction in ownership costs, or assuming that a launch-period payment fully reflects the ongoing service obligation.
Request any developer funding agreement and its termination terms. Establish which expenses it covers, how the contribution is calculated, whether it has a cap, and what ends the commitment. Then request a budget showing the same service scope without that contribution. If no such arrangement exists, evaluate the assessment on its actual inclusions and assumptions, not a presumed subsidy.
Bahia Mar's amenity terms make two important distinctions. Onsite beach-club use and access may require fees in addition to regular assessments. A marina slip lease requires separate payment beyond regular association assessments, and slip leases are offered on a first-come, first-served basis.
For a boating household, access and cost are separate diligence questions. A residence purchase should not be treated as a guaranteed slip allocation. Confirm availability, applicable lease terms, and the separate financial commitment before making the marina central to the purchase decision.
The beach club calls for similar precision: determine the access rights attached to the particular residence and which fees, if any, apply to the intended use. These terms show why the monthly association figure is not necessarily the household's complete lifestyle budget. They do not demonstrate subsidized dues or establish that assessments will rise.
The St. Regis name is used under license; Marriott International does not own, develop, or sell the project. Brand identity should therefore be considered alongside-not in place of-the documents defining service obligations and payment responsibilities. An advertised concierge offering does not, by itself, explain how every requested service is charged.
A buyer also considering Four Seasons Hotel & Private Residences Fort Lauderdale should compare service and assessment schedules for the specific residences, not simply their headline monthly figures. The meaningful comparison is what the owner receives and what remains theirs to pay.
The same discipline applies when extending a search to Rosewood Residences Hillsboro Beach. Neither branding nor geographic proximity establishes equivalent services, shared-cost allocations, or developer funding arrangements. Each ownership package requires its own documentary review.
Before committing, request a written reconciliation covering four points: the exact ownership category; tower and master-association obligations without double counting; included services and separately charged amenities; and any developer contribution with its termination conditions.
The reconciliation should identify the budget period and distinguish advertised assessments from projected ongoing costs. Have counsel review the governing and service documents while a financial adviser evaluates the payment assumptions. Where a future cost is not established, retain it as an unresolved underwriting question rather than substitute an unsupported estimate.
The strongest purchase decision does not depend on finding the lowest opening dues. It depends on understanding whether the residence's service model remains attractive at the cost the owner may ultimately bear. At Bahia Mar, the documented issues are layered governance, distinct ownership offerings, and potentially separate amenity payments. A subsidy remains a question to resolve, not a fact to assume.
For a discreet perspective on South Florida ownership options, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAn initial HOA subsidy is not established. Its amount, duration, termination conditions, and any replacement assessment are not confirmed.
If developer support covers operating expenses, owners could initially pay less than the underlying service cost. Ending that support could shift more expense to owners, depending on the agreement and budget.
The disclosed community includes two condominium towers and Resort Tower 3. Each tower's association will belong to a master association that also requires assessments.
Not without confirming how the advertised figure is calculated. Buyers should reconcile both obligations to avoid either omitting a charge or counting it twice.
Unit R 1501 has displayed $4,096 monthly, while unit 1802 has displayed $5,265 monthly. These unit-specific figures do not establish project-wide or guaranteed future assessments.
They are distinguished as separate offerings, with the resort component described as 79 fully serviced residences. Buyers should not assume identical assessment structures or service entitlements.
Onsite beach-club use and access may require additional fees. Buyers should confirm the rights and charges applicable to their particular residence.
Slip leases are offered on a first-come, first-served basis rather than guaranteed with every residence. Leasing a slip requires payment beyond regular association assessments.
Marriott International does not own, develop, or sell the project. The St. Regis name is used under license.
Request the applicable budgets, a unit-specific tower and master-association reconciliation, and a schedule of included and separately charged services. Also request any developer funding agreement and its termination terms.