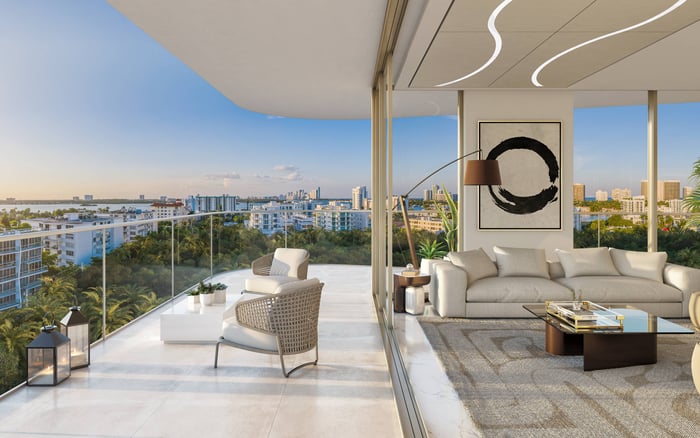
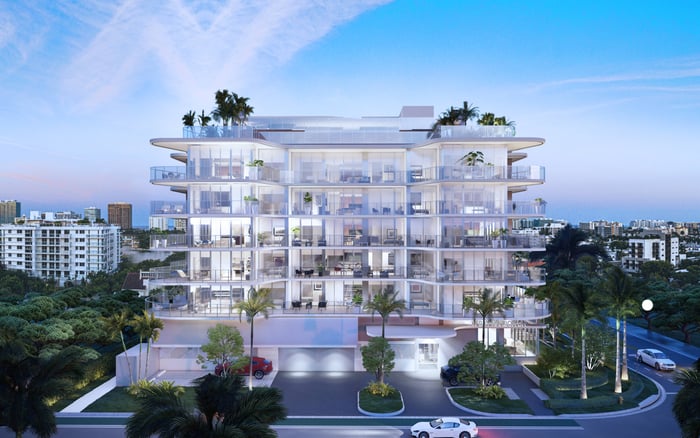
Mila’s nine-residence condominium model calls for a precise distinction between transaction disclosures and long-term ownership obligations. An estoppel certificate matters, but reserves, governing documents, insurance and available project records complete the financial picture.
For a luxury buyer, acquiring a residence and understanding its ownership obligations are distinct undertakings. At Mila Bay Harbor Islands, a nine-unit condominium project at 1125 97th Street, those obligations deserve the same attention as the home itself. An estoppel certificate is an important transaction document, but it does not replace a review of how future capital work may be identified, approved and funded.
Begin with the legal structure. Mila’s developer is 1125 97th Bay Harbor Condo 2618 LLC. That identification does not establish the entity as the unit-owner association. Buyers should distinguish the developer from the association and confirm, through the applicable documents, which entity holds each responsibility.
The questions below are due-diligence considerations, not statements that Mila has pending capital work, a special assessment, a reserve shortfall or an engineering defect. The purpose is informed ownership, not an assumption of problems.
Boutique ownership can be compelling, but nine residences do not automatically mean nine equal shares of every expense. Nor does a small residence count, by itself, establish that assessments will be higher. Mila’s actual allocation percentages must be established through its governing documents.
Ask counsel to identify the provisions governing common expenses, reserves and assessment allocations. The relevant question is not simply how many owners participate, but what percentage of a particular obligation belongs to the residence under consideration.
For buyers also considering Alana Bay Harbor Islands, the useful comparison is document-based: review each property’s allocations and financial framework rather than extrapolating from neighborhood or building scale. Residence count alone does not explain an ownership model; its documents do.
Florida law requires a condominium association to issue an estoppel certificate within 10 business days after a written or electronic request from an owner, mortgagee or their designee. The certificate identifies the owner and unit and provides prescribed assessment and outstanding-balance information.
Review the assessment disclosures carefully, but do not treat the certificate as a forecast of every future capital obligation.
The distinction is between a standardized transaction disclosure and the broader record of a building’s needs. A repair may be under discussion or identified through engineering work before it becomes a formally levied special assessment. The certificate cannot replace the documents needed to understand that earlier stage.
Timing also matters. An estoppel is effective for 30 days when hand-delivered or sent electronically, and 35 days when sent by regular mail. Coordinate the request and delivery with the closing schedule. That effective period is not an assurance that no future expenditure will arise.
A useful capital review connects three questions: what work has been identified, what decisions have been made and what funding is available. Available board minutes and engineering reports can reveal repairs or upgrades under discussion before an assessment is formally levied.
For each identified item, ask whether it is exploratory, recommended, approved or already underway. Request available scope descriptions, estimates and scheduling information. Distinguish preliminary discussion from an approved financial commitment. These are questions to resolve, not conditions to presume at Mila.
Next, compare reserve studies and reserve balances with budgets, actual spending and identified repair needs. Reserves are savings for future capital expenditures and major repairs, separate from operating funds. An operating budget alone therefore cannot establish whether future capital needs are adequately funded.
Engineering inspections may identify repairs whose costs exceed available reserves, potentially prompting special assessments. The buyer’s task is to understand the relationship between need and funding. Neither a reserve balance nor an inspection finding provides a complete conclusion on its own.
Apply the same discipline when evaluating Onda Bay Harbor: assess its obligations through its own available records. This is a comparison framework, not a suggestion that either property has a particular capital issue.
A pre-completion purchase calls for a different document request from a purchase in an operating condominium. Request available project documents and proposed association documents, along with available budgets, allocation schedules and information on future capital funding.
Do not assume that several years of operating accounts, board minutes or reserve history already exist. Where a document is prospective, read it as prospective. Ask which financial figures are proposed and which reflect actual balances or spending. Projections should not become assumptions about operating performance.
For an operating association, request available governing documents, budgets, financial records, reserve information, minutes and inspection materials. Ask advisers to determine which inspection requirements apply to the particular building. Coastal location alone does not establish identical milestone-inspection obligations and should not be used to imply that Mila has an inspection currently due.
The estoppel must provide contact information for insurance maintained by the association. That offers a point of contact, not an analysis of coverage, limits or deductibles.
Review the master-policy declarations separately, paying particular attention to wind and flood coverage, policy limits and deductibles that may affect owners’ financial exposure. Ask an insurance adviser to explain the relevant terms. An insurance contact on the certificate is not evidence of comprehensive protection.
Local administration is a separate consideration. Bay Harbor Islands requires condominium associations and other covered property entities to register annually with the Town’s code compliance unit on or before January 30. Ask for confirmation of applicable registration, but keep that administrative inquiry separate from the review of reserves, physical condition and insurance.
Investment discipline requires treating distinct questions separately. The estoppel addresses prescribed transaction disclosures. Governing documents establish how obligations are allocated. Capital records help explain potential work and funding, while insurance documents address another dimension of exposure.
Whether the broader search includes Bay Harbor Islands or Bal Harbour, comparisons should rest on the applicable documents for each residence. A polished presentation cannot answer an allocation question, and a certificate showing no outstanding balance cannot establish the absence of future capital needs.
Before committing, have the appropriate advisers reconcile the available records and identify unresolved questions in writing. The objective is not certainty about every future expense. It is a clear understanding of what is disclosed, what remains under consideration and how obligations would be allocated.
For a discreet perspective on South Florida luxury ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationMila is a nine-unit condominium project at 1125 97th Street, Bay Harbor Islands, Florida. Its governing documents should be reviewed to understand allocations and ownership obligations.
1125 97th Bay Harbor Condo 2618 LLC is identified as the developer, not as the unit-owner association. Buyers should establish the association’s identity and responsibilities through the applicable documents.
Nine residences do not establish equal one-ninth allocations. The actual percentages require review of the governing documents.
The association must issue it within 10 business days after a written or electronic request from an owner, mortgagee or their designee.
It is effective for 30 days when hand-delivered or sent electronically, and 35 days when sent by regular mail.
No. Its assessment and balance disclosures do not provide a comprehensive account of repairs or upgrades that may be under discussion before an assessment is levied.
Review available reserve studies, reserve balances, budgets, actual spending, board minutes and engineering reports. Compare identified work with available funding and the applicable allocation provisions.
No Mila-specific pending capital project, special assessment, reserve shortfall or engineering defect is established. The article presents due-diligence questions, not findings about existing problems.
Request available project and proposed association documents, including available budgets and allocation information. Do not assume that an operating history or several years of board minutes already exist.
It provides insurance contact information, not a full coverage analysis. Review master-policy declarations separately for wind and flood coverage, limits and deductibles.