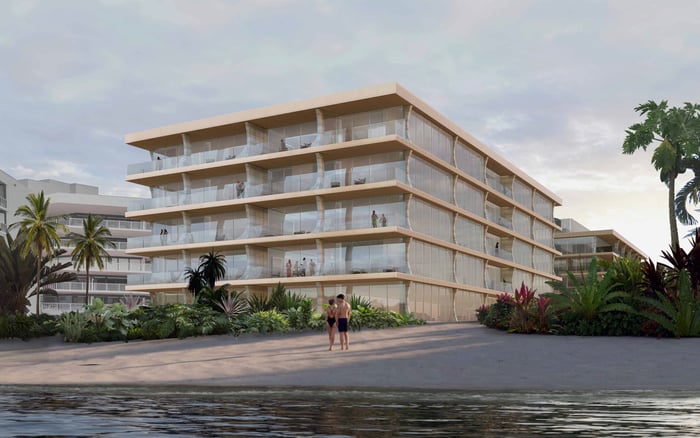
For a full-service condominium purchase on South Flagler Drive, financial clarity begins with the unit’s estoppel certificate. A disciplined review separates association balances from transaction charges, tests the authority for fees, and examines potential assessments beyond the closing statement.
The appeal of a full-service residence on South Flagler Drive is easy to appreciate. The financial obligations accompanying the purchase deserve equally close attention. Before closing, the buyer should understand not only the recurring assessment, but also the association balance attached to the unit, the charges triggered by the transaction, and any unresolved assessment questions.
For buyers considering Forté on Flagler West Palm Beach, that discipline begins with a distinction: an estoppel certificate addresses specified association obligations, not the entire financial outlook of ownership. It belongs alongside the purchase contract, budget, board notices, and relevant meeting records-not in place of them.
The objective is a closing file in which every charge has a clear description, a supported amount, and an agreed allocation. Elegance in the residence should be matched by precision in the paperwork.
A Florida condominium estoppel certificate identifies assessments and other amounts owed to the association on a particular unit. Review it for regular assessments, special assessments, unpaid balances, and sale- or transfer-related charges relevant to closing.
First, confirm that the certificate identifies the correct unit. Then separate recurring obligations from delinquent amounts and transaction charges. A single total may be convenient, but it does not explain what created the balance or how each component should be handled under the purchase contract.
Unpaid assessments and other delinquent amounts warrant particular attention because they affect the association balance that must be addressed at closing. Ask the closing team to reconcile those figures with the association’s account detail and the proposed closing statement. Resolve discrepancies through specific questions rather than carrying assumptions into signing.
This review concerns a condominium obligation. Florida’s separate homeowners’ association estoppel provision should not be treated as interchangeable with the condominium provision applicable to the tower.
The estoppel certificate must disclose whether a capital contribution, resale fee, transfer fee, or other fee is due. When a sale- or transfer-related fee is payable, the certificate must identify its type and amount.
Each charge therefore needs a precise description. A capital contribution should not disappear into a generic transfer-cost line, nor should a certificate preparation charge be mistaken for an association transfer fee. Even when several amounts appear together on a closing statement, the buyer’s review should keep them distinct.
The same approach applies when evaluating Mr. C Residences West Palm Beach as part of a broader search: request the documents applicable to the contemplated transaction rather than carrying over a fee assumption from another property.
For each disclosed charge, ask what triggers it, how the amount is established, and which contractual provision determines the buyer-seller allocation. A familiar label is no substitute for a documented answer.
The requirement to disclose a fee on an estoppel certificate does not, by itself, establish that every association may legally impose it. Seeing a charge on paper is not the same as confirming the authority behind it.
Where a capital contribution, resale fee, or transfer charge appears, ask counsel to review the applicable legal requirements and governing documents. The question is not merely whether the arithmetic is correct, but whether the charge has an appropriate basis for this association and this transaction.
Do not treat another tower’s contribution schedule as a benchmark that settles the issue. The useful comparison is procedural: does each purchase file explain the fee, identify the amount, and support its imposition? This allows a buyer to compare transactions without assuming their association obligations are identical.
The fee for preparing and delivering the estoppel certificate is legally distinct from an association’s transfer fee. It pays for a different function and should be reviewed on a separate line.
Preparation-and-delivery charges are subject to statutory limits and adjustments. Base statutory figures should not automatically be read as the applicable adjusted maximums. Before approving the charge, ask the closing team to confirm the fee schedule in effect when the certificate is requested.
Expedited delivery within three business days can involve an additional charge. A delinquent unit account also permits an additional estoppel charge. Neither should be confused with the underlying delinquency: money owed on the unit and money charged to prepare the certificate are separate components of the transaction.
Request an itemized explanation showing the standard preparation charge and any additional amounts. This keeps an administrative expense from obscuring the larger association obligations being settled.
An estoppel certificate is not a complete forecast of future assessments. Amounts disclosed as due answer a different question from whether the association is considering spending that could lead to another owner obligation.
Review the budget, board notices, and relevant meeting records separately. Ask the association to clarify any assessment references: is the discussion preliminary, has an assessment been adopted, and what payment information is available? These questions distinguish an existing obligation from a potential future one without assuming either is present.
For a buyer also considering Shorecrest Flagler Drive West Palm Beach, the comparison should follow the same documentary discipline. Project selection and association review are complementary exercises; a residence’s appeal does not answer the financial questions attached to its purchase.
Where records raise an unresolved assessment issue, have counsel address its treatment under the contract. The absence of an amount in the current balance is not assurance that ownership costs cannot change.
The final review should bring the documents together, not simply confirm that each has arrived. A useful working schedule gives every association charge its own entry, with the amount, supporting document, payment timing, and proposed buyer-seller allocation.
Keep four categories distinct: regular assessments, special assessments, delinquent balances, and transaction-related charges. Within the last category, separate certificate preparation costs from any capital contribution, resale fee, or transfer fee. Record unresolved questions separately rather than folding them into an unexplained estimate.
Then compare the schedule with the purchase contract and closing statement. The certificate helps establish the association amounts to address; the contract must be examined to determine how those costs are allocated between the parties. Neither document should be expected to do the other’s work.
The strongest due-diligence file gives the buyer a clear account of the purchase: what is payable, why it is payable, who bears it, and what still requires attention beyond closing.
For a considered approach to South Flagler Drive and West Palm Beach residential opportunities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIt identifies assessments and other amounts owed to the association on a particular unit, including relevant sale- or transfer-related charges.
Review regular assessments, special assessments, and unpaid or delinquent amounts. Reconcile those figures with the association account detail and proposed closing statement.
The condominium statute requires disclosure of whether a capital contribution is due. A sale- or transfer-related fee must be identified by type and amount.
No. The disclosure requirement does not itself establish authority to impose every fee; counsel should review the applicable law and governing documents.
No. Preparing and delivering the certificate is legally distinct from an association transfer fee, so the charges should be reviewed separately.
No. Confirm the applicable adjusted fee schedule rather than assuming the statute’s base figures are the amounts that apply to the request.
Yes. Expedited delivery within three business days can involve an additional charge, separate from standard preparation and delivery.
No. Review the budget, board notices, and relevant meeting records separately to investigate potential assessment exposure beyond amounts disclosed as due.
Reconcile the disclosed charges with the purchase contract to determine the buyer–seller allocation. Confirm that the closing statement reflects that treatment.
No. Florida has a separate homeowners’ association estoppel provision; a condominium tower should be reviewed under the applicable condominium provision.