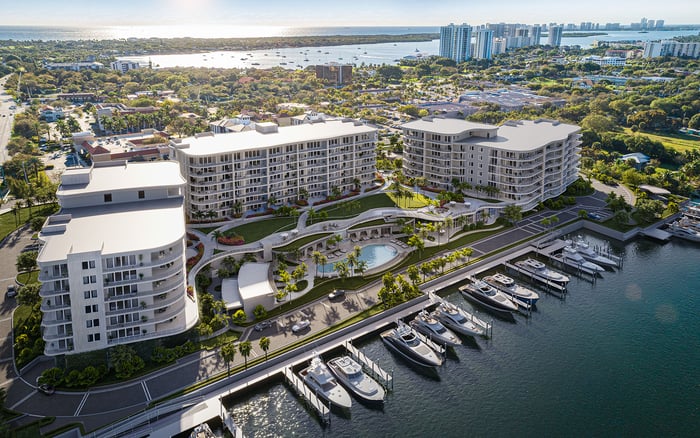
A discreet closing begins with precise identification. For South Flagler Drive buyers, that means reconciling the unit’s public records, documenting entity or trust signing authority, and verifying any claimed FinCEN reporting pause rather than treating it as a blanket exemption.
A lock-and-leave residence on South Flagler Drive promises freedom from daily oversight. The closing file should support that freedom with equally disciplined paperwork. For a West Palm Beach buyer, four questions matter: which property is being conveyed, who holds title, who may sign, and which reporting obligations apply on the closing date?
Keep those questions separate. A tax-mail address does not establish signing authority. An LLC name does not reveal every beneficial owner. A development’s financing does not establish clear title to an individual residence. The objective is a coherent file, not merely a collection of search results.
Begin with the exact street address and unit number. Building names are useful for a shortlist; parcel identifiers and legal descriptions are stronger anchors for a closing review.
Begin the Palm Beach County property-record review with the exact unit address. Identify the parcel control number, commonly called the PCN, and use it as a consistent reference for subsequent ownership and assessment checks.
Ask the closing team to reconcile the owner of record, tax mailing address, sale history, assessment information, and PCN shown in the available property records. Preserve a dated copy to compare with the contract and recorded documents. Treat the property summary as an index to the review, not its conclusion.
For a buyer considering Forté on Flagler West Palm Beach, the discipline is the same: have counsel reconcile the contracted residence with the applicable legal description and public-record identifiers. Do not assume a marketing designation sufficiently identifies the interest being purchased.
Ownership and assessment summaries serve a different purpose from recorded deeds and mortgages. Review both.
Compare the deed’s grantor, grantee, and legal description with the proposed seller and the residence identified in the purchase contract. If the names differ, ask counsel to explain and document the connection. A verbal assurance that the parties are related is not enough.
Extend the review to recorded mortgages, liens, association liens, and judgments potentially affecting the unit. Ask the closing team to identify matters requiring resolution and the evidence it expects before funds are released.
An LLC named in a tax-mail block provides a lead for further review, not a conclusion about the entity’s owners or authorized signer. Follow the record into the underlying documents before assigning that entity a role in the transaction.
For a residence marketed as South Flagler House West Palm Beach, confirm that every search result matches the contracted property rather than relying on a similar building or entity name.
The distinction matters when nearby properties have overlapping names. A single LLC-associated unit record establishes neither whole-building ownership nor association control. It also provides no basis for inferring the ownership mix at another development.
Keep development milestones in a separate category. Neither a construction milestone nor a projected delivery date substitutes for transaction-specific title review.
Use five distinct headings in the ownership file: recorded titleholder, tax-mail recipient, registered agent, authorized signer, and beneficial owner. A name under one heading is not proof of another role.
For an entity seller or purchaser, ask counsel to obtain and reconcile the relevant entity filings, exact legal name, jurisdiction, and status documentation. Ask which governing documents or transaction-specific approvals are needed to establish the proposed signer’s authority. These are verification requests, not a presumption that every transaction requires the same document package.
An entity filing is not the entire authority review. Have counsel connect the entity in the records to the party in the contract and the person executing the closing documents.
The same questions belong in a purchase file for Mr. C Residences West Palm Beach. Project selection and entity verification are separate decisions; neither should stand in for the other.
When a trust is involved, ask counsel to reconcile the proposed vesting language with the documents supporting the trustee’s authority. Identify who will sign, in what capacity, and what evidence the closing team will accept for this transaction.
Request a focused review of relevant trust provisions, amendments, and any succession or approval questions counsel considers applicable. Do not assume a beneficiary is the authorized signer, or that a familiar trust name proves authority to buy or convey the residence.
Keep the buyer’s brief practical: establish authority while sharing sensitive documents only through arrangements approved by counsel. The public property summary is a starting point, not a substitute for that private-document review.
Do not treat a description of a paused FinCEN reporting regime as confirmation that no filing is required for a South Flagler Drive closing. Any claimed pause needs a date-specific review of its existence, scope, and applicability to the transaction; this article does not establish its current legal status.
Ask closing counsel to confirm the then-current residential real-estate reporting requirements, whether the transaction falls within them, and who would handle any applicable filing. If a pause is relevant, request confirmation of what it covers and whether that remains true when the transaction closes. Do not assume it eliminates filing obligations or potential liability beyond its actual terms.
Separately, request an assessment of the purchasing entity’s position under the Corporate Transparency Act’s beneficial ownership information framework. Do not recycle historical BOI deadlines or assume every domestic purchasing LLC must file. A residential transaction-reporting pause does not, by itself, determine an entity’s CTA status.
Whether the shortlist includes Shorecrest Flagler Drive West Palm Beach or another residence, request a concise pre-closing reconciliation: property identity, recorded title, matters requiring resolution, signing authority, and date-specific reporting advice.
The final question is not whether every search returned a name. It is whether the documents support the same residence, the same contracting parties, and an authorized closing. That is the quieter foundation of lock-and-leave ownership.
Explore South Florida residences with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationUse the exact unit address, PCN, and recorded legal description. Reconcile them with the purchase contract rather than relying on the building name alone.
Review the available owner-of-record, tax-mail, sale-history, assessment, and parcel-control information. Preserve a dated copy for comparison with the contract and recorded documents.
The property summary does not replace review of recorded deeds and mortgages. Ask counsel to check potentially relevant liens and judgments as well.
No; a tax-mail entry does not establish signing authority. Ask counsel to distinguish the recorded titleholder, tax-mail recipient, registered agent, authorized signer, and beneficial owner.
Ask counsel to reconcile the entity’s exact identity, relevant filings, status documentation, and evidence supporting the proposed signer’s authority for the transaction.
Ask counsel to reconcile the vesting language and signer’s capacity with the relevant trust documents. Confirm what authority evidence the closing team will accept.
Match each search result to the contracted unit’s address, parcel identifier, and legal description. A similar building or entity name is not sufficient.
No; a single unit record does not establish whole-building ownership, association control, or another development’s ownership mix.
Ask closing counsel to verify the pause’s existence, scope, and applicability on the closing date. Do not assume a pause eliminates all filing obligations or potential liability.
No; residential transaction reporting and CTA beneficial ownership information obligations are separate questions. Request a separate, date-specific assessment of each.