Coral Gables has a nominal property-tax advantage at equal taxable values in the comparison examined here. Coconut Grove offers the same Florida homestead framework. For buyers in either market, residency, portability and ownership history deserve as much attention as millage.
For a buyer weighing Coconut Grove against Coral Gables, property taxes belong alongside architecture, privacy and the intended rhythm of ownership. Neither address unlocks a special Florida homestead regime. Both operate within the same primary-residence framework. The more useful questions concern jurisdiction, taxable value, residency timing and how long the property will remain a permanent home.
Coral Gables has a lower nominal property-tax burden at identical taxable values in the rate comparison used here. Coconut Grove, which uses City of Miami rates, offers no separate neighborhood tax advantage. Yet the rate difference alone cannot determine an individual buyer’s tax bill, much less total annual ownership costs.
The strongest comparison begins with the owner’s circumstances, not the asking price. A relocating household, an existing Florida homestead owner and a seasonal buyer should approach the same residence with different tax assumptions.
Property-tax millage expresses dollars of tax for every $1,000 of taxable value. Total millage extends beyond the municipal levy to include county, school and special-district components. Comparing only the city portion can therefore understate the annual obligation.
For historical context, Coral Gables’ FY2024 total was 18.2022 mills, comprising 5.2823 county mills, 6.602 school mills, 5.559 municipal mills and 0.7589 special-district mills. Its 2025 proposed municipal rate was 5.5590 mills, unchanged from the comparison rate. That continuity does not establish an unchanged total bill.
A separate paired comparison places Coconut Grove at 19.9878 total mills and Coral Gables at 18.1852. The Coconut Grove figure includes 7.1080 municipal operating mills and 0.2536 debt mills. These figures are illustrative, not verified current-year quotations. The historical and proposed figures should not be blended into a single current schedule.
For a buyer considering Ponce Park Coral Gables, the next step is a residence-specific tax estimate using the applicable year’s rates and the buyer’s anticipated taxable values-not a citywide percentage treated as a quotation.
The paired totals of 19.9878 and 18.1852 mills produce a difference of 1.8026 mills, or approximately $1,803 annually for every $1 million of identical taxable value.
On a uniform $5 million taxable base, the calculation produces approximately $99,939 in Coconut Grove and $90,926 in Coral Gables-a $9,013 annual difference. At a uniform $10 million taxable base, the figures are $199,878 and $181,852, respectively, a difference of $18,026. Both illustrations exclude non-ad-valorem charges.
The word “taxable” is essential. Two homes purchased for $5 million do not necessarily have identical taxable bases. Exemptions and assessment benefits affect the calculation, and different taxing authorities may apply exemptions differently. These examples isolate millage; they do not forecast the bills for two equally priced listings.
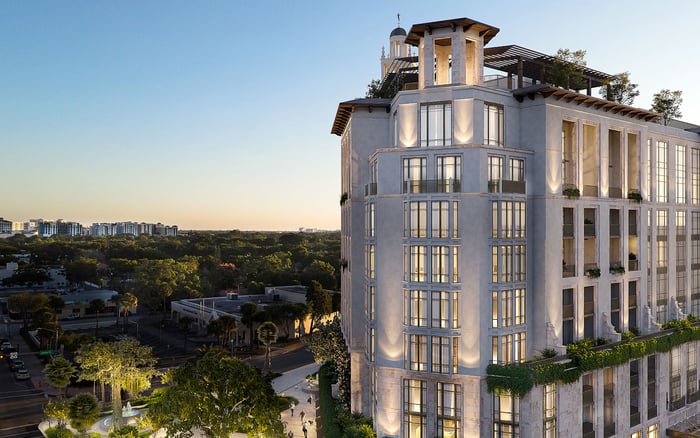
For a household comparing Four Seasons Residences Coconut Grove with a Coral Gables alternative, this exercise puts the tax-rate difference in perspective without assigning either property an unsupported tax bill.
Eligible owners in both markets can receive Florida homestead benefits when the property is their permanent primary residence and they satisfy the eligibility requirements. Buyers generally must establish permanent residence by January 1 and apply by March 1 of the applicable tax year. The purchase and residency decisions should therefore be coordinated, not treated as interchangeable.
The exemption structure also requires care. The first $25,000 applies to all property taxes, including school taxes. The additional exemption applies only to non-school taxes. A single deduction applied across total millage will not accurately capture that distinction.
For buyers considering Arbor Coconut Grove as a permanent home, the relevant questions are personal: when permanent residence will be established, whether eligibility requirements will be met and which exemptions belong in the estimate. The neighborhood name does not establish entitlement.
Baseline planning should use established benefits rather than proposed expansions. Before committing to a tax assumption, confirm eligibility and filing requirements with the appropriate property-appraiser office or a qualified adviser.
Save Our Homes generally limits annual increases in a homesteaded property’s assessed value to the lesser of 3% or CPI. It protects the assessment, not the final tax bill. Changes in rates and other bill components can still affect the amount payable.
Over a long holding period, appreciation above that assessment limit can widen the gap between assessed and market value. Ownership history therefore matters alongside the municipal rate. A low bill associated with an established homestead should not become the buyer’s budget without a separate assessment of that buyer’s position.
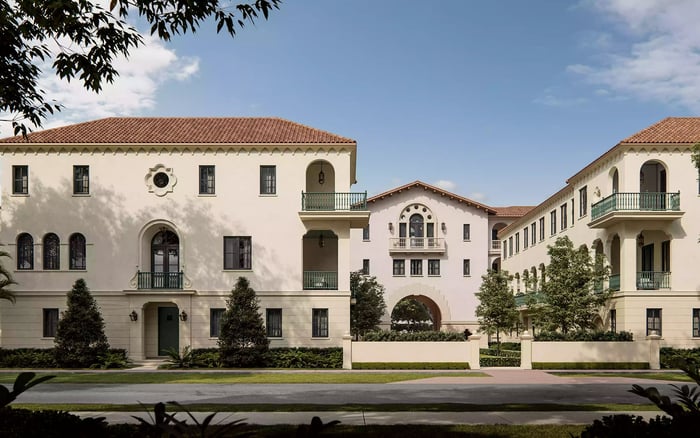
Eligible owners moving between Florida primary residences may also transfer some accumulated Save Our Homes assessment benefit through portability. For an existing Florida owner evaluating The Village at Coral Gables, a review of potential portability belongs alongside the millage comparison. Its usefulness depends on eligibility and the benefit available, not simply the destination.
For a permanent-residence buyer expecting a long hold, both markets provide access to the same homestead structure. Coral Gables’ lower nominal millage in the paired illustration offers a starting advantage, while eligibility, portability and future assessment growth shape the individual result.
For a buyer who prefers Coconut Grove, the disciplined approach is to quantify the illustrative tax premium, then decide whether the preferred residence justifies it. There is no need to recast the Grove as tax-favored to make that choice rational.
A seasonal property that does not qualify as the owner’s permanent Florida residence does not receive the primary-residence homestead exemption or Save Our Homes protection. That does not mean its assessment is necessarily uncapped; other assessment limitations require separate consideration. Seasonal buyers should not borrow primary-residence assumptions for their budgets.
The supported distinction concerns property taxes, not overall carrying costs. Insurance, maintenance, association fees and other ownership expenses require separate property-level budgets. A nominal tax advantage does not establish which residence is less expensive to own overall.
Before choosing, align the intended use, residency calendar, anticipated taxable values, potential portability and applicable rates. Coral Gables may lead on nominal tax carry at equal taxable values; either market may fit the buyer’s wider priorities. The objective is to choose a residence with clear expectations-not to mistake a tax bill for a complete ownership strategy.
Explore residences aligned with your priorities through MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationBoth use the same Florida homestead framework. Eligibility depends on permanent primary residence and other requirements, not the neighborhood name.
The paired illustration places Coral Gables at 18.1852 total mills and Coconut Grove at 19.9878. These are illustrative figures, not verified current-year quotations.
Coconut Grove uses City of Miami rates rather than a separate neighborhood rate.
The paired rates produce approximately $99,939 in Coconut Grove and $90,926 in Coral Gables, a $9,013 annual difference. The illustration assumes identical taxable bases and excludes non-ad-valorem charges.
No. Millage applies to taxable value, which is not necessarily the purchase price, and exemptions can differ among taxing authorities.
Buyers generally must establish permanent residence by January 1 and apply for homestead by March 1 of the applicable tax year.
The first $25,000 applies to all property taxes, including school taxes. The additional exemption applies only to non-school taxes.
No. It generally limits annual growth in a homesteaded property’s assessed value to the lesser of 3% or CPI, rather than fixing the bill.
Eligible owners moving between Florida primary residences may transfer some accumulated Save Our Homes assessment benefit through portability.
A property that does not qualify as the owner’s permanent Florida residence does not receive the primary-residence homestead exemption or Save Our Homes protection. Other assessment limitations may still apply.