A Houston-to-Fisher Island move calls for more than a new address. Family offices should separate Florida domicile from other states’ residency tests, maintain person-specific travel records, and align official documents with the family’s actual home life.
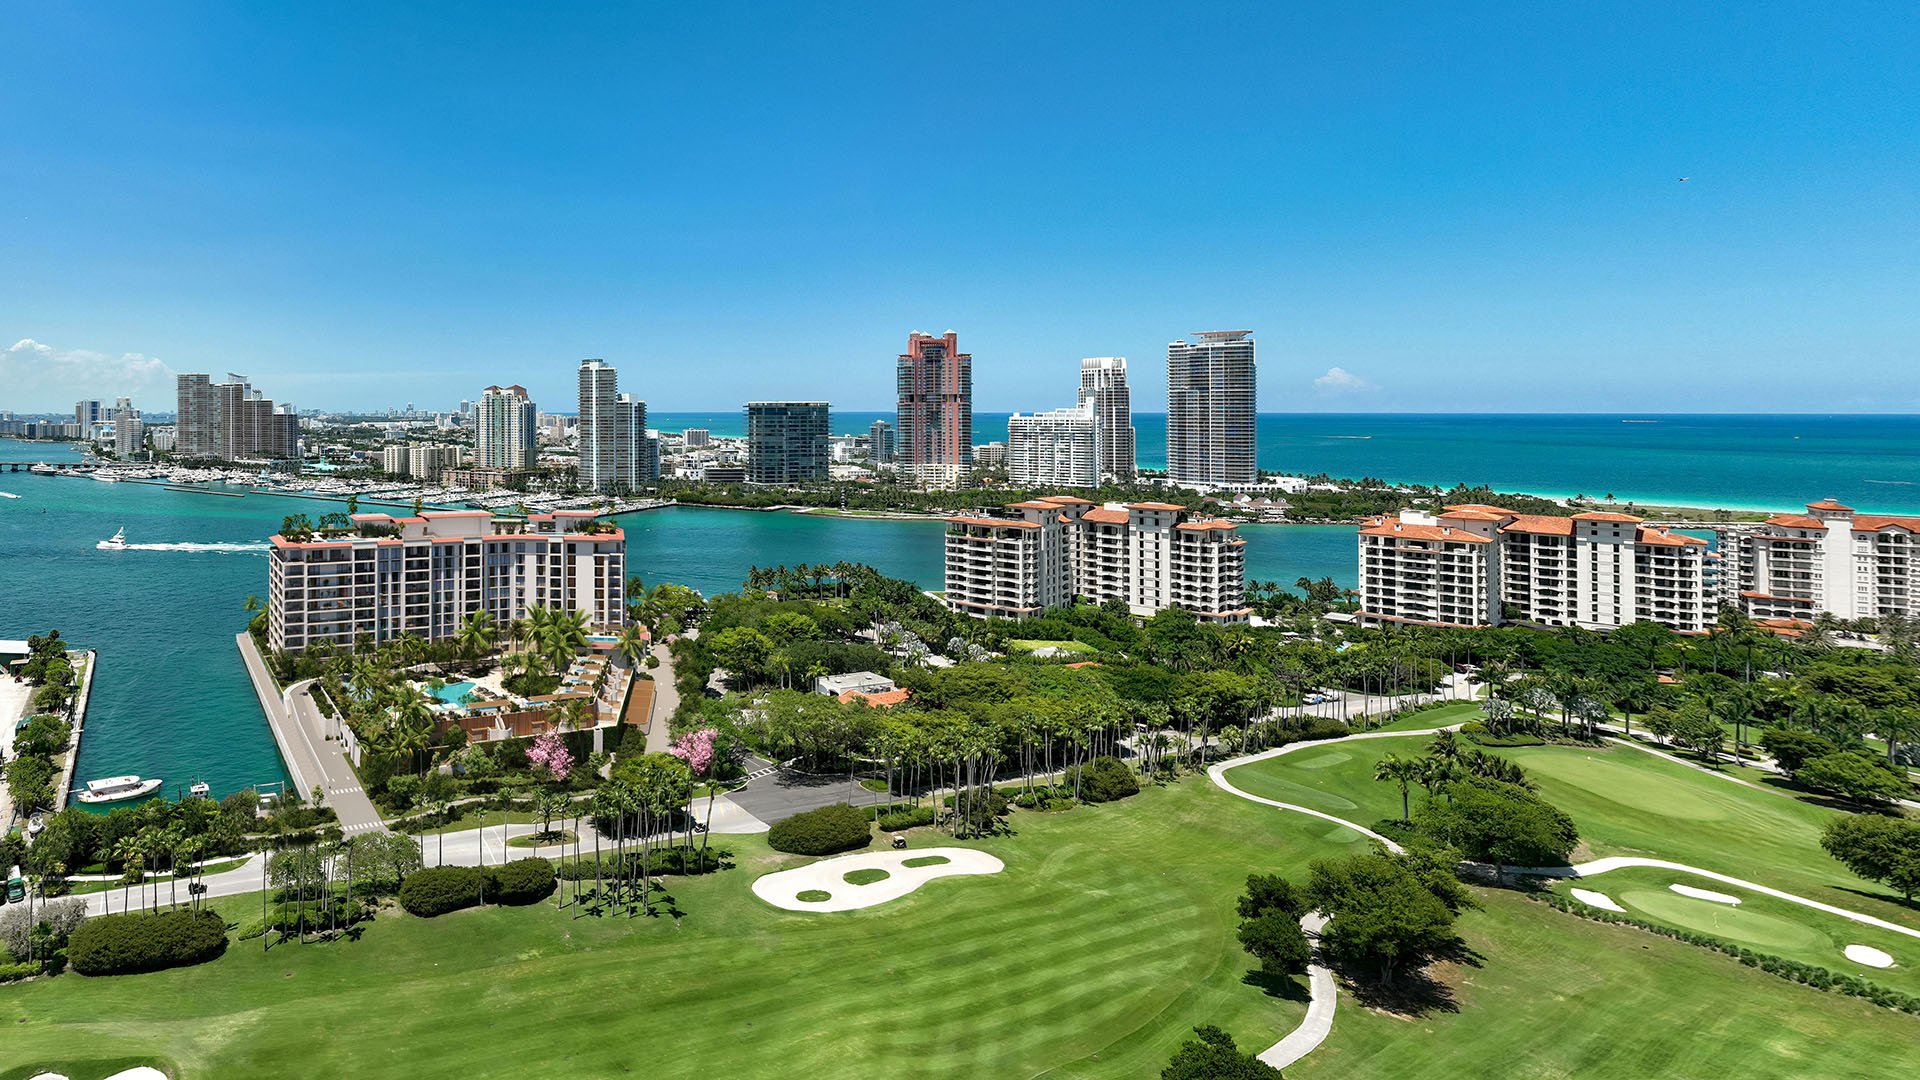
For a Houston family considering Fisher Island, the residence search and domicile plan should advance together. The central question is not simply which property to acquire, but whether Florida will become the family’s true, fixed, permanent home. A compelling address cannot answer that question alone.
Texas and Florida impose no individual state income tax, so this is not a conventional departure from a state personal-income-tax regime. The more consequential planning issues are consistent domicile evidence and potential tax residency in other states where family members maintain homes or spend time.
When evaluating Palazzo del Sol Fisher Island, the family office should distinguish the acquisition decision from the residence’s intended use. Will it become the household’s permanent home or remain a seasonal retreat? That distinction should guide both the purchase brief and the records that follow.
Florida domicile has no 183-day minimum. Establishing it depends on making Florida the permanent home, not reaching a calendar target. Physical presence nevertheless remains meaningful evidence: an address used mainly for correspondence tells a different story from a home around which daily life is organized.
Statutory tax residency is a separate inquiry. Another state may treat a Florida domiciliary as a resident under its own rules. Some states combine a qualifying permanent place of abode with a day-count threshold, potentially bringing worldwide income within their resident taxation rules.
New York’s relevant threshold is more than 183 days, together with its permanent-place-of-abode requirements. It is not a direction to spend 184 days in Florida. Nor should New York’s framework be applied automatically to California, New Jersey, or any other jurisdiction.
The family office should ask advisers two distinct questions: has domicile genuinely moved, and could another state independently establish tax residency? Staying below a statutory threshold does not, by itself, demonstrate abandonment of an old domicile.
A shared itinerary helps with logistics but is insufficient as the sole residency record. Spouses and other family members may travel separately for business, school, healthcare, or personal commitments. A recommended control is a daily location calendar for each person whose residency position requires review.
Record actual travel rather than relying exclusively on planned departures or overnight locations. Partial days can count as full days under state residency rules. A calendar that records only where someone slept may therefore understate presence elsewhere.
Do not automatically treat every airport connection as a counted day. Transit treatment and other exceptions require jurisdiction-specific confirmation. Preserve arrival and departure details so advisers can apply the relevant rules without guessing from a destination summary.
Travel planning should allow for unexpected changes. The family office can ask counsel to recommend a margin below relevant thresholds, then compare planned visits with actual accumulated days. That margin is a planning choice, not a universal legal safe harbor.
Daily logs are more useful when supported by contemporaneous records. Retain travel confirmations, flight records, and relevant transaction records in a form that lets the office reconcile actual movements without reconstructing a year from memory.
Auditors may compare a calendar with third-party evidence, including credit-card activity and phone-location data. The practical objective is consistency: resolve discrepancies while the circumstances remain clear. A reservation shows a plan; supporting evidence helps establish what actually happened.
As a recommended operating routine, designate one coordinator to reconcile calendars regularly, flag unexplained entries, and direct jurisdiction-specific questions to counsel. Keep planned and actual travel distinct rather than overwriting one with the other.
For a household considering Palazzo della Luna Fisher Island as its permanent home, this recordkeeping should reflect genuine use of the residence. The calendar is evidence of the family’s life, not a substitute for living it.
The residency review should extend beyond properties on an ownership schedule. A qualifying abode need not be owned. Depending on the jurisdiction, a long-term rental or continuously available apartment can create exposure when combined with the applicable presence rules.
Ask advisers to review retained homes, leased residences, and other potentially available accommodations. Document availability and use, then assess both alongside each person’s calendar. Ownership, access, and physical presence are not interchangeable concepts.
For a buyer weighing The Links Estates at Fisher Island, the wider residential portfolio belongs in the planning conversation. A Florida purchase does not resolve the treatment of an apartment maintained elsewhere. The appropriate response is a property-by-property review, not an assumption that the newest acquisition overrides every other connection.
A Declaration of Domicile under Florida Statutes §222.17 can be recorded in the county of the Florida residence to document the claimed permanent home. It is one element of the record, not a replacement for the underlying facts.
Florida driver-license, vehicle-registration, and voter-registration records help substantiate the move when they consistently reflect the Florida home. Banking, brokerage, legal, and healthcare records should also align when that address genuinely represents the family’s permanent residence.
The office should distinguish legitimate mailing arrangements from residential-address fields and ask advisers to resolve inconsistencies. Administrative neatness should follow an actual move, not manufacture the appearance of one.
A Florida homestead exemption, when eligible, can support the claim that the property is a permanent residence rather than a vacation home. Eligibility should be reviewed separately, not assumed from a purchase. The same discipline applies when considering The Residences at Six Fisher Island: the residence decision and domicile evidence must remain connected to actual use.
Family location, schools, personal belongings, healthcare relationships, and social ties help show where personal life is centered. These details deserve attention because they can reinforce-or contradict-the official address record.
Before treating the transition as complete, the family office should compare three things: where each person actually spends time, which homes remain available elsewhere, and what official and financial records say. Any mismatch merits explanation and, where appropriate, professional review.
The strongest plan is not the thickest file. It is a coherent account of a genuine move, maintained as travel patterns and family circumstances evolve. This is a planning framework, not individualized legal or tax advice; state-specific conclusions belong with qualified counsel.
For a discreet conversation about selecting a South Florida residence around your family’s long-term plans, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Florida domicile depends on making Florida your true, fixed, permanent home, although physical presence remains relevant evidence.
Texas and Florida both impose no individual state income tax. The move is not an exit from a state personal-income-tax regime.
Yes. Another state can apply its own residency rules, including applicable permanent-place-of-abode and day-count tests.
It is a New York presence threshold considered together with its permanent-place-of-abode requirements. It does not require spending 184 days in Florida.
Yes. Depending on the jurisdiction, a long-term rental or continuously available apartment can qualify as an abode relevant to residency analysis.
No. Partial days can count as full days, so records should capture actual movements rather than just overnight locations.
Not automatically. Transit treatment and other exceptions require confirmation under the particular state’s rules.
Travel and transaction records should support the log. Flight records, credit-card activity, and phone-location data may be compared with calendars during a residency review.
No. It documents the claimed permanent home, but actual home use, family ties, and consistent official and financial records also matter.
When eligible, a homestead exemption supports the claim that the Florida property is a permanent residence rather than a vacation home. Eligibility should be reviewed separately.