For parents helping a child acquire a South Florida residence, cash and a condo deed are not interchangeable gifts. Tax status, adjusted basis, mortgage debt and homestead eligibility should shape the plan before funds move or ownership changes.
For a parent helping a child establish a South Florida home, the choice can seem straightforward: give the child cash to purchase a residence, or buy the condo and transfer it later. The lifestyle outcome may look identical. The tax consequences need not be.
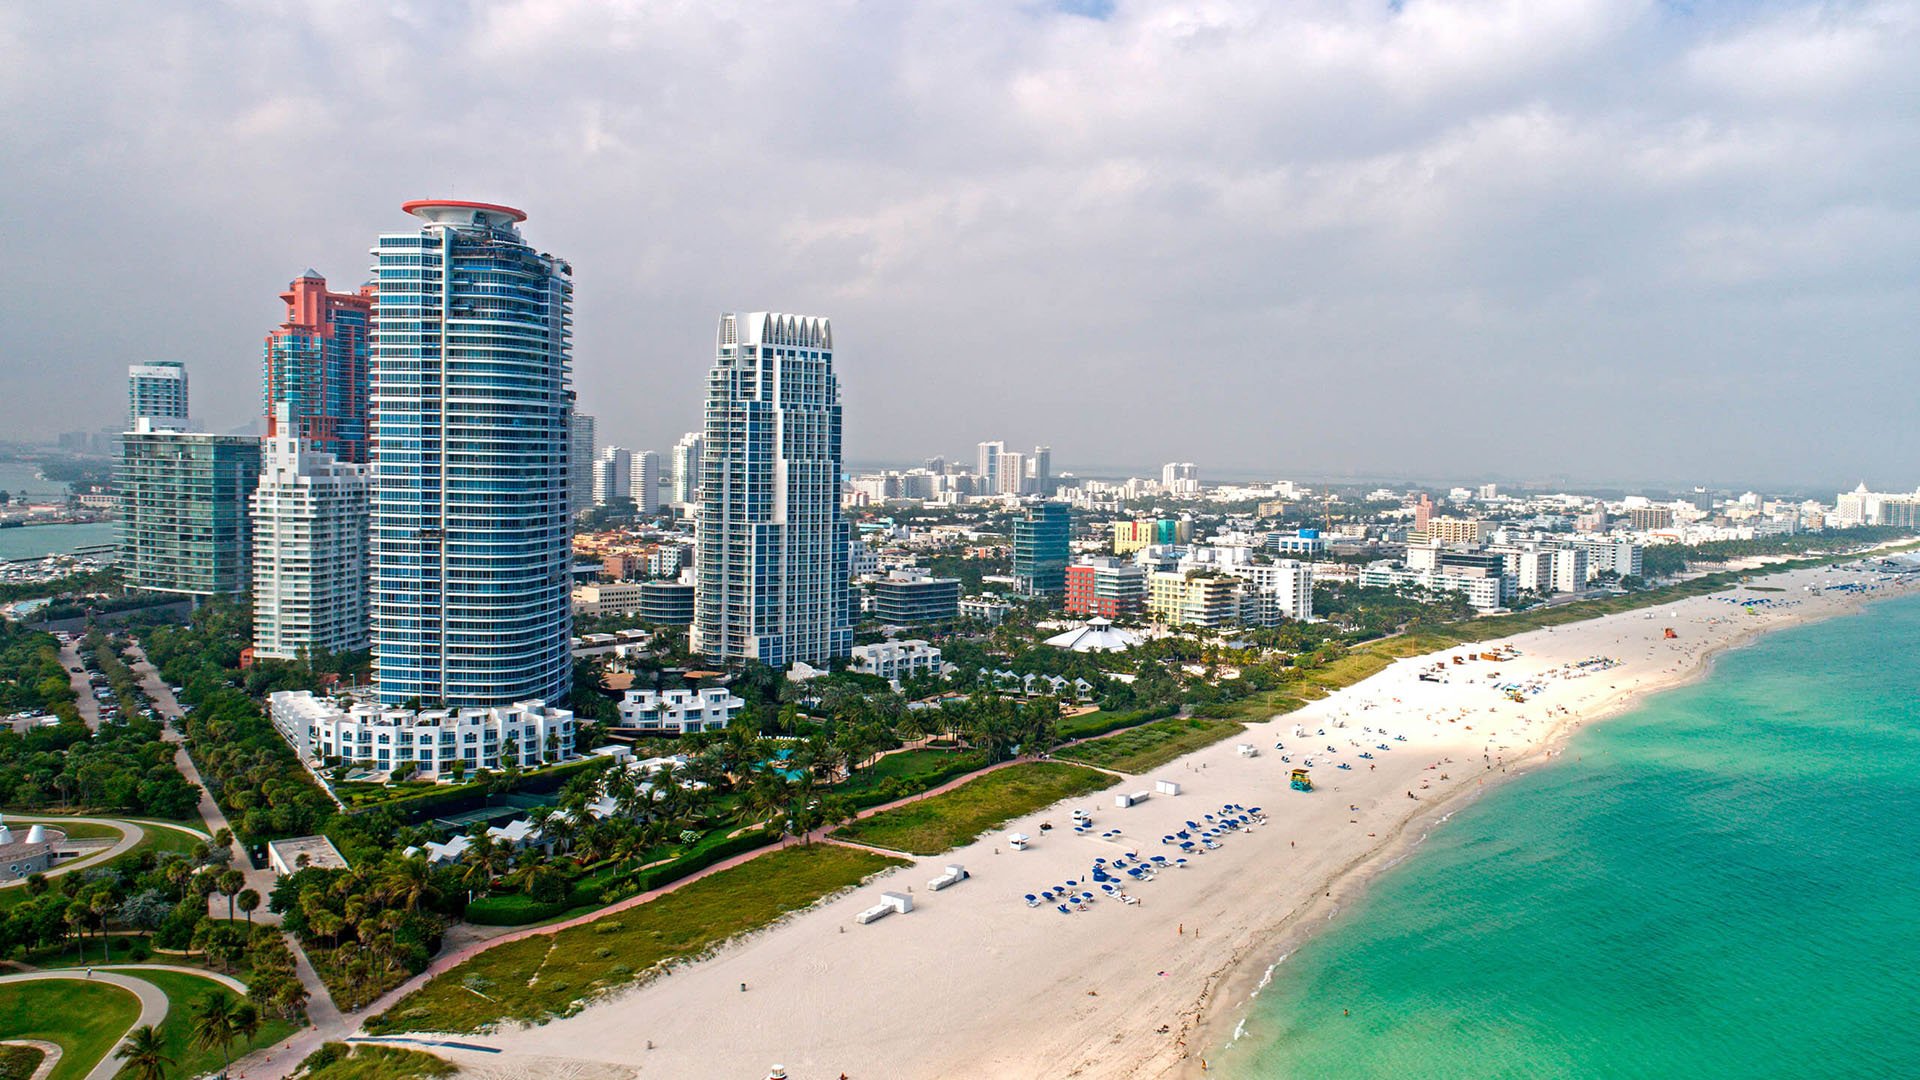
Whether the search centers on Brickell, Miami Beach, Sunny Isles Beach or Fort Lauderdale, the first important decision is not the floor plan. It is who should acquire the property, in what capacity, and with what eventual transfer in mind.
A family considering 2200 Brickell should settle those questions before treating a parent's purchase followed by a deed to the child as equivalent to a cash-funded purchase by the child. Neither route is universally preferable. The sequence warrants its own analysis before the transaction becomes difficult to unwind.
Living outside Florida does not, by itself, make a parent a foreign person for federal tax purposes. Florida residence, U.S. citizenship, domicile and federal tax status are distinct questions. Planning begins by separating them rather than relying on the family's description of someone as an overseas or nonresident owner.
That distinction matters when evaluating exclusions, reporting obligations and the treatment of U.S. real estate. A familiar allowance discussed among U.S. families should not automatically become the planning assumption for a nonresident noncitizen.
The family's objective comes next. Is the intention to establish the child's home immediately, retain parental ownership for now, or pass the property at death? These are different ownership plans, even if everyone expects the child eventually to enjoy the same residence. Advisers should compare the actual alternatives before any cash moves or deed is signed.
A transfer for less than adequate and full consideration is generally a gift for federal gift-tax purposes. For valuation, the relevant figure is generally fair market value when the transfer occurs, not what the parent originally paid.
Basis answers a different question. A child receiving appreciated real estate as a gift generally takes the parent's adjusted basis for calculating a later gain. Current market value does not simply become the child's new basis because a deed changes hands.
Consider a family evaluating Five Park Miami Beach. Giving cash for the child's purchase and transferring an already-owned, appreciated residence are not interchangeable basis strategies. In the second case, the parent's embedded gain generally remains relevant to the child's eventual sale.
Buying and immediately gifting a condo does not inherently create the same appreciated-property concern. The comparison turns on adjusted basis relative to value, not merely on the parent's brief ownership.
Inheritance deserves a separate calculation. Inherited property generally receives a basis tied to fair market value at death, subject to exceptions and estate-valuation rules. A lifetime gift can therefore preserve gain that an inheritance-related adjustment might otherwise eliminate. That is a reason to compare alternatives, not a universal recommendation to postpone a transfer.
For 2026, the federal annual gift-tax exclusion is $19,000 for each recipient from each donor, subject to applicable eligibility rules. Two eligible spouses can generally give a combined $38,000 to a recipient, although gift-splitting elections and reporting requirements may apply.
Exceeding an annual exclusion can require a gift-tax return without creating an immediate tax payment when an applicable lifetime exclusion covers the excess. Reporting and payment are separate questions.
The federal basic estate-and-gift-tax exclusion is $15 million for an individual in 2026. Families should not assume it is available to every foreign or nonresident parent. Nor should they assume that cash and U.S. real estate receive identical gift-tax treatment for a nonresident noncitizen.
Establish eligibility first, then calculate the consequences of the proposed asset transfer. Starting with the largest headline exclusion reverses that order.
A condo's mortgage can substantially change the analysis. Florida documentary stamp tax can apply even when the family describes a conveyance as a gift. For a gift of mortgaged real estate, the state's conveyance rule bases the tax on the unpaid mortgage balance at transfer.
Foreign-person analysis also requires care. Under FIRPTA, a foreign person's gain or loss from disposing of a U.S. real-property interest is generally treated as effectively connected with a U.S. trade or business. A gift can produce taxable gain when liabilities assumed or discharged exceed the transferor's adjusted basis.
For an owner considering a transfer of a residence at Park Grove Coconut Grove, the review should place the debt balance alongside adjusted basis and current value. Calling the deed a gift does not settle the federal analysis, particularly where debt is involved. Equally, a gift should not automatically be described as a taxable sale; structure and liabilities matter.
Ownership alone does not establish Florida homestead eligibility. The property generally must be the owner's permanent residence or the permanent residence of the owner's dependent. A qualifying exemption also provides access to Save Our Homes assessment protection.
A parent's exemption does not automatically transfer with the condo. The child must establish eligibility as the new owner.
For a family considering Rivage Bal Harbour, intended use belongs in the ownership discussion alongside taxes and succession. A residence intended for permanent occupancy and one intended for occasional family visits should not share an unexamined homestead assumption.
Begin by confirming the parent's status and defining the family's objective. Then assemble the financial record: adjusted basis, support for fair market value, outstanding mortgage debt and the contemplated ownership arrangement. Keeping value, basis and debt distinct helps prevent an attractive property from obscuring a costly transfer decision.
Next, compare a cash gift for the child's purchase, a lifetime gift of the condo and an inheritance plan. Weigh future gain alongside present gift-tax exposure, reporting and any estate implications. No single exclusion or basis rule resolves every part of that comparison.
Before implementation, ask the appropriate advisers to review tax and transfer requirements. Practical due diligence should also address title, possible lender consent, association procedures, insurance and assessments. These are review points, not assumptions that every building or transaction imposes identical requirements.
The disciplined approach is to choose the ownership sequence before selecting the transfer document. For a family making a substantial residential gift, that preparation is part of protecting the generosity itself.
For a considered approach to your family's South Florida property search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Florida residence, U.S. citizenship, domicile and federal tax status are distinct questions that should be established before planning the transfer.
Not necessarily. An appreciated condo gifted during life generally carries the parent's adjusted basis for calculating the child's later gain, so the two routes are not interchangeable basis strategies.
It is $19,000 for each recipient from each donor, subject to applicable eligibility rules. Two eligible spouses can generally give a combined $38,000, although elections and reporting requirements may apply.
No. A gift-tax return may be required without an immediate payment when an applicable lifetime exclusion covers the excess.
No. The federal basic estate-and-gift-tax exclusion should not be assumed available to every foreign or nonresident parent; eligibility must be established first.
Gift-tax valuation generally uses fair market value when the property is transferred, rather than the parent's original purchase price.
Generally not for calculating a subsequent gain. The child receiving appreciated real estate generally takes the donor's adjusted basis.
Inherited property generally receives a basis tied to fair market value at death, subject to exceptions and estate-valuation rules. A lifetime gift may preserve embedded gain that an inheritance-related adjustment might otherwise eliminate.
Yes. Florida documentary stamp tax can apply based on unpaid mortgage debt, and a foreign parent's gift can produce taxable gain when liabilities assumed or discharged exceed adjusted basis.
No. The child must establish eligibility as the new owner; ownership alone is insufficient, and the property generally must be the owner's or the owner's dependent's permanent residence.