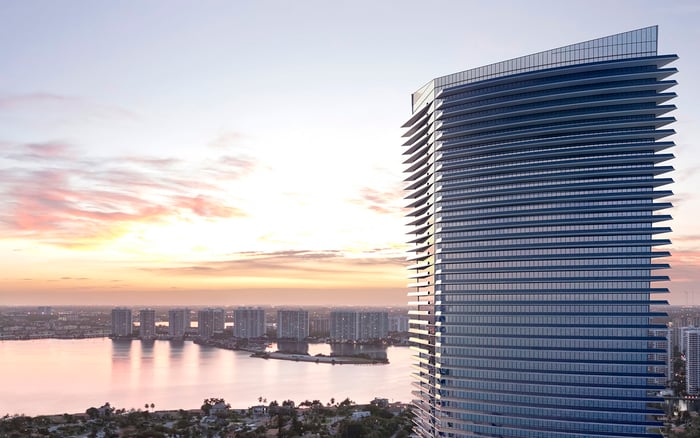
For a foreign buyer, a South Florida condo acquisition should include a deliberate review of estate-tax status, ownership structure and liquidity. The decisions made before title is finalized can shape both the family’s tax exposure and its ability to retain the residence.
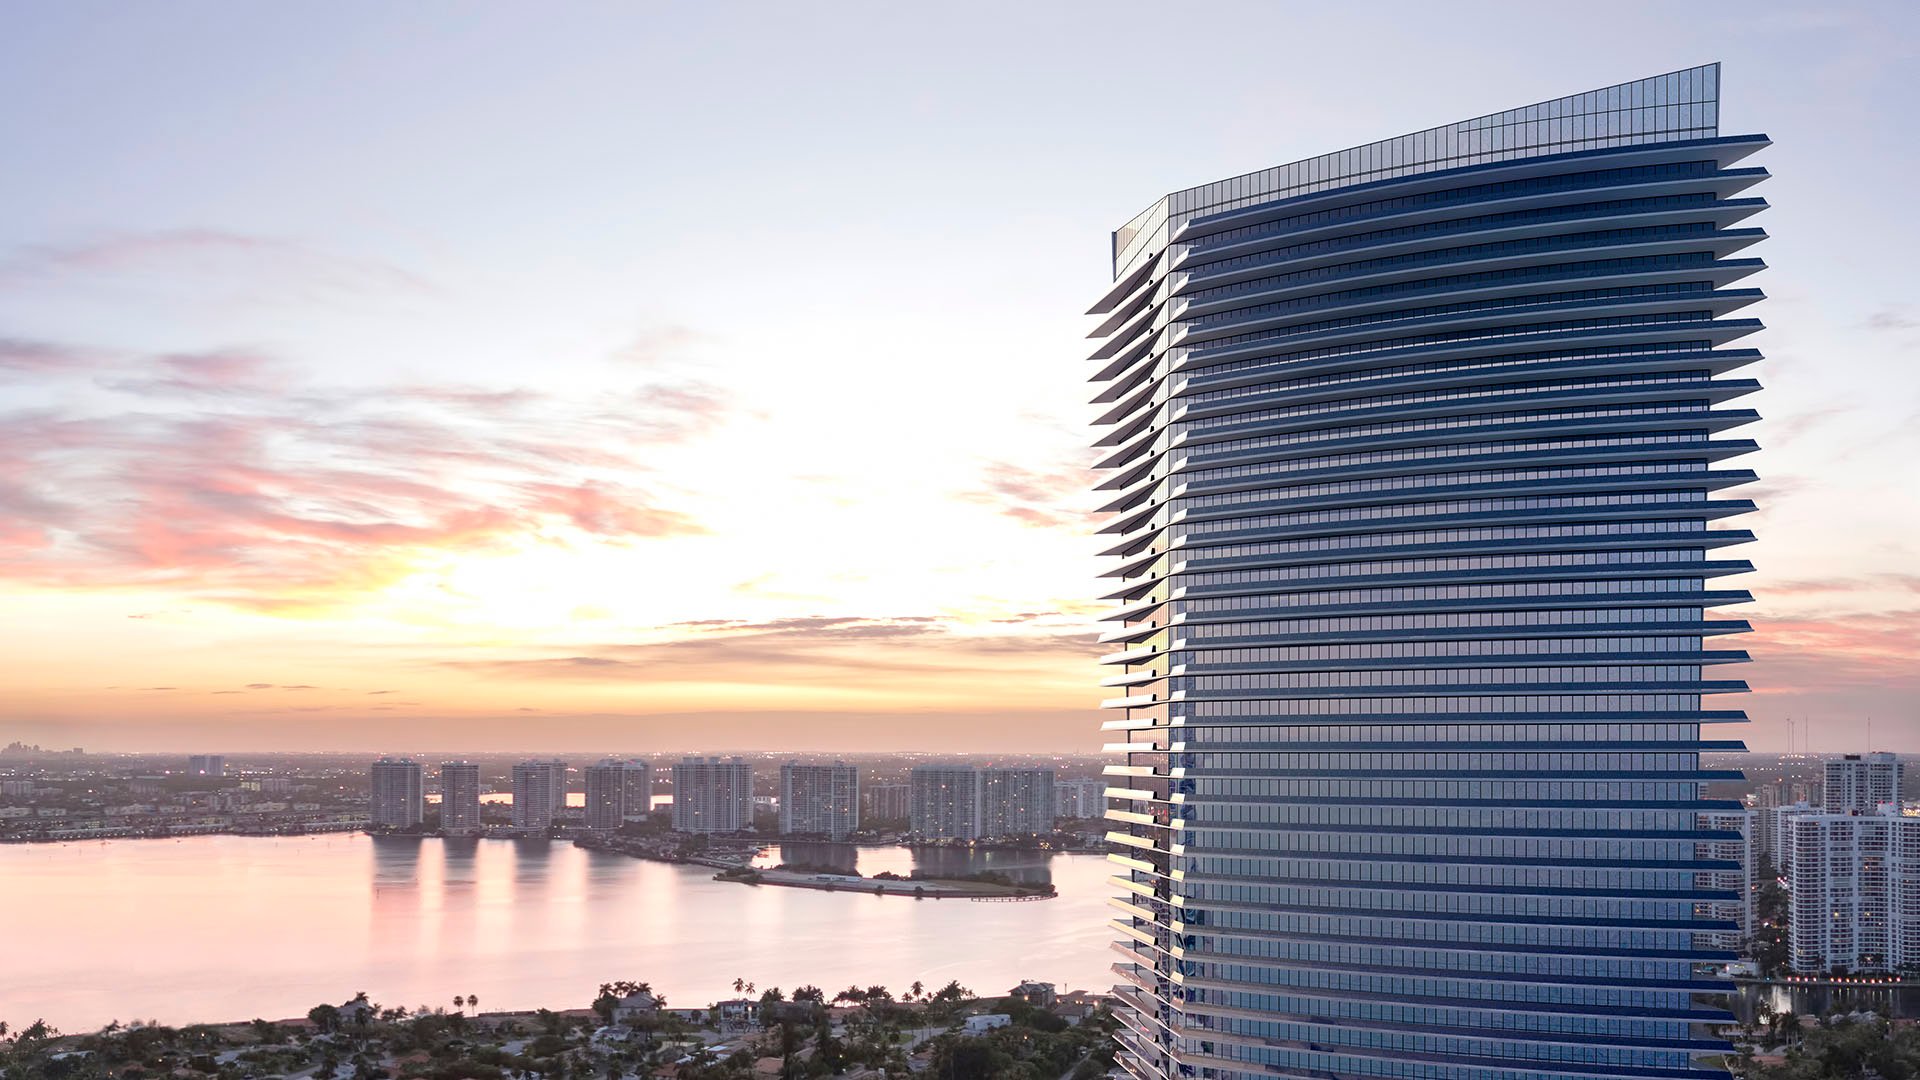
A South Florida residence can be both a personal retreat and an asset intended to remain in the family. For an international buyer, those ambitions deserve consideration together. The question is not simply who will acquire the condo, but what the family would own, owe and need to administer if that owner died.
From offer to recording, estate planning should accompany the purchase, not follow it. This is a framework for ownership, tax exposure and liquidity-not a procedural guide to deposits, inspections or county recording. Its purpose is to help the buyer reach the title decision with a considered plan.
For someone evaluating The Residences at 1428 Brickell, the Brickell address is one decision; the legal and financial framework for ownership is another. The latter calls for coordinated advice from cross-border tax and estate counsel before title is finalized.
Foreign citizenship alone does not determine U.S. estate-tax treatment. The rules for nonresident noncitizens, commonly abbreviated NRNCs, concern individuals who are neither U.S. citizens nor U.S.-domiciled for estate-tax purposes. A buyer with foreign citizenship should not assume this classification applies.
For NRNCs, U.S. estate taxation generally reaches U.S.-situated assets rather than worldwide assets. A directly owned South Florida condo is U.S.-situs real estate and is included in the owner’s U.S. gross estate at death.
The first planning step is therefore personal, not architectural: establish citizenship and estate-tax domicile, then assess whether an applicable estate-tax treaty changes the analysis. Treaty benefits can affect credits, deductions or situs treatment, but depend on the particular treaty and the individual’s circumstances. They should be confirmed, not presumed from nationality alone.
The general Form 706-NA filing threshold is $60,000. Filing is required when U.S.-situated assets at death, together with specified gift-tax amounts, exceed that figure. This is a filing trigger, not a statement that every dollar above it is taxed at one rate.
Federal estate-tax rates are graduated and reach 40%. Describing the exposure as a flat 40% charge on the entire condo would be misleading. The calculation requires analysis of asset values, allowable deductions, applicable credits and any relevant treaty provisions.
Form 706-NA is the estate-tax return for NRNC decedents and is used to compute estate and generation-skipping transfer tax liability where applicable. For a luxury buyer, the useful exercise is a tailored estimate of potential liability-not a headline percentage applied to the purchase price.
Estate value generally reflects fair market value at death, rather than the original developer-contract or closing price. An acquisition budget and an estate-liquidity budget therefore answer different questions. The first funds the purchase; the second should address the residence’s value when the estate is assessed.
A buyer considering The Perigon Miami Beach should distinguish the Miami Beach purchase decision from the family’s longer-term funding needs. Ask advisers to test different future valuations without treating appreciation as assured. A plan based solely on today’s contract price may not reflect the eventual exposure.
Mortgages, debts and administration expenses can matter, but deductions are subject to NRNC-specific limitations and documentation requirements. Do not assume that subtracting the mortgage balance from the condo’s value produces the taxable estate. The estate-tax computation also requires separate values for U.S. and non-U.S. assets. Worldwide asset information can therefore remain relevant even when the tax generally reaches only U.S.-situated property.
The ownership decision should weigh estate exposure alongside lifetime taxation, compliance and succession needs. No structure should be selected merely because it sounds protective.
Direct ownership.
The condo remains U.S.-situs real estate in the owner’s gross estate. Transferring the property after death may also require Florida ancillary administration, adding a local probate process alongside administration in the owner’s home jurisdiction.
A U.S. corporation.
Corporate ownership is not automatically an estate-tax shield. Shares of corporations organized under U.S. law are U.S.-situs assets, even when the share certificates are held abroad. Changing the asset from a condo to domestic corporate shares does not, by itself, resolve the situs issue.
A foreign corporation.
Properly structured ownership can mitigate estate-tax exposure because the buyer owns generally non-U.S.-situs foreign shares rather than the condo directly. That potential benefit must be weighed against corporate taxation and compliance burdens. It is an option for analysis, not a default recommendation.
Trusts and partnerships.
These arrangements require structure-specific review. Neither label establishes that U.S. real estate has been removed from an NRNC’s taxable estate.
Before selecting an ownership vehicle, ask counsel for a written comparison of the proposed structure’s treatment during ownership, on disposition and at death. The most attractive estate-tax result should not be considered in isolation from its other consequences.
An estate can hold a valuable residence without sufficient accessible funds to meet its tax obligations. That distinction matters when the intention is for heirs to keep the condo rather than sell it quickly.
For a family considering Bentley Residences Sunny Isles in Sunny Isles Beach, liquidity planning should begin with that intended outcome. Ask advisers to compare potential estate obligations with the funding available to meet them. Revisit the analysis as values and family circumstances change.
Life insurance can provide liquidity for estate taxes and may help heirs retain the residence. It does not itself eliminate estate tax on a directly owned condo. Treat insurance as a possible funding tool, subject to professional review of the arrangement-not as a substitute for ownership planning.
Before title is finalized, seek clarity on four points: the buyer’s estate-tax classification, the proposed ownership structure, the estimated exposure and the intended source of liquidity. Address potential Florida ancillary administration separately from the tax calculation. Paying a liability and transferring a residence are distinct tasks.
Keep disposition planning separate as well. FIRPTA withholding concerns disposition, not estate tax. A structure should therefore be evaluated for both lifetime income-tax consequences and taxation at death, rather than judged against only one objective.
The aim is not complexity for its own sake. It is an ownership plan that supports the family’s intentions beyond acquisition, informed by individualized legal and tax advice.
For a discreet conversation about your South Florida residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. These rules concern people who are neither U.S. citizens nor U.S.-domiciled for estate-tax purposes; foreign citizenship alone does not establish that status.
Yes. A directly owned South Florida condo is U.S.-situs real estate and is included in the owner’s U.S. gross estate at death.
It is the general Form 706-NA filing threshold for U.S.-situated assets at death together with specified gift-tax amounts. It does not, by itself, determine the tax payable.
No. Federal estate-tax rates are graduated and reach 40%, while the actual liability depends on the applicable computation, deductions, credits and treaty provisions.
Generally, fair market value at death determines estate value rather than the original developer-contract or closing price.
Allowable deductions can reduce the taxable U.S. estate, but mortgages and other debts are subject to NRNC-specific limitations and documentation requirements. The mortgage balance should not automatically be treated as fully deductible.
Not automatically. Shares of a corporation organized under U.S. law are U.S.-situs assets even when the certificates are held abroad.
Properly structured foreign-corporation ownership can mitigate estate-tax exposure but introduces corporate tax and compliance trade-offs. Trusts and partnerships require structure-specific analysis and are not automatic solutions.
Insurance can provide liquidity to help pay estate taxes and potentially avoid a rushed sale. It does not itself eliminate tax on a directly owned condo.
No. FIRPTA withholding is a separate disposition-related issue, so ownership planning should consider both lifetime tax consequences and taxation at death.