A disciplined ownership-cost review for Alma and Onda buyers, separating advertised association fees from contractual obligations, service commitments, and the documents that should guide a long-term purchase.
A considered residence purchase is more than an acquisition of space. It is a commitment to the services, maintenance standards, and financial decisions that sustain life there. For buyers weighing Alma Bay Harbor Islands against Onda, the useful question is not simply which monthly charge is lower. It is what that charge covers, how it can change, and which obligations sit outside it.
Keep three categories distinct: the purchase contract, the association budget, and the agreements supporting ongoing services. A quoted assessment does not explain all three. Nor does an amenity description establish a permanent service commitment. The strongest comparison begins with documents for the specific residence and relevant budget period, not a building-wide headline.
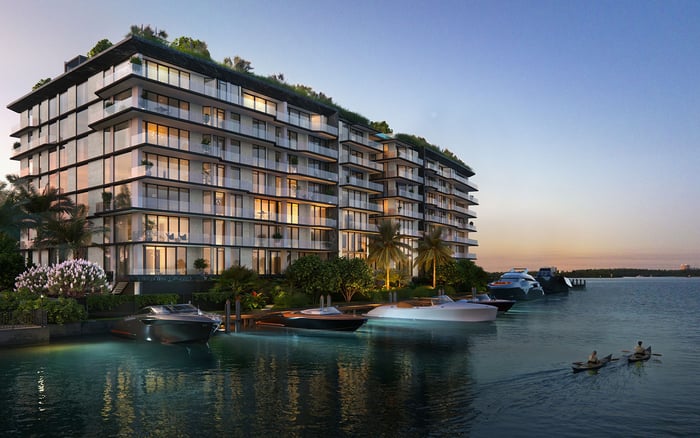
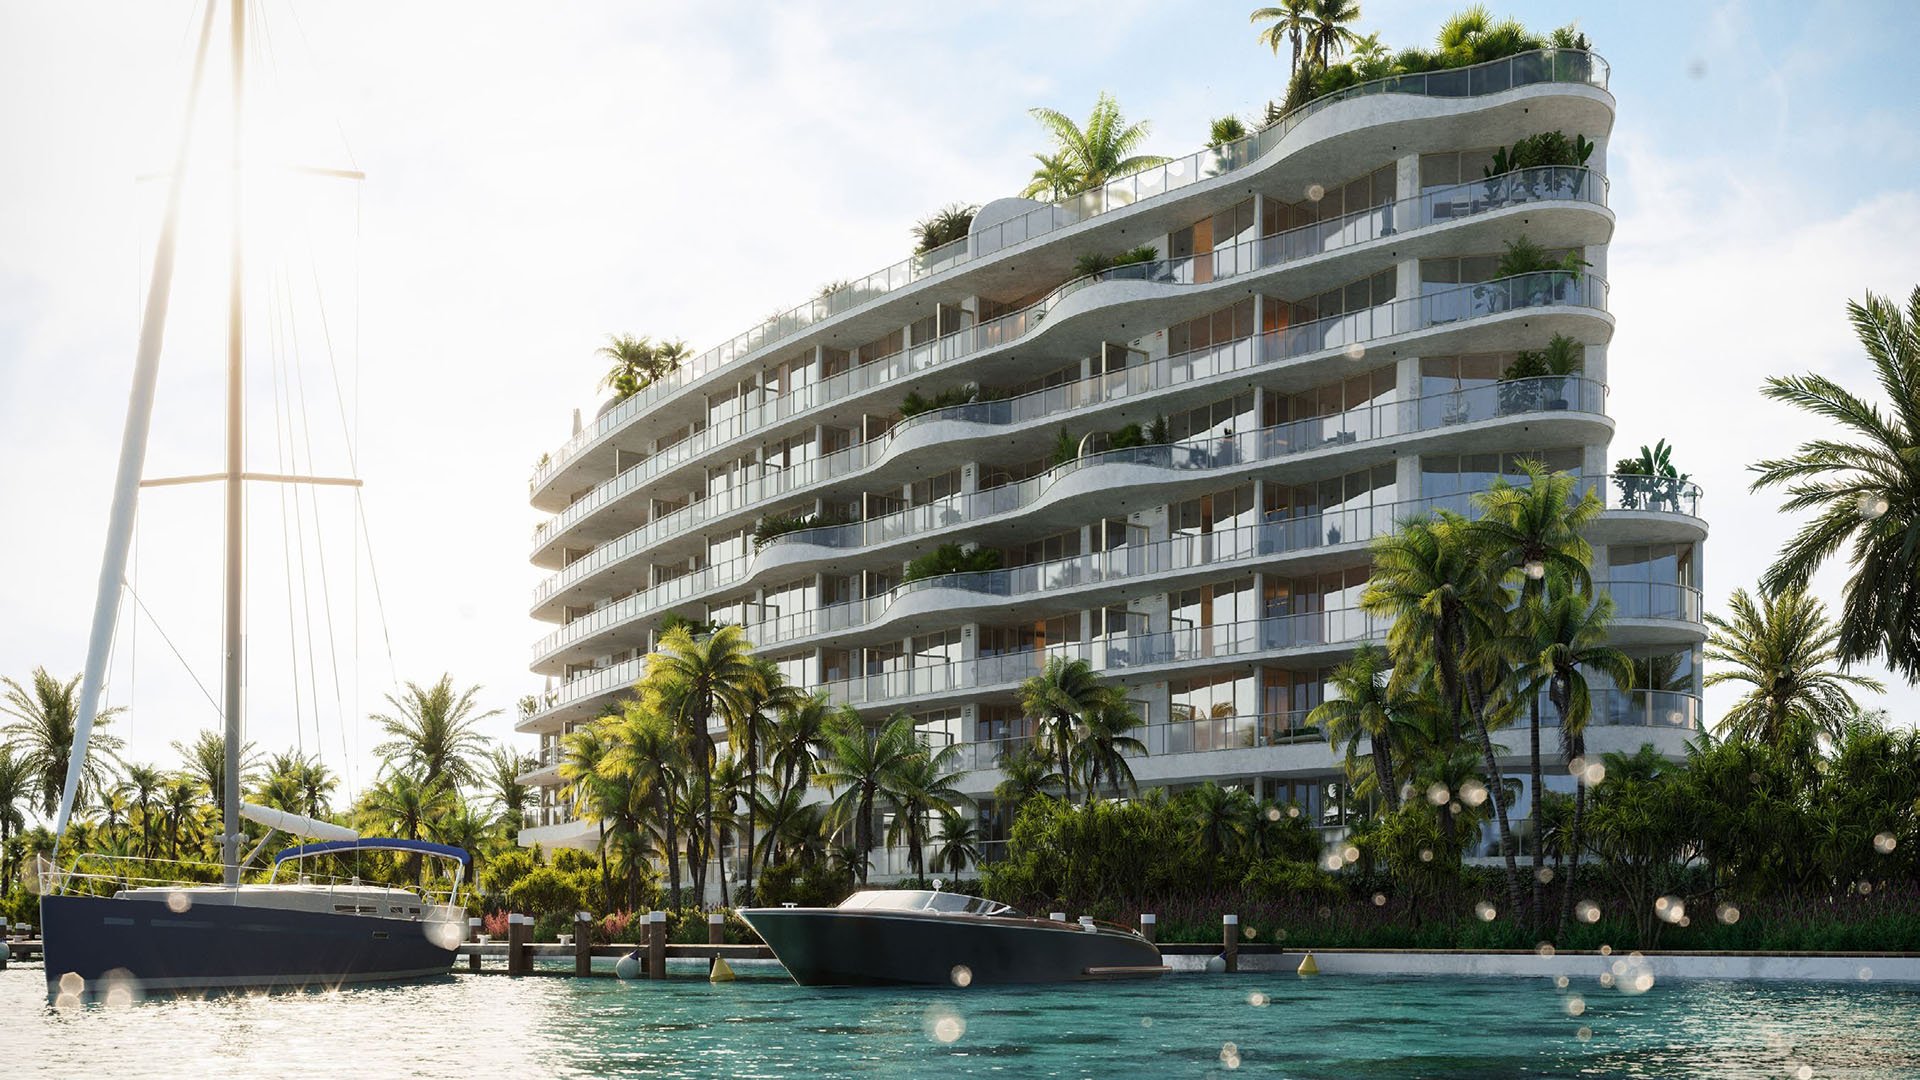
Onda Bay Harbor, at 1135 103rd Street, offers several advertised reference points. Unit 202 is listed with a monthly association fee of $3,743; Unit 602 with $4,400; Unit 403 with $7,627; and Unit 504 with $8,737.
These are individual listing figures, not an assessment schedule for a single period. Their dates and unit details differ. The spread should therefore not be read as evidence of fee increases over time, inconsistent billing, or a definitive range for every residence in the building.
A separate snapshot of 10 listings places the median advertised fee at $7,075 monthly, with an approximate monthly figure of $2.46 per square foot. A building-level maintenance figure also shows $2.46 per square foot monthly. Neither establishes the charge payable for a particular purchase.
For budgeting, request the current unit assessment and its effective date in writing. Reconcile that amount with the adopted budget and the residence’s allocation of common expenses. Use advertised figures to frame questions, not settle them.
Onda’s listing descriptions illustrate why inclusions deserve as much attention as the amount. Unit 602 identifies common areas, grounds maintenance, sewer, trash, and water. Unit 202 identifies amenities, grounds maintenance, pools, sewer, security, trash, and water.
Unit 403 lists management, amenities, common areas, grounds and structural maintenance, sewer, security, trash, and water. Unit 504 lists landscaping, security, building exterior, common areas, outside maintenance, amenities, elevator, hot water, parking, and sewer.
The wording differs. That does not establish that owners receive different services or that a category omitted from one listing is excluded from that residence’s assessment. The descriptions need to be reconciled with the governing documents and current operating arrangements.
Ask what each category funds. For security, request the documented scope and coverage hours. For maintenance, distinguish routine work from replacement obligations. For amenities, clarify what is included and what requires separate payment. These are diligence questions, not statements about either project’s arrangements.
Contract escalators and association increases belong in separate parts of the review. A purchase-price adjustment, if present, concerns acquisition terms. An escalation provision in a service agreement concerns an ongoing operating obligation. An association assessment change is a third issue. None should be inferred from the others.
Have counsel identify whether the purchase agreement permits adjustments, what triggers them, how they are calculated, and whether limits apply. Review notice provisions, payment timing, and any applicable buyer rights alongside the adjustment language. Do not assume either Alma or Onda uses a particular formula.
For service agreements, request the provisions governing price changes, renewal, termination, and scope. Where escalation provisions exist, ask whether increases are fixed, tied to an index, or dependent on specified costs. A starting price alone is insufficient to evaluate a multiyear commitment.
Organize the review chronologically: signing, any applicable pre-closing updates, closing, and the first ownership budget period. At each stage, distinguish estimates from documented obligations. This avoids comparing an early projection for one residence with a later operating figure for another.
For Alma and Onda alike, request the applicable budget, supporting financial statements, the unit’s assessment allocation, and documentation addressing reserves, insurance, and any special assessments. Onda’s advertised fees do not establish reserve adequacy, insurance coverage, special-assessment status, or future increases.
Keep the comparison consistent. Separate operating expenses from reserve contributions, identify separately billed items, and confirm the period each document covers. Ask for explanations of material differences rather than treating a lower total as an automatic advantage.
If Bay Harbor Towers enters the shortlist, apply the same document standard rather than carrying over assumptions from Onda’s advertised charges. Buyers also considering Bal Harbour should maintain that discipline across locations: proximity does not make budgets or contractual obligations interchangeable.
An association charge belongs on one line of the ownership plan; it is not the entire plan. Create separate entries for the buyer’s applicable property taxes, insurance, financing, in-residence upkeep, and optional services. Use residence-specific information rather than allowances borrowed from another building.
For a residence used seasonally, ask who handles access, inspections, maintenance coordination, and unexpected issues during absences. Establish whether requested support is included, separately contracted, or unavailable. Do not assume a service-oriented setting includes private home management.
A buyer also exploring The Well Bay Harbor Islands should ask the same questions about included and optional support. Compare the documented service scope and its cost, not the promise suggested by a project’s name or positioning.
Build a base case from confirmed obligations, then test hypothetical changes separately. Label those scenarios as planning assumptions, not forecasts for either association.
A defensible Alma-versus-Onda decision should rest on comparable documents, not mismatched fee quotations. Onda’s advertised figures provide useful starting points, but they do not establish which project will cost less over a full ownership period.
Before committing, answer three questions clearly: what is payable now, what can change under the relevant documents, and what service standard the payment supports. That clarity is part of the luxury purchase itself, allowing the residence to remain a place of ease rather than recurring financial uncertainty.
For a discreet conversation about your Bay Harbor Islands shortlist, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationOnda Residences is at 1135 103rd Street, Bay Harbor Islands, FL 33154.
The advertised monthly figures are $3,743 for Unit 202, $4,400 for Unit 602, $7,627 for Unit 403, and $8,737 for Unit 504. They are listing figures, not confirmed current assessments.
No. It is the median advertised fee across a snapshot of 10 listings, not a charge established for every residence.
The $2.46 monthly figure is a building-level reference, not a unit-specific assessment schedule. Request the current assessment for the residence being purchased.
The descriptions include common-area upkeep, utilities such as water and sewer, and various maintenance and amenity categories. The wording differs by listing and should be checked against current association documents.
No. Differences in advertised wording do not establish different service entitlements or exclusions.
The advertised figures do not establish that conclusion. A defensible comparison requires current, residence-specific charges and comparable budget and contract documents.
Ask counsel to examine any adjustment triggers, calculation methods, limits, notice provisions, and payment timing. Review purchase-contract adjustments separately from service-agreement increases.
No. They do not establish reserve adequacy, insurance coverage, special-assessment status, or future increases.
Use separate entries for applicable property taxes, insurance, financing, in-residence upkeep, and optional services. Confirm each item for the specific residence and avoid double-counting included services.