For Seattle families considering Fort Lauderdale preconstruction, a successful purchase begins with coordinating deposit obligations, investment liquidity, closing finance and the practical timing of relocation.
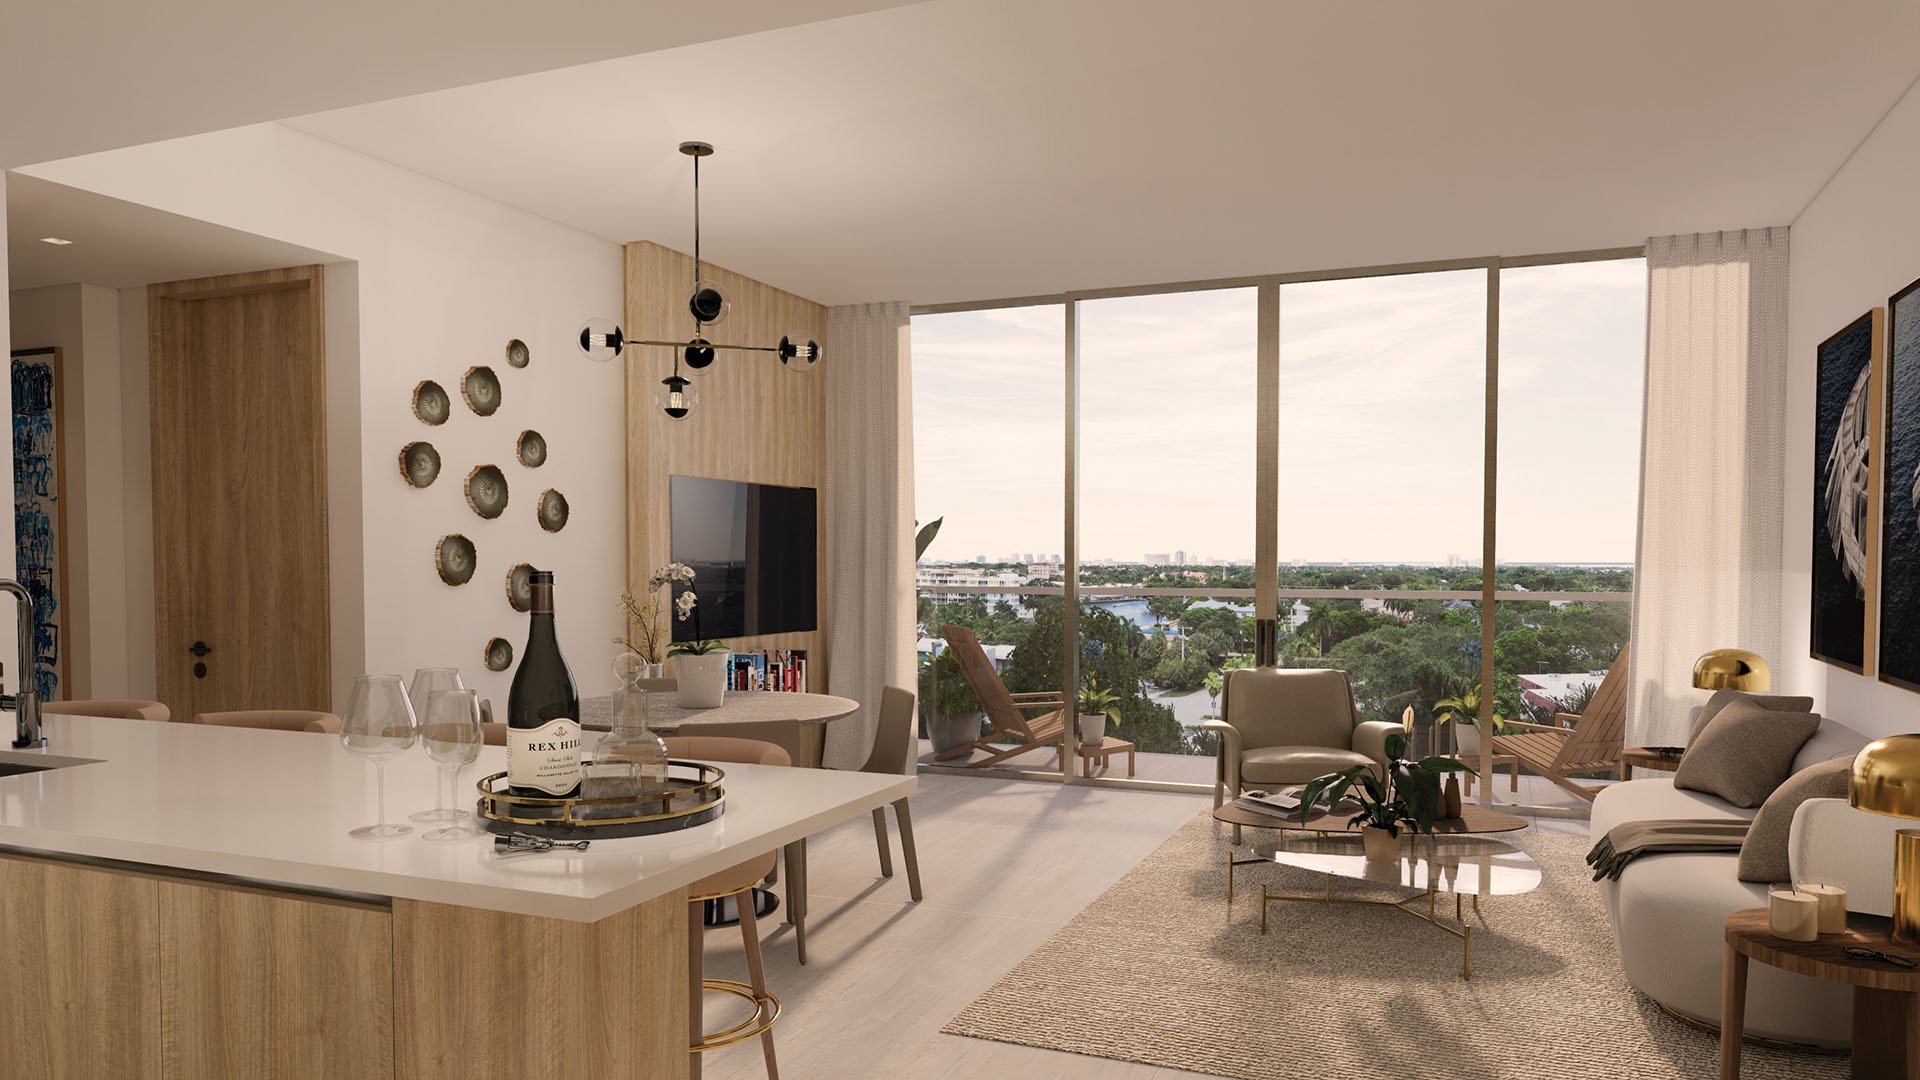
For a Seattle family moving to Fort Lauderdale, choosing a residence is only one part of the transition. The more consequential task is aligning three calendars: the developer’s payment milestones, the household’s access to capital and the family’s move. Coordinate those calendars, but never assume they will move together.
A preconstruction commitment can require substantial cash long before keys are available. Proceeds from a Seattle home sale, an investment liquidation or a business transaction may arrive on a different timetable. The objective is not simply to demonstrate sufficient wealth. It is to have funds available when the contract requires them, without compromising the family’s broader financial position.
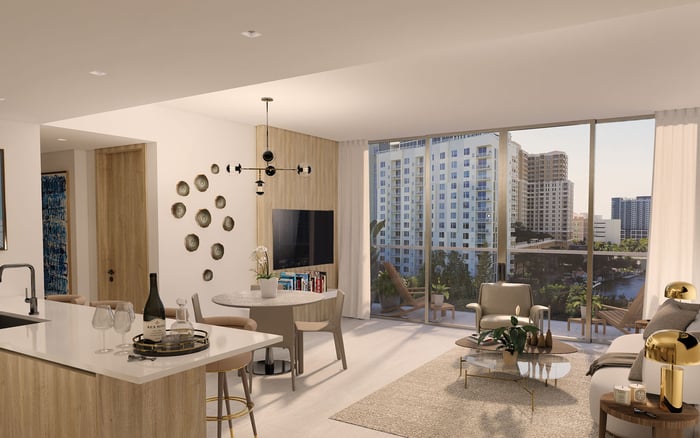
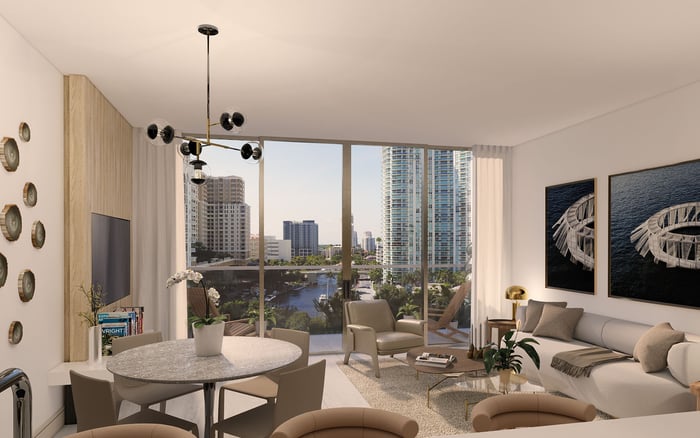
For a household considering Sixth & Rio Fort Lauderdale, planning should begin with the current purchase documents rather than a generic payment illustration. A residence should fit both the family’s lifestyle and its funding calendar.
Build the deposit plan from the selected residence’s purchase agreement. Confirm the total required before closing, each installment and the remaining closing balance rather than relying on a general market range or another development’s schedule.
If a reservation precedes the purchase agreement, review its written conditions separately. Ask counsel to confirm whether the reservation payment is refundable, any deadlines for requesting its return and how it would be credited under an executed agreement.
Have counsel convert the purchase agreement’s deposit schedule into a working ledger showing each amount, its triggering event, notice requirements and the consequences of late payment. Distinguish calendar-based obligations from construction milestones. Do not treat an estimated delivery date as permission to postpone an installment.
The remaining purchase balance is generally funded at closing through cash or mortgage proceeds. Earlier deposits need their own funding plan. A proposed closing mortgage should not be treated as money available for construction-stage installments.
Be precise when speaking with a private bank. A portfolio mortgage and a securities-backed credit line are not interchangeable. Ask the lender to identify the proposed product, its collateral, permitted uses, funding conditions and repayment obligations in writing. Do not build the deposit calendar around a facility that has merely been discussed.
If securities-backed borrowing is proposed for deposits, treat it as an option requiring specific lender confirmation, not an assumed entitlement. Ask how changing collateral values could affect available credit, what circumstances could require repayment and how the family would respond without relying on an immediate asset sale. If a cross-collateralized structure is proposed, have advisers identify every asset and obligation involved.
Separately, request project-level review for the intended condo loan program. Personal financial strength does not establish a development’s eligibility. For a purchase under consideration at St. Regis® Residences Bahia Mar Fort Lauderdale, seek confirmation for the specific development and financing structure. Do not assume a banking relationship resolves the question.
A useful planning framework divides capital into three categories: money for signed deposit obligations, money for the household transition and money intended for closing. Keep those categories distinct even if the assets sit within a broader portfolio.
Assign each installment a primary funding source and a backup. If the primary source is a Seattle property sale, ask what happens if the sale completes after the payment deadline. If it is a planned investment sale or compensation event, have the relevant advisers confirm timing, restrictions and the amount available for use.
Avoid counting the same asset twice: once as collateral supporting borrowing and again as unrestricted cash for closing. A projected liquidity event should likewise remain conditional until its proceeds are available.
Stress-test the plan against an earlier contractual payment trigger, a delayed sale, lower portfolio values and a later-than-expected move-in. Preserve a separate allowance for temporary housing, travel and overlapping household expenses. The appropriate reserve is family-specific; relocation spending should not compete with an imminent deposit.
Higher deposits reduce the remaining purchase balance, but lower closing leverage is not the same as lower interim liquidity risk.
Before signing, have a Florida real-estate attorney review the deposit exhibit, escrow instructions, permitted developer draws, default provisions and refund rights. Do not assume that placing funds in escrow means every installment will remain untouched until closing.
Ask counsel whether any deposits may be used for construction under the proposed agreement and applicable Florida law. Request an explanation of the protections, conditions and exceptions relevant to those funds rather than relying on a blanket assurance.
Due diligence should extend beyond payment percentages. Examine the developer’s track record, financing structure and presales. Ask what documentation supports the proposed arrangement and how the contract addresses delays, buyer default and circumstances permitting a refund. Understanding when capital becomes committed is as important as understanding when it must be transferred.
For Seattle families, the household calendar deserves its own contingency plan. Consider school transitions, temporary accommodation and the disposition of the existing home alongside construction timing. Do not make them dependent on an assumed delivery date.
If the search also includes Four Seasons Hotel & Private Residences Fort Lauderdale, compare the actual transaction and possession terms of the residence under consideration. Do not carry a preconstruction funding assumption from one opportunity into another.
Domicile planning requires separate advisory attention. Ask legal and tax advisers how physical presence, address changes, driver’s-license updates, voter registration and other evidence of the family’s center of life apply to the intended Florida move. Neither a purchase contract nor an anticipated completion date should be treated as a guarantee of tax savings.
Before committing, have the real-estate attorney, lender, investment adviser and tax adviser work from the same deposit ledger. Record which funds are available, which remain conditional and who is responsible for confirming each next step.
Revisit that ledger as contractual milestones approach and household circumstances change. The strongest plan preserves choice: the ability to meet obligations without a forced sale, arrange the move without relying on a single date and approach closing with financing already examined.
For a discreet conversation about aligning your Fort Lauderdale residence search with your family’s purchase timeline, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationUse the selected residence’s purchase agreement to establish the total required before closing. Confirm every installment and the remaining closing balance before committing.
Record each payment amount, its triggering event, notice requirements and the consequences of late payment. Distinguish fixed calendar deadlines from construction milestones.
Check the reservation’s written terms rather than assuming a refund is available. Ask counsel to confirm refund conditions, deadlines and how the payment would be credited under a purchase agreement.
No. The closing balance is generally paid with cash or mortgage proceeds at closing, so earlier installments require a separate funding plan.
No, they should not be treated as interchangeable products. Ask the lender to confirm the proposed structure, collateral, permitted uses and repayment conditions in writing.
No. Request project-level eligibility review for the intended condo loan program rather than relying on personal financial strength alone.
No. Ask Florida counsel to review any permitted construction use and explain the applicable protections, conditions and exceptions.
A Florida real-estate attorney should examine the deposit exhibit, escrow instructions, permitted draws, default provisions and refund rights.
Assign a backup source for any installment expected to rely on sale proceeds. Test whether the household could meet the payment deadline if the sale completed later than planned.
No. Coordinate domicile documentation and the actual move with legal and tax advisers rather than treating a property purchase as a guaranteed tax outcome.