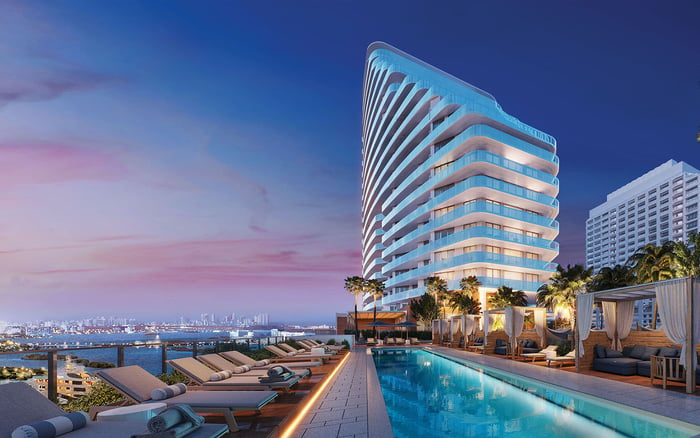
A Frankfurt sale can fund a Fort Lauderdale residence without consuming the portfolio’s flexibility. The key is to establish after-tax proceeds, match liquidity to contractual deadlines, and protect reserves for life after closing.
Selling in Frankfurt and buying in Fort Lauderdale is more than a change of address. It is a decision about how much wealth to hold in residential property, how much liquidity to retain, and which currency will fund future obligations. The residence should fit the portfolio, not quietly become the portfolio.
Start with spendable proceeds, not the Frankfurt sale price. Deduct mortgage repayment, selling expenses, potential taxes, and currency conversion and transfer costs. Then separate money available today from money expected when the German transaction completes. An anticipated receipt cannot substitute for funds available by a contractual deadline.
Before comparing residences at Four Seasons Hotel & Private Residences Fort Lauderdale, establish a purchase ceiling that leaves room for closing costs and retained capital beyond the price. This keeps the property search aligned with the intended financial outcome.
Gains on privately held German property are generally exempt from German income tax when the sale occurs after the ten-year speculation period. That period is generally calculated to the day using the notarized purchase and sale contracts, not move-in dates. Even a small timing difference warrants professional review before signing.
A qualifying owner-occupied sale within ten years may also be exempt where the residence was used in the sale year and the preceding two calendar years. Otherwise, a sale within the taxable period generally exposes the gain to personal income tax. Keep the estimated liability out of the Florida acquisition budget until advisers confirm the treatment.
German exemption does not settle U.S. liability. U.S. citizens and tax residents are generally taxed on worldwide gains, so a Frankfurt sale exempt in Germany may still create U.S. tax. Buying Florida property does not itself establish U.S. tax residency. Coordinate the sale, residency analysis and purchase rather than treating them as separate decisions.
A useful planning framework separates transaction liquidity, post-closing safety reserves and long-term investment capital. These are planning categories, not regulatory requirements.
Transaction liquidity covers deposits, due-diligence expenses, the remaining purchase equity and closing charges. Safety reserves support carrying costs and unexpected demands after ownership begins. Long-term capital remains available for broader investment objectives, rather than becoming an informal backup for an underfunded closing.
Compare cash and financing against the same retained-liquidity target. Cash avoids mortgage-specific charges but commits more equity to one asset. Financing can preserve liquid investments while adding debt service and transaction costs. Neither approach is inherently more sophisticated.
Choose the structure that remains comfortable after allowing for market volatility, recurring expenses and a delayed Frankfurt receipt.
For preliminary budgeting, allow approximately 1-2% of the purchase price for a cash buyer’s closing costs. For a financed purchase, approximately 2-5% is an indicative allowance, depending on financing and transaction details. Neither range replaces an itemized estimate for the actual acquisition.
A calculator covering title charges, state taxes and recording may omit loan origination, appraisal, prepaid interest or buyer escrow reserves. Reconcile each estimate with the funds actually required, identifying what is included and what remains separate.
For a prospective purchase at Sixth & Rio Fort Lauderdale, apply the same discipline: map each contractual payment to an available funding source before committing. Do not assume Frankfurt proceeds will arrive precisely when Florida funds are due.
Plan currency conversion alongside that calendar. Distinguish the euro amount expected from the dollar amount needed, include conversion and transfer costs, and agree on a funding contingency before a deadline becomes urgent.
South Florida luxury preconstruction purchases may require cumulative deposits of approximately 30-50% of the purchase price before closing. Schedules can include 10-20% at contract, 10% at groundbreaking and 10-15% at top-off, with additional payments depending on the development. These are indicative patterns, not established terms for any particular residence.
If St. Regis® Residences Bahia Mar Fort Lauderdale is on the shortlist, obtain the actual contract schedule rather than applying these general percentages to the purchase. Model when each payment becomes unavailable for other purposes, including while the Frankfurt sale remains incomplete.
Deposits generally count toward the purchase price. Do not count them again as an extra acquisition expense when calculating the balance due at closing.
Escrow treatment also requires contract-specific legal review. Protections for the initial 10% differ from the treatment of deposits above that level, which may be available for construction use where law and contract permit. Escrow is not a blanket guarantee, nor is every deposit above 10% automatically released or lost.
The post-closing budget extends beyond mortgage payments. Include Florida property tax, insurance, condominium or HOA charges, and association reserve contributions. Reconcile these components so that reserve contributions already included in regular charges are not counted twice.
For a residence at Auberge Beach Residences & Spa Fort Lauderdale, as for any condominium under consideration, request the association’s structural integrity reserve study and latest structural inspection during due diligence, where applicable. Review reserve balances and pending assessments alongside the operating budget. This is a diligence framework, not a statement about that association’s finances.
Underfunded reserves can lead to special assessments. Size personal reserves around the actual property, household cash flow and tolerance for unexpected costs-not a universal percentage of the purchase price. Keep ordinary carrying costs separate from an allowance for exceptional demands. The reserve decision should rest on documents, not impressions drawn from the building’s presentation.
Before committing, assemble one capital schedule showing net Frankfurt proceeds, potential tax liabilities, dollar funding dates, purchase equity, closing costs and the capital remaining afterward. Compare cash and financed versions on the same basis, with deposits correctly credited toward the price.
Stress-test the plan for delayed proceeds, less favorable currency conversion and higher ownership costs. A transaction that works only when every assumption aligns is not yet comfortably funded.
Keep any continuing German obligations in view and confirm remaining liabilities with advisers before treating those funds as available for the Fort Lauderdale purchase.
The strongest purchase leaves room to enjoy ownership without forcing the next investment decision. Set that retained-capital threshold first, then select the residence within it.
For a discreet Fort Lauderdale property conversation grounded in your broader priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Start with proceeds after mortgage repayment, selling expenses, potential taxes, currency conversion and transfer costs, then protect closing funds and retained reserves.
Gains are generally exempt after the ten-year speculation period. Timing generally follows the notarized purchase and sale contract dates and should be confirmed before signing.
A qualifying sale may be exempt if the seller used the property as a residence in the sale year and the preceding two calendar years. Individual circumstances require tax review.
No. U.S. citizens and tax residents are generally subject to U.S. tax on worldwide gains, so a German-exempt sale may still create U.S. liability.
No. Property ownership should not be equated with U.S. tax residency; the residency analysis requires individual review.
Indicative allowances are approximately 1–2% of purchase price for cash buyers and 2–5% for financed purchases. Obtain an itemized estimate and check for omitted lender charges, prepaids and escrow reserves.
Not automatically. Compare cash and financing against the same post-closing reserve target, considering equity committed, debt service and transaction costs.
South Florida luxury developments may require cumulative deposits of approximately 30–50% before closing, depending on the contract. Deposits generally count toward the purchase price rather than adding to it.
No. Protections for the initial 10% differ from the treatment of amounts above 10%, which may be available for construction use where law and contract permit.
Use actual carrying costs, household cash flow, association reserve information and pending assessments. Request the structural integrity reserve study and latest structural inspection where applicable rather than relying on a universal reserve percentage.