For Oceana Bal Harbour buyers, an initial HOA subsidy is a diligence question, not an established building history. Understanding the durable cost of service requires separating advertised dues from operating expenses, reserve funding and the full cost of ownership.
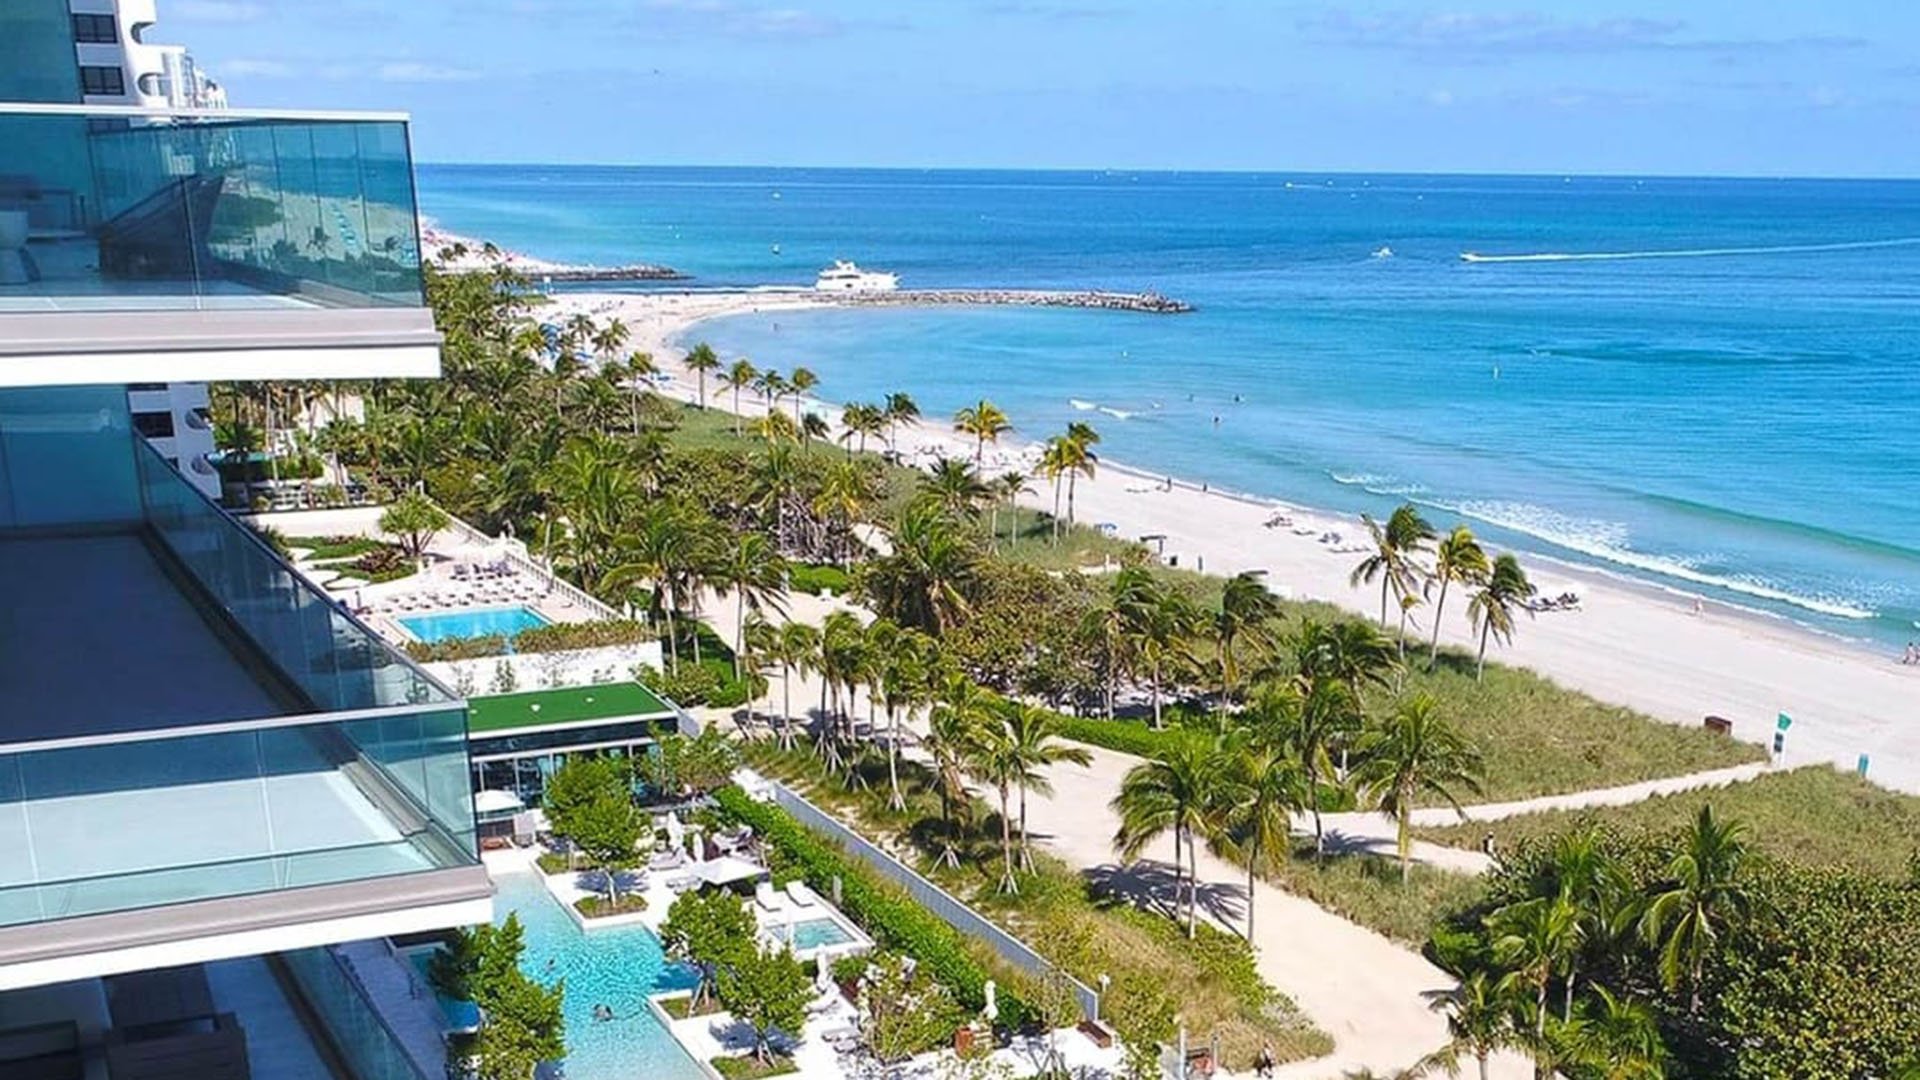
At Oceana Bal Harbour, the appeal begins with an oceanfront setting on the former Bal Harbour Club site, flow-through residences and unobstructed ocean views. For a buyer evaluating long-term ownership, however, the financial question extends beyond the residence: what does it cost to sustain the services and shared infrastructure behind that experience?
An initial HOA subsidy is a diligence question, not an established part of Oceana’s history. Buyers should not assume an initial subsidy, current sponsor support or a scheduled subsidy expiration. The key distinction is between the assessment an owner pays today and the recurring cost owners would need to fund without temporary assistance.
A lower assessment does not necessarily mean a lower cost of service. Nor does a substantial assessment establish financial weakness. The buyer’s task is to understand what the charge funds, how it is allocated and whether the underlying assumptions are durable.
If a sponsor temporarily contributes toward association expenses, owner assessments could fall below the amount owners would otherwise need to provide. That support would not eliminate the expense. It would change who funds it-and potentially for how long.
This distinction matters when comparing an introductory assessment with a mature operating budget. If support ends while expenses remain unchanged, the funding gap must be addressed. Higher owner contributions could be one response; changes in spending or other recurring revenue could also affect the outcome. None of these possibilities should be treated as an Oceana forecast.
For underwriting purposes, stabilized service cost means recurring operating expenses plus appropriate reserve funding, less sustainable non-assessment income. The resulting owner-funded amount must then be allocated under the condominium’s governing documents. This is a framework, not a calculation of Oceana’s actual stabilized dues.
Buyers also considering Rivage Bal Harbour should apply the same questions independently. A comparison should not assume that either property has subsidies, equivalent service obligations or the same budget maturity.
Advertised monthly association fees at Oceana have ranged from $2,553 to $18,020 across listings. A September 7, 2026 listing sample showed a median monthly-equivalent fee of $4,650 among 14 for-sale residences disclosing charges. That median describes the sample-not a building-wide assessment or a quote for a particular purchase.
Individual examples underscore the need for precision. Unit 1205 at 10201 Collins Avenue advertised $3,660 in monthly dues, while Unit 807 at the same address advertised $4,748. Unit 1903N at 10203 Collins Avenue advertised $4,582 monthly.
These figures are dated listing snapshots from different periods. They do not establish fee increases over time, a change in service quality or the withdrawal of sponsor support. Comparing one residence’s charge with another’s is no substitute for reviewing the same unit’s assessment history.
Before relying on a quoted amount, confirm the residence, billing frequency, effective date, allocation basis and any separately billed association obligations. Then reconcile the figure with the current budget and association documentation. A useful comparison begins with verified charges, not simply the smallest number in a search result.
Advertised fee inclusions at Oceana encompass management, cable TV, hot water, parking, pest control, pools, sewer and security. These categories help explain what the association charge supports. They do not reveal whether each budget line is sufficient or how future obligations are funded.
Ask for an explanation of insurance, staffing, utilities, maintenance contracts and reserve contributions. Compare budgeted spending with actual results, and ask management to explain material differences. The purpose is not to presume a deficit, but to distinguish recurring expenses from unusual items and temporary funding.
Operating sufficiency and reserve sufficiency require separate attention. A budget that meets near-term bills does not, by itself, demonstrate adequate provision for longer-term work. Conversely, a larger reserve contribution should not automatically be read as a higher day-to-day service cost.
For a buyer comparing Oceana with Fendi Château Residences Surfside, the discipline is the same: verify each property’s inclusions, funding assumptions and unit allocation separately. Proximity along the coast does not establish financial comparability.
Begin with the adopted association budget, financial statements, reserve study and any assessment resolution. Read them together; no single document provides a complete answer. Request the unit’s current assessment and any approved changes, including their effective dates.
If sponsor support is identified, request the written agreement. Clarify the amount, duration, conditions, covered expenses and responsibility after expiration. Distinguish ordinary assessments paid on sponsor-owned units from additional support that reduces what other owners must fund. A sponsor payment alone does not establish a subsidy.
Next, ask whether operating deficits, reserve funding changes or approved spending commitments affect the forward budget. These are diligence questions, not statements about Oceana’s present condition. Any modeled adjustment should be traceable to a document or clearly labeled as a buyer’s assumption.
Oceana’s association maintains a portal with instructions for requesting estoppels and condominium questionnaires. Management contact details are [email protected] and 786-623-4305. Use those channels to request the appropriate documentation. A unit-specific balance confirmation, however, does not replace analysis of the association’s finances.
The advertised figures for Unit 1205 pair $3,660 in monthly dues with $43,966 in annual property taxes. Annualized dues total $43,920, illustrating how a tax bill can represent a separate expense of comparable scale. These advertised figures are illustrative, not a current ownership quote.
Historical taxes are not an estimate of a buyer’s post-purchase bill. Build a separate ownership schedule for association charges, buyer-specific taxes, applicable insurance, financing and residence-level expenses. Keep any confirmed special assessment distinct from recurring dues. The fee examples do not establish any specific Oceana special assessment.
A thoughtful purchase model should separate verified current obligations from a document-supported forward case. If temporary assistance exists, model its removal explicitly. If none is documented, do not manufacture a subsidy adjustment merely because the listing fee appears attractive.
The objective is not to predict a dramatic increase. It is to establish whether recurring funding and an intelligible reserve plan support the expected service experience. Oceana’s stabilized, fully funded cost cannot be derived from advertised fees alone. For the discerning buyer, clarity on that distinction belongs alongside the view, floor plan and purchase price.
For a considered perspective on South Florida ownership and residence selection, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAn initial HOA subsidy is not established as part of Oceana’s history. Buyers should treat sponsor support and any expiration date as questions to verify, not assumptions.
Temporary sponsor support could reduce owner assessments without reducing the underlying expenses. If that support ends, the association would need to address the resulting funding gap.
It is an underwriting framework covering recurring operating expenses and appropriate reserve funding, less sustainable non-assessment income. Oceana’s actual stabilized dues cannot be calculated from advertised listing fees alone.
Advertised monthly fees have ranged from $2,553 to $18,020 across listings. These are dated, unit-specific snapshots rather than current association-certified charges.
No. That figure was the median monthly-equivalent fee in a September 7, 2026 sample of 14 for-sale units disclosing charges, not a building-wide assessment.
No. Differences between units do not establish changes over time or the withdrawal of subsidies; verify each unit’s allocation, assessment history and effective dates.
Advertised inclusions encompass management, cable TV, hot water, parking, pest control, pools, sewer and security. Buyers should confirm the applicable scope and any separate obligations.
Request the adopted budget, financial statements, reserve study and any assessment resolution, together with current unit-specific charges. If sponsor support is identified, request its written terms and expiration conditions.
Oceana’s association portal provides instructions for estoppel and condominium questionnaire requests. Listed management contacts are [email protected] and 786-623-4305.
No. Property taxes and other applicable ownership expenses must be evaluated separately, and historical taxes should not be treated as a buyer’s post-purchase estimate.