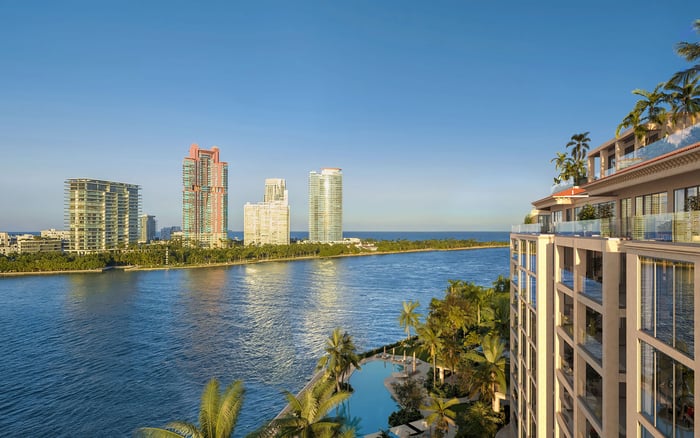
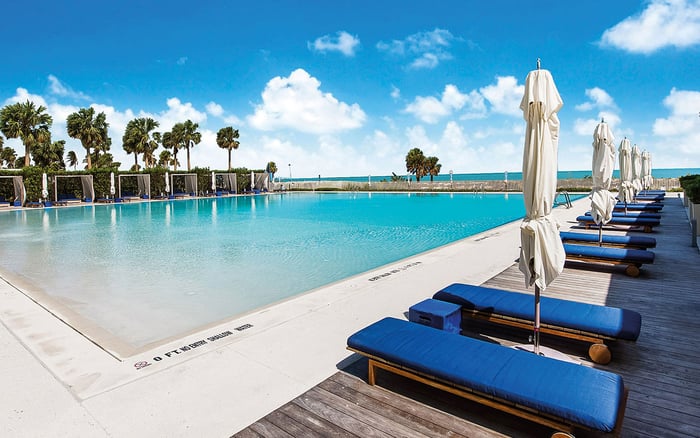
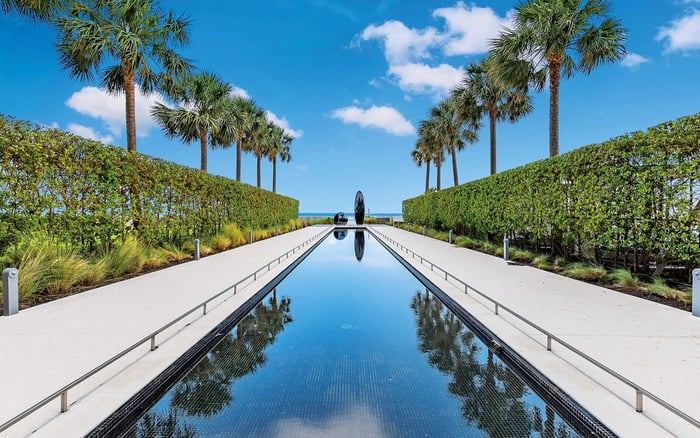
At Oceana Key Biscayne, future resale planning begins with distinguishing buyer approval from a right of first refusal. Current governing documents, clear deadlines and verified interview requirements matter more than assumptions about how an association operates.
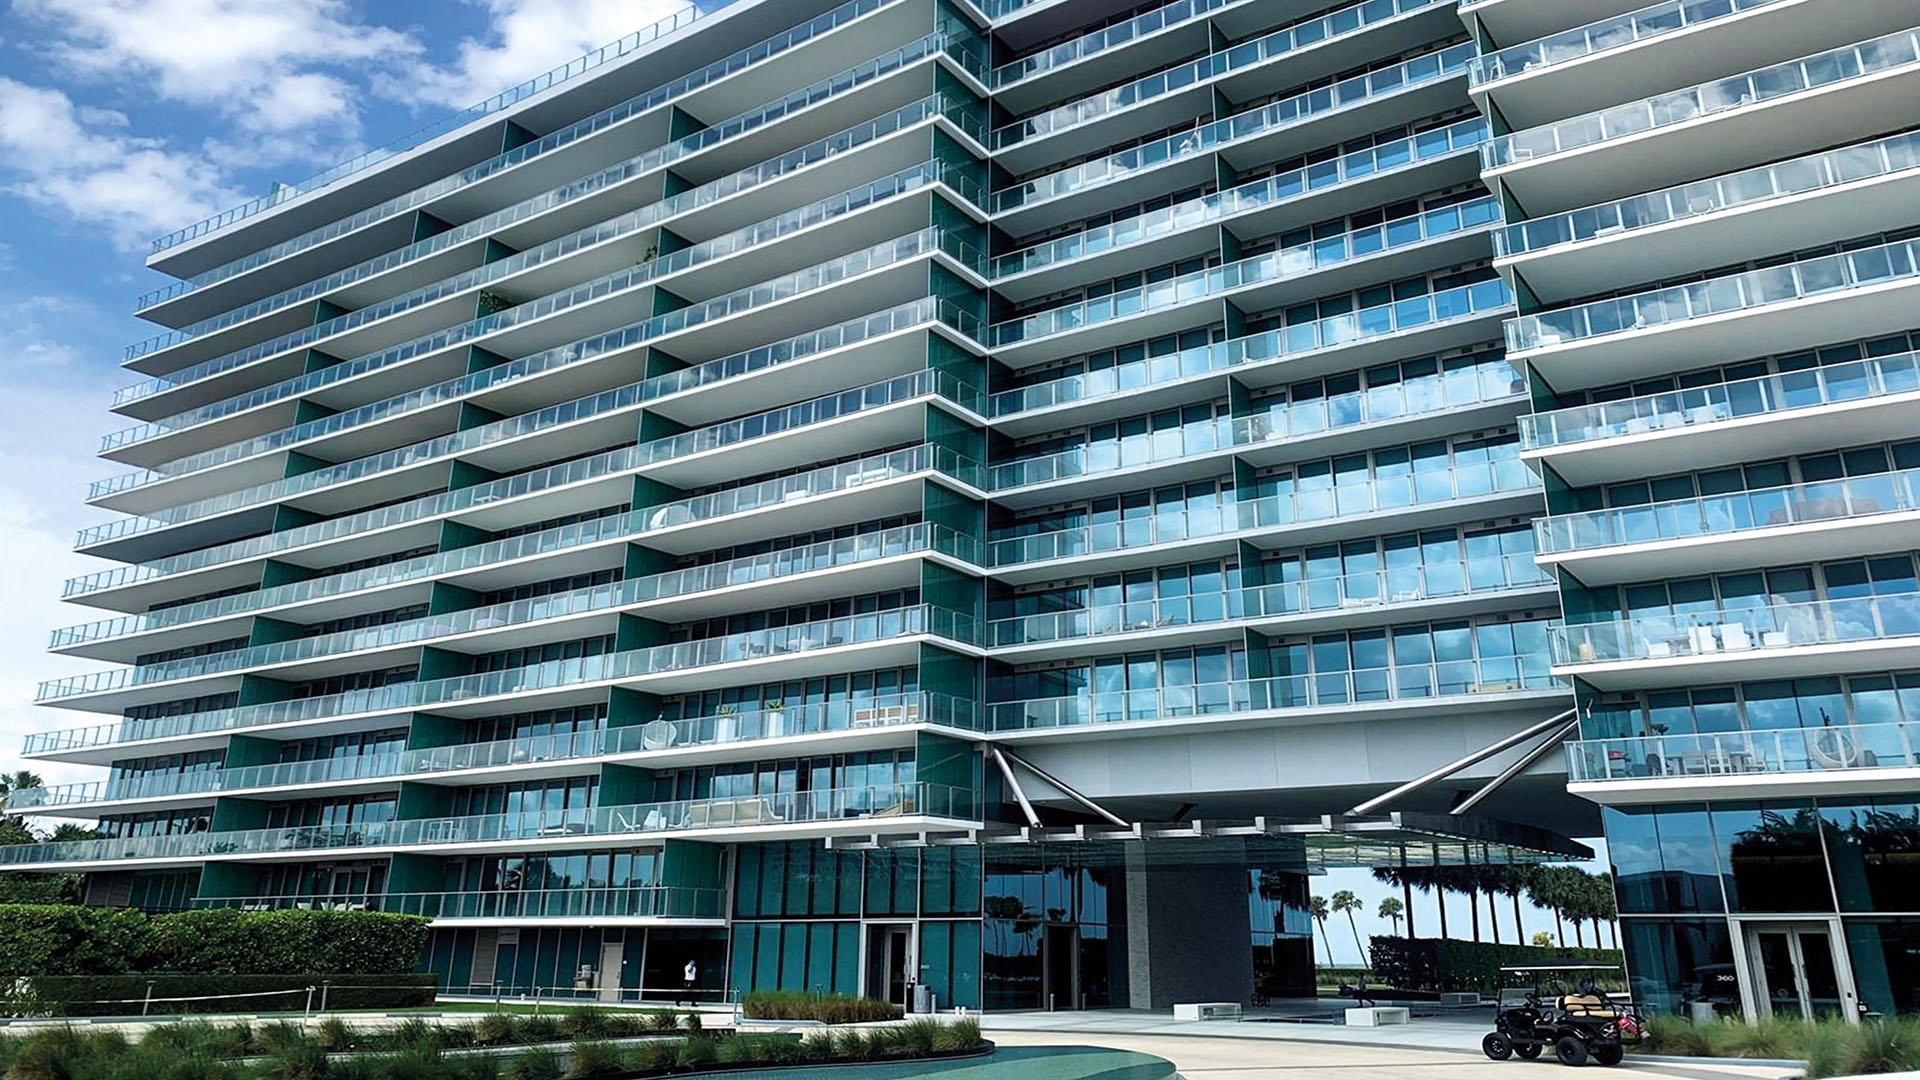
The appeal of Oceana Key Biscayne begins with its beachfront setting and residential scale: the development is marketed with 142 condominium residences and 12 luxury villas, totaling 154 homes. For a buyer considering a substantial acquisition, ownership also carries a less visible consideration: how the residence can eventually be sold.
A right of first refusal, often abbreviated ROFR, and a resale interview can affect that process, but they are not interchangeable. Neither should be presumed to apply at Oceana without a review of the current governing documents and resale requirements. The question is not whether association oversight is inherently undesirable, but whether the applicable procedure gives buyer and seller a clear, workable path from contract to closing.
For future liquidity, procedural clarity matters alongside the residence itself.
A January 2025 purchase of a $15 million Oceana penthouse involved a Delaware LLC affiliated with Juan Ball. An association approval letter attached to the deed documented formal approval of that transaction.
That evidence is meaningful but narrow. It does not establish that the purchase required an interview, that a ROFR was waived, or that the association holds an operative purchase right today. Nor does it establish how frequently buyers acquire through entities or whether different buyer categories face different procedures.
The distinction matters when evaluating Key Biscayne ownership. A completed transaction with an approval letter demonstrates an approval step in that transaction-not the full scope of the association's transfer restrictions. Buyers should ask counsel to identify the provisions governing their proposed acquisition and eventual resale rather than infer them from another owner's closing.
A ROFR gives its holder the contractual opportunity to match a third party's purchase terms. It is neither simple permission to reject a purchaser nor an invitation to negotiate an unrelated acquisition on different terms.
Under a typical condominium structure, the seller submits an executed purchase contract to the association, triggering the exercise period defined in the governing documents. Those provisions generally identify who holds the right, what notice constitutes an exercise, and when that notice must be delivered. They also typically set a deadline for the holder or its designee to complete the purchase.
If the right is validly exercised, the original buyer's acquisition cannot proceed as planned because the holder or designee purchases instead. For the seller, this may redirect the transaction rather than eliminate the sale. For the outside buyer, the question shifts from whether the closing is on schedule to whether that buyer will acquire the residence at all.
Price is only part of the analysis. Because the right concerns matching purchase terms, counsel should examine the full contract, including timing and conditions. Under typical provisions, failure to exercise or complete the purchase within the required deadlines allows the seller to proceed with the outside purchaser, subject to the governing language.
Florida condominium approval procedures may include an application, credit and background checks, an interview and an application fee. These are general possibilities, not established Oceana requirements.
If an interview applies, its practical significance depends on the written procedure and how it is administered. Buyers should confirm who must participate, whether attendance is remote or in person, how appointments are arranged, and whether an entity purchaser must designate particular individuals. These are questions to resolve, not assumptions about Oceana's current practice.
The same discipline applies to a comparison with Apogee South Beach. A buyer considering both properties should request each association's current transfer requirements independently; an approval process at one building says nothing about the other's rules.
Do not automatically add an approval period to a ROFR period as though they must run consecutively. Their relationship depends on the applicable documents and submission requirements. A transaction calendar should reflect verified triggers and deadlines, not a generic allowance borrowed from another condominium.
A future seller's strongest preparation is to understand transfer procedures before committing to a closing date. For a buyer today, that means evaluating the resale process as part of acquisition diligence.
Start with the current declaration, amendments and resale package. Ask counsel to distinguish any purchase right from any approval authority, then confirm the following points in writing:
Holder and authority: Who may exercise a ROFR, and does doing so require owner approval? A board's interest in a purchase does not necessarily establish authority to proceed.
Submission and notice: What must be delivered, to whom, and what event starts each review period?
Exercise and completion: What are the separate deadlines for exercising a purchase right and completing the resulting acquisition?
Waiver and approval: What documentation confirms that the outside buyer may proceed, and how is it obtained?
Interview logistics: If an interview is required, who attends and how does scheduling fit within the transaction calendar?
Written provisions are only part of the assessment. Request recent approval turnaround times and any ROFR exercise history. Neither should be inferred from the existence of a clause or a single approved purchase. Historical practice can inform planning, but it should not replace the governing language.
A buyer also considering Oceana Bal Harbour should prepare a separate, document-based assessment for that property. Similar names are no basis for assuming identical association powers, interview practices or transfer timelines.
For each potential acquisition, ask the same practical question: what must happen between a signed contract and an authorized closing? A clear answer allows the buyer to assess scheduling flexibility and the seller to set expectations before accepting an offer.
This is a conditional liquidity analysis-not a claim that Oceana trades at a discount, attracts fewer buyers or requires a longer marketing period because of association provisions. Those outcomes should not be inferred from approval requirements alone. A documented, consistently administered process may be easier to plan around than one whose requirements remain unresolved until late in the transaction.
For an Oceana buyer, the objective is proportionate diligence, not suspicion of association governance. Confirm whether a ROFR exists, whether an interview is mandatory, and how any applicable requirements interact. Then have Florida condominium counsel align the contract calendar and closing documentation with those findings.
The residence may satisfy every lifestyle priority while still requiring careful transfer planning. Understanding that distinction before acquisition helps turn future resale from an assumption into a process the owner can prepare for.
For a discreet perspective on South Florida ownership and resale planning, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAn operative ROFR should not be assumed. Buyers should have counsel review the current declaration and amendments to establish whether one applies.
A mandatory interview is not established here. Confirm any interview obligation and its format through the current governing documents and resale package.
The $15 million purchase included an association approval letter attached to the deed. That establishes formal approval in that transaction, not an interview requirement or a ROFR waiver.
A ROFR allows its holder to match a third party's purchase terms and purchase instead. Buyer approval is a separate transfer-review mechanism.
Under a typical structure, submission of an executed purchase contract starts the document-defined period. The governing provisions determine the actual trigger and delivery requirements.
The holder or its designee purchases instead of the original buyer, subject to the governing terms. This redirects the seller's transaction and prevents the original buyer's acquisition from proceeding as planned.
Not necessarily. Their timing and relationship depend on the governing documents and submission requirements.
No. Some associations need owner approval, so counsel should confirm exercise authority rather than rely on the board's interest in acquiring a unit.
No price discount, smaller buyer pool or longer marketing period should be inferred from approval requirements alone. Their potential relevance here is closing predictability if they apply.
Review the current governing documents and resale package for approval requirements, any ROFR, deadlines and waiver procedures. Also request recent approval turnaround times and any exercise history.