For Silicon Valley buyers establishing a permanent home in Sunny Isles Beach, the essential planning questions extend beyond closing: January 1 eligibility, March 1 filing, any qualifying Florida portability benefit, and the buyer’s reassessed property-tax basis.
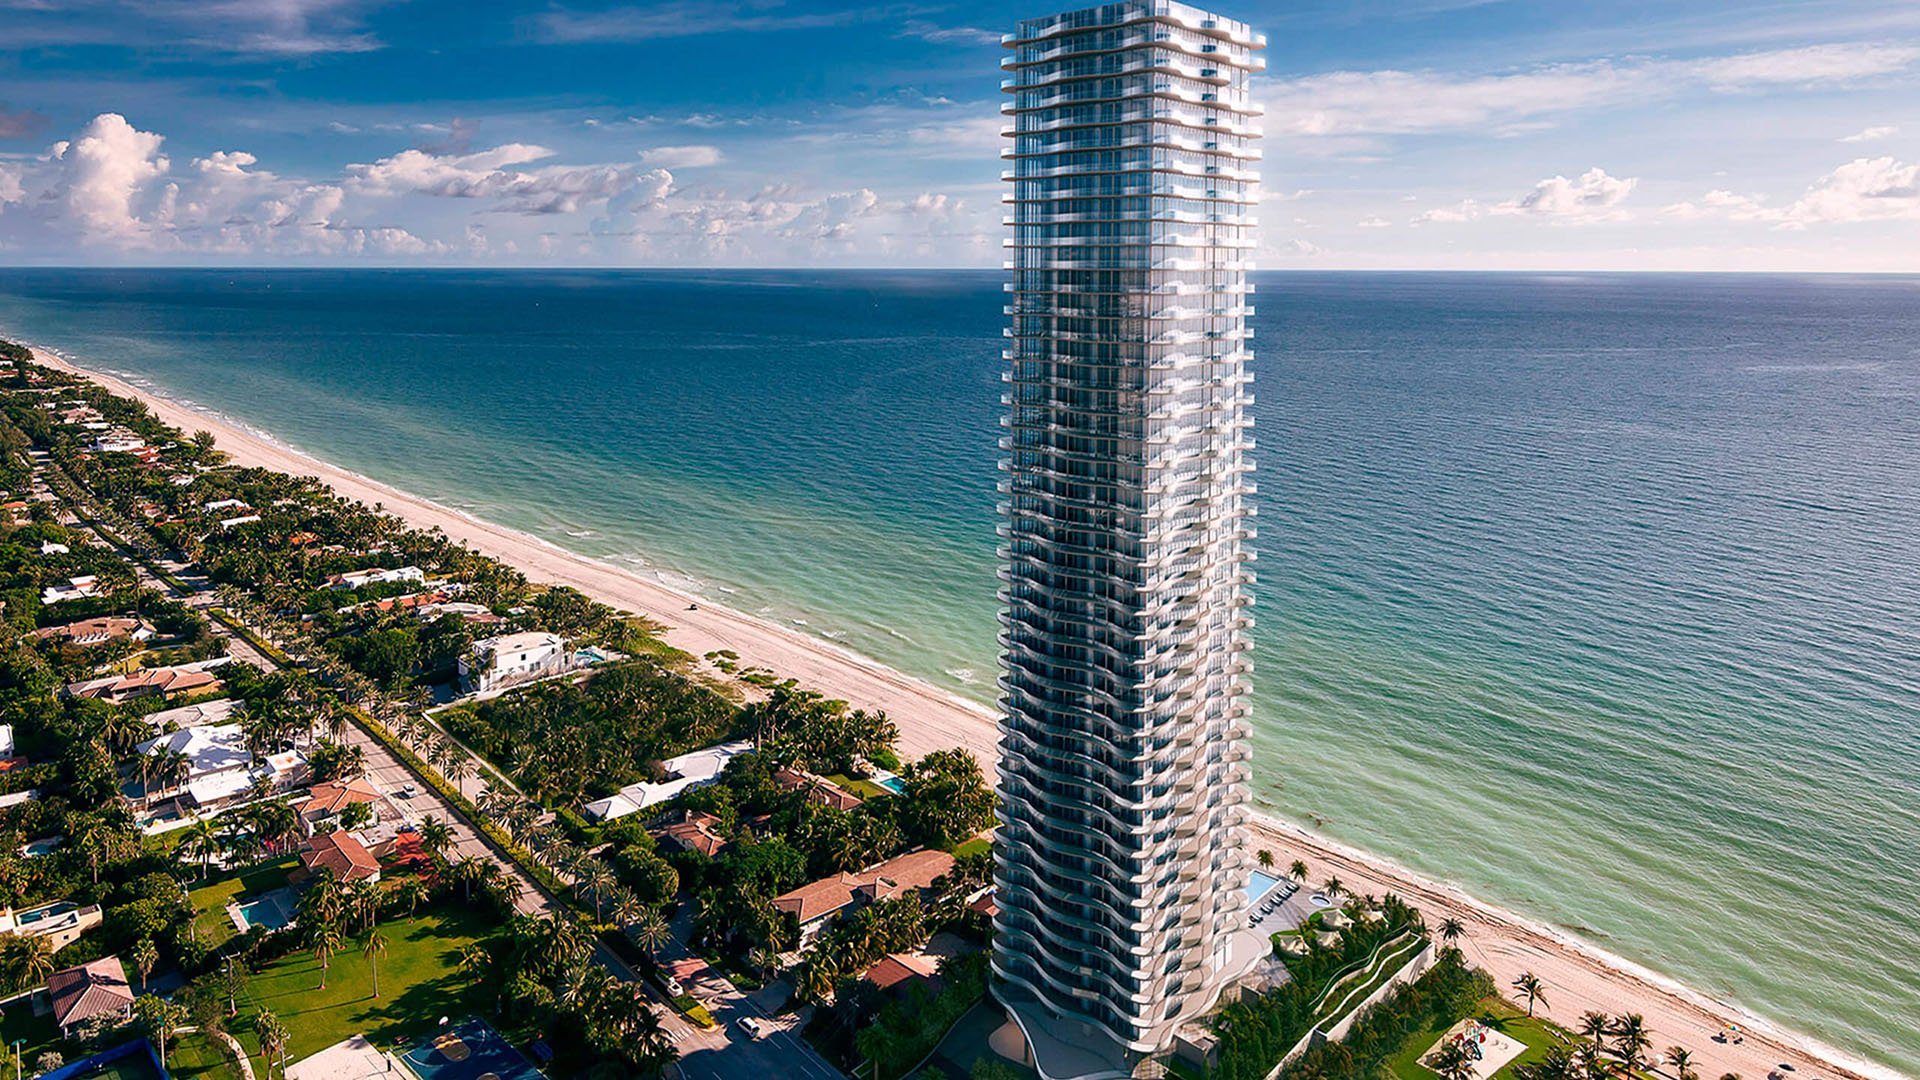
For a Silicon Valley buyer, choosing a Sunny Isles Beach residence can feel like the defining moment of a Florida move. The more consequential question, however, is whether the home supports that relocation on the calendar governing homestead eligibility and property-tax treatment. A purchase, however significant, does not by itself establish a permanent residence.
When considering Jade Signature Sunny Isles Beach, the ownership conversation should extend beyond the residence itself: when the buyer will own and permanently occupy the property, whether an eligible prior Florida homestead benefit exists, and how the assessment may change after acquisition.
Three concepts must remain distinct. Florida domicile concerns the owner’s legal home. Homestead concerns the property’s exemption eligibility. Save Our Homes portability concerns the transfer of an eligible assessment benefit from another Florida homestead. None is shorthand for the others.
To claim homestead for a particular tax year, the buyer must meet the ownership and permanent-residence requirements as of January 1. Florida must be the owner’s legal domicile, and the property must be the permanent residence-not simply a seasonal destination.
The intended eligibility year therefore belongs in acquisition planning. Before committing to a closing schedule, align the proposed ownership date with the actual move and the ability to establish permanent residence. A closing before year-end is not sufficient if the remaining eligibility requirements are unmet on January 1.
For a buyer evaluating Armani Casa Sunny Isles Beach, the practical question is not merely whether the transaction can close on time, but whether the selected residence can support the intended permanent move on time. Resolve that distinction before purchase assumptions become a tax budget.
The statutory homestead application deadline is March 1, moving to the next business day when March 1 falls on a weekend. Filing follows eligibility; it does not replace it. A timely application cannot substitute for the ownership and permanent-residence conditions that had to exist on January 1.
A Silicon Valley residence does not generate a Florida Save Our Homes portability benefit. Portability transfers an eligible accumulated assessment difference between Florida homesteads. It does not import a California assessment history or convert a previous property-tax bill into a Florida credit.
For someone establishing a first Florida homestead without a qualifying prior Florida homestead, the purchase analysis should not assume an incoming portability benefit. A buyer who previously maintained a qualifying Florida homestead may be positioned differently, but that history requires its own review.
The lookback is precise: eligibility requires a qualifying prior Florida homestead exemption as of January 1 in one of the three immediately preceding years. It is not simply a test of whether a former home sold within the preceding 36 months. Organize the review around qualifying tax years, not elapsed months since a sale.
Eligible owners may transfer up to $500,000 of accumulated Save Our Homes assessment difference. That figure is neither a cash payment nor $500,000 in tax savings. When the new homestead’s just value is lower than the former homestead’s just value, the transferable assessment benefit is reduced proportionally.
Portability also requires a separate application, generally using Form DR-501T with the new homestead application. Its standard deadline is March 1 of the year for which the benefit is requested. Homestead approval alone should not be mistaken for a completed portability claim.
An existing tax bill provides context, but it should not become the buyer’s forward budget without further analysis. The seller’s protected assessment does not simply pass to the purchaser.
After a change in ownership and establishment of a new homestead, the property generally resets to just value on January 1 of the following year, subject to any eligible Save Our Homes benefit the buyer transfers. Reassessment and portability are separate components of the calculation, not interchangeable protections.
For a residence under consideration at Turnberry Ocean Club Sunny Isles, request an individualized review of the expected post-acquisition assessment and any qualifying transferable benefit. A seller’s historical tax burden cannot answer both questions.
The distinction matters at any purchase price: an assessment difference is not a dollar-for-dollar reduction in taxes. Without the particular residence’s assessment information and the buyer’s verified portability position, a precise property-tax estimate would create false confidence. Treat a buyer-specific projection as a due-diligence item, not a marketing assumption.
The strongest relocation purchase is a residence the buyer genuinely intends to use as a permanent home. Consider whether it suits ordinary routines, not just a winter visit: working from home, accommodating family, and living comfortably throughout the year. These are practical selection questions, not a substitute for legal eligibility.
A buyer considering Regalia Sunny Isles Beach should apply the same discipline. Project identity does not resolve domicile, homestead timing, or portability. The relevant facts concern the owner, the selected property, and the actual transition to permanent residence.
Keep California residency termination on a separate advisory track. Florida homestead approval alone should not be treated as resolving California income-tax residency. Coordinate the departure and arrival with qualified legal and tax advisers rather than assuming a Florida exemption answers every interstate question.
Sunny Isles Beach applications and supporting documentation belong with the Miami-Dade County property appraiser. Online applications are available for both homestead exemption and the transfer of a homestead assessment difference.
Before filing, confirm the intended eligibility year, the evidence needed for ownership and permanent residence, and whether a prior Florida homestead supports portability. If portability is relevant, establish the qualifying prior January 1 status and prepare the separate transfer application alongside the new homestead application.
Approval does not end the owner’s responsibility. Eligibility must remain accurate, and improperly retaining an exemption can lead to back taxes, interest, and penalties. Changes affecting qualification deserve prompt attention.
For a well-planned move, the sequence is straightforward: select a residence that supports permanent use, satisfy January 1 eligibility, file by the applicable deadline, and budget for the buyer’s own reassessment. The address and the tax plan should reinforce each other without being mistaken for the same thing.
Explore Sunny Isles Beach residences with MILLION to align your property search with your permanent-home priorities.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The property must be the owner’s permanent residence, Florida must be the owner’s legal domicile, and the ownership and permanent-residence requirements must be met as of January 1.
January 1 is the eligibility date for the tax year in which homestead is claimed. Closing before that date alone is insufficient if the permanent-residence requirements are not also satisfied.
The statutory deadline is March 1, moving to the next business day when March 1 falls on a weekend.
Applications and supporting documentation go to the Miami-Dade County property appraiser. Online applications are available for homestead and portability.
No. Save Our Homes portability transfers an eligible assessment benefit between Florida homesteads; a California residence does not generate that benefit.
The owner must have a qualifying prior Florida homestead exemption as of January 1 in one of the three immediately preceding years. This is not simply a 36-month period measured from a sale.
No. It represents the maximum eligible accumulated assessment difference that may be transferred, not cash or tax savings. A move to a homestead with a lower just value reduces the transferable benefit proportionally.
No. Portability requires a separate application, generally Form DR-501T submitted with the new homestead application, with a standard March 1 deadline for the requested benefit year.
The buyer should not assume so. After an ownership change and establishment of a new homestead, the property generally resets to just value on January 1 of the following year, subject to any eligible transferred benefit.
Florida homestead approval alone should not be treated as resolving California income-tax residency. The departure from California requires a separate review with qualified advisers.