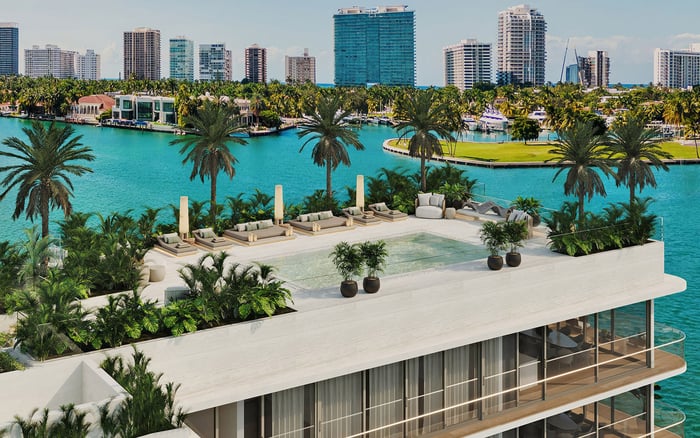
For a Madrid household establishing its principal home in Bay Harbor Islands, the residence and its ownership structure must work together. Personal title, trust ownership, and entity ownership require distinct homestead analysis, while genuine occupancy remains essential to Florida domicile.
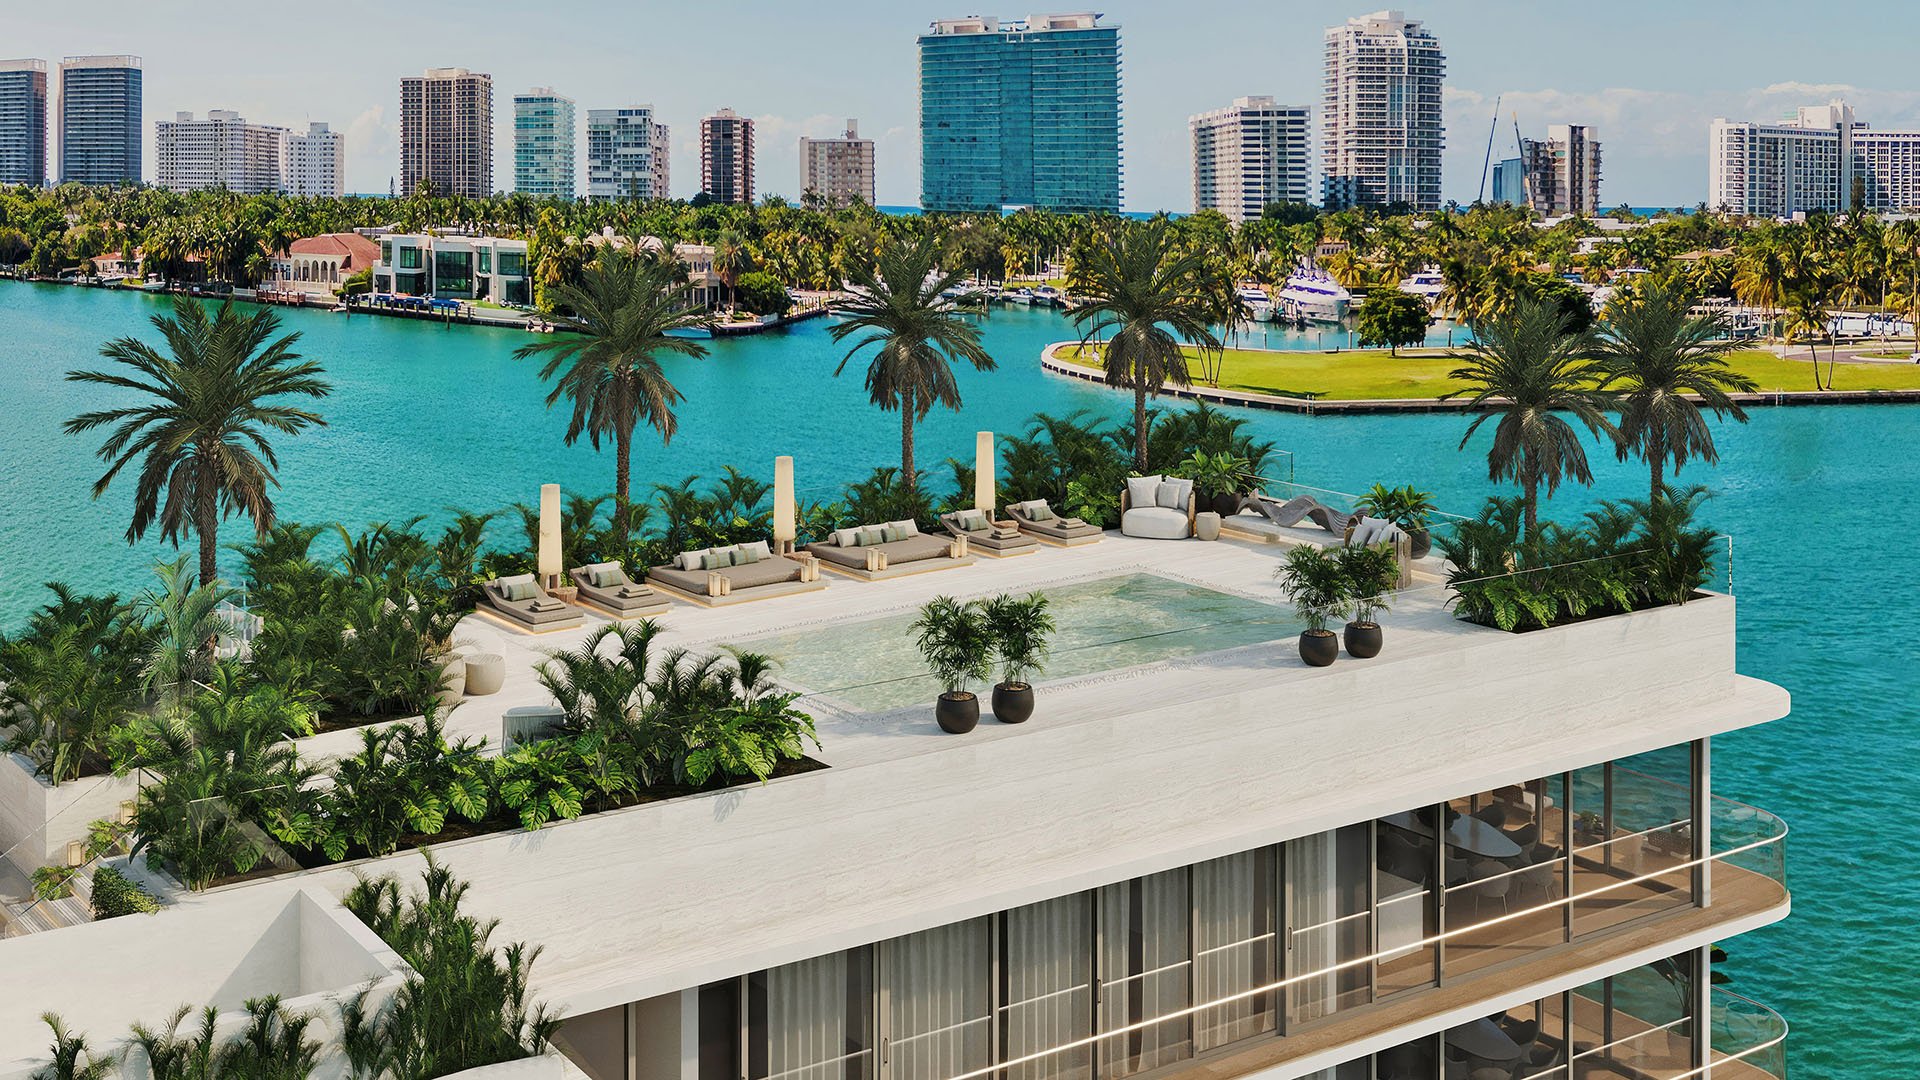
For a household leaving Madrid, a Bay Harbor Islands acquisition should begin with a question more consequential than the view: will this residence genuinely become the permanent home? Florida domicile depends on actual residence and the intention to remain-not simply a deed, an investment allocation, or an address on correspondence.
The ownership decision belongs alongside that question. Personal title, trust ownership, and entity ownership are not interchangeable for homestead planning. The goal is not a residence that somehow guarantees every ownership option, but a purchase in which actual use, qualifying ownership, and estate documents support the intended outcome.
When considering Alana Bay Harbor Islands, frame the search around ordinary weeks rather than occasional visits. Ask whether the home suits the household's routines and anticipated time in Florida. No project name, amenity, or purchase price can establish domicile on the buyer's behalf.
Spain's day-count test can establish tax residence when an individual spends more than 183 days there during a calendar year. Yet days alone do not settle the departure: Spain also considers whether the main base or center of economic interests remains there. Spending fewer than 183 days in Spain does not automatically establish nonresidence.
Florida asks a different question: whether physical presence accompanies a genuine intention to make the state the permanent home. There is no universal Florida 183-day domicile requirement mirroring the Spanish test. Maintaining another residence, whether in Madrid or Miami Beach, need not defeat domicile, provided the claimed Florida home remains predominant and principal.
Keep four analyses distinct: Spanish tax residence, Florida domicile, homestead property-tax eligibility, and homestead creditor protection. Florida has no personal income tax, but that does not prevent a former jurisdiction from continuing to claim tax residence. Spanish exit-tax exposure, treaty issues, immigration status, and U.S. reporting obligations require separate professional review; this framework does not resolve them.
Holding the residence personally and actually occupying it avoids the additional trust- or entity-ownership questions that can complicate homestead analysis. Personal title is therefore a useful starting point for discussion, not an automatic recommendation for every international household.
Its principal advantage here is simplicity: the resident is also the named owner. Property-tax benefits and creditor protection nevertheless require separate eligibility reviews. A personally held condominium used only occasionally does not become a permanent home simply because the deed is uncomplicated.
For a buyer evaluating Bay Harbor Towers, the practical sequence is to establish the intended residential use, then have counsel assess title against the family's circumstances. Personal ownership should not be labeled inherently weakest for asset protection, just as a more elaborate structure should not be presumed superior. Complexity is not itself a benefit.
Certain trust arrangements can be compatible with Florida homestead, but the word “trust” does not establish eligibility. The terms must support the resident's qualifying ownership or beneficial rights. When a revocable trust is proposed, occupancy rights, beneficiary provisions, and Florida homestead compatibility deserve coordinated review.
The question is not merely whether a trust can acquire the home. It is whether this particular trust, for this particular resident, supports the intended homestead treatment and estate plan. Do not assume that revocability alone resolves those questions or that a revocable trust automatically provides creditor protection.
If La Maré Bay Harbor Islands is under consideration, review the contemplated trust before settling the vesting instructions. Wills and trusts should also be reviewed for Florida-law compatibility and should reflect Florida residence when supported by the facts. The deed and estate plan should be consistent with each other, without attempting to substitute for actual occupancy.
Corporate or LLC title can jeopardize benefits associated with a natural person's homestead. It should not be treated as equivalent to personal ownership or selected on the assumption that homestead treatment will follow automatically.
Ask counsel to analyze property-tax eligibility and creditor protection separately before choosing entity title. Do not presume a “transparent LLC” shortcut to eligibility. A household accustomed to holding investment property through entities should resist carrying that habit into a principal-residence purchase without examining the consequences.
The essential tradeoff is this: an ownership structure must be evaluated against the intended use of the home, not chosen independently of it. Entity title does not replace occupancy evidence; equally, living in the property does not by itself resolve the homestead questions created by entity ownership.
A persuasive domicile position aligns records with lived reality. Travel logs, airline records, calendars, and location records can help substantiate time spent at the Florida home. The aim is accurate documentation, not a paper trail suggesting a relocation that has not occurred.
A Florida driver's license, vehicle registration, and, where legally eligible, voter registration can support the move. Federal tax returns, banking relationships, and financial correspondence should use the Florida address when it genuinely represents the principal residence. Healthcare providers, clubs, charitable connections, and family activities can further demonstrate that daily life has relocated.
When considering The Well Bay Harbor Islands, assess how the residence would fit those routines rather than treating the purchase itself as evidence of a completed transition. Corresponding ties to the former primary jurisdiction should also be reviewed and weakened where they conflict with the genuine move.
A Declaration of Domicile can document intent and can be recorded with the circuit court clerk in the county where the person resides. But a declaration, like a mailbox or a purchase contract, cannot substitute for establishing a real Florida home.
Before finalizing the acquisition, have Florida counsel and cross-border tax advisers distinguish what each decision accomplishes. Confirm the proposed owner, review any trust rights, assess each homestead dimension, and align estate documents with the intended residence. Separately, examine whether the Spanish departure is supported by both presence and economic-interest facts.
Judge the residence by a demanding but practical standard: can it comfortably sustain the life the household intends to establish? This is general planning context, not individualized legal or tax advice. The strongest approach is not the most elaborate deed, but a coherent relationship between ownership, documented presence, and a genuine permanent home.
For a residence search centered on the way you intend to live, explore Bay Harbor Islands with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Florida domicile requires actual residence together with a genuine intention to make Florida the permanent home.
Not automatically. Spain also considers whether the main base or center of economic interests remains there.
No universal 183-day domicile requirement applies in this framework. Actual presence and the intention to make Florida the permanent home must be considered together.
Another home does not necessarily defeat Florida domicile, but the Florida abode must remain predominant and principal. Spanish tax residence still requires separate analysis.
Personal title avoids the additional trust- or entity-ownership questions relevant to homestead planning. It does not automatically establish domicile or guarantee homestead eligibility.
Certain arrangements may qualify, depending on the trust terms and the resident's qualifying ownership or beneficial rights. Occupancy rights and beneficiary provisions require review.
No such protection should be assumed merely because the residence is held in a revocable trust. Homestead compatibility and creditor protection require specific review.
Yes. Corporate or LLC ownership can jeopardize benefits associated with a natural person's homestead and should not be presumed equivalent to personal title.
Travel logs, airline records, calendars, and location records can substantiate presence. Consistent credentials, financial correspondence, and personal relationships can further support the relocation.
No. Recording a declaration documents intent, but it must align with actual residence and the household's administrative, financial, and personal ties.