For an executive purchasing a South Florida primary residence, contract review should connect deed vesting, homestead rights, insurance questions, succession planning, and signing authority before closing arrangements are finalized.
An executive’s South Florida primary residence deserves the same disciplined review as a consequential business acquisition, but with a different center of gravity: family rights. The purchase contract, proposed deed, estate plan, insurance arrangements, and signing instructions should be reviewed together, not treated as separate administrative tasks.
Waterfront appeal and architectural distinction may guide the search. They should not determine the ownership structure. Before approving closing documents, ask counsel to connect four questions: who will own the residence, whose rights affect it, how insurance will address the proposed ownership, and who can legally sign.
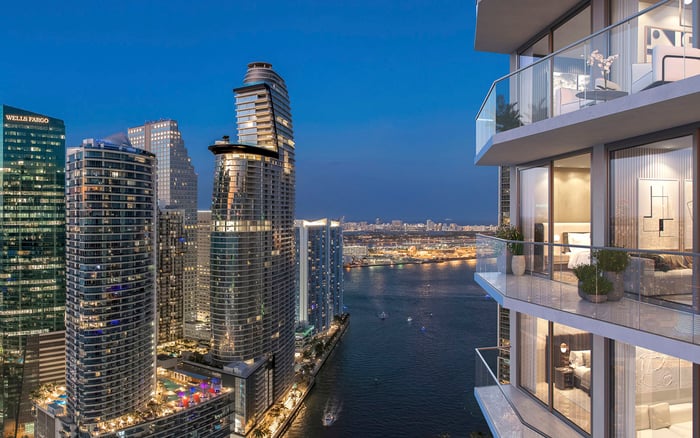
For a buyer considering The Residences at 1428 Brickell, the Brickell address is the lifestyle decision. Vesting and signing authority are separate legal decisions, deserving their own timetable.
Deed vesting identifies how ownership is held. For a proposed Florida homestead, that decision cannot be separated from marital status, descendants, and intended succession. Homestead conveyance and inheritance restrictions require their own review. A preferred ownership arrangement should not be approved simply because it resembles the buyer’s broader asset plan.
Ask counsel to evaluate the intended primary-residence use before settling the deed language. If trust ownership is contemplated, request a coordinated review of the proposed transfer and estate documents. Conveyances of land interests in trust generally require a deed signed and delivered before two subscribing witnesses by the grantor or a lawfully authorized representative.
Contract review should also address flexibility. Counsel may recommend negotiating language that accommodates an approved vesting arrangement and advance delivery of draft documents. These are negotiation recommendations, not automatic statutory entitlements. Assess any proposed change against the actual agreement rather than assuming it will be available at closing.
A married owner generally needs spousal joinder to convey or mortgage homestead. That requirement matters even when the executive views the residence as an individually managed asset. Ask counsel who must participate in each contemplated deed or mortgage; do not infer the answer solely from whose name appears as owner.
A distinct rule applies to a direct conveyance from one spouse to the other: real estate, including homestead, can be transferred without the grantee spouse executing that conveyance. This is not a general exception allowing spouses to bypass joinder in other transactions.
For a Coconut Grove purchase such as Four Seasons Residences Coconut Grove, identify the necessary participants before coordinating travel and signatures. Personal convenience neither establishes legal authority nor eliminates a required spouse’s involvement.
Investment priorities should not obscure family rights. A buyer may have clear intentions about who ultimately receives the residence, but those intentions still need to be tested against Florida’s homestead descent rules.
When homestead is not validly devised and the deceased owner leaves a spouse and descendants, the spouse generally receives a life estate and the descendants receive the remainder, subject to statutory qualifications. In those circumstances, the surviving spouse may instead elect an undivided one-half interest, with the other half passing to the descendants.
These are materially different ownership outcomes. Counsel should explain how the proposed vesting and estate plan interact with the buyer’s family circumstances. A general statement of beneficiary preference is no substitute for legal analysis.
Florida also provides statutory deed language for waiving spousal homestead rights that would otherwise prevent a spouse from devising the property to someone else. That waiver has limits: it does not waive homestead creditor protection or the requirement for spousal joinder in a sale, mortgage, gift, or deed. Inheritance consent and transaction participation remain separate questions.
Treat insurance named-insured questions as a dedicated adviser review, not an automatic consequence of approving the deed. Ask the insurance adviser to examine the proposed ownership arrangement and explain how it should be addressed in the actual policy documents. Clarify any proposed named-insured or additional-insured treatment rather than treating those descriptions as interchangeable.
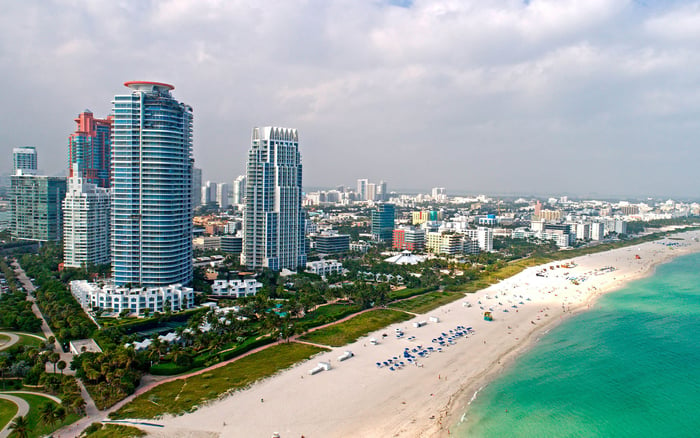
For a Miami Beach residence under consideration at The Perigon Miami Beach, this is an individualized review recommendation, not a statement about the project’s insurance. Ask the adviser to address intended occupancy and any relevant flood or windstorm questions. Do not assume the answers from the address or ownership proposal.
If insurance review needs to influence the purchase commitment, discuss proposed contract protection with counsel before signing. Any requested contingency, document-delivery obligation, or review period depends on negotiation and the agreement’s terms; none should be assumed to exist.
An executive’s assistant, relative, or adviser should not sign merely because the buyer has given informal permission. Establish legally sufficient authority for the representative’s intended role, then have the closing team review it before scheduling execution.
Do not assume a general power of attorney authorizes every closing act. Its effectiveness and granted powers require review. Powers involving survivorship rights and beneficiary designations receive specific statutory treatment, making express-authority review particularly important when an agent would change those rights.
Homestead conveyance or mortgage authority, including required spousal joinder, may be exercised through an attorney-in-fact when statutory requirements are satisfied. A power of attorney used for a homestead deed or mortgage must be executed with deed formalities. Ask counsel to confirm both the document’s execution and its authority for the intended transaction.
For a West Palm Beach purchase at Alba West Palm Beach, advance authority review is a sensible planning step if someone other than the buyer expects to sign. It does not replace review of the actual instruments.
Before approving the final package, request a coordinated review of the proposed deed, estate-planning implications, insurance adviser’s responses, required spousal participation, and representative authority. Ask counsel to distinguish unresolved legal questions from negotiated contract requests and administrative arrangements.
The objective is not complexity for its own sake. It is a residence whose ownership, family protections, and execution arrangements reflect deliberate choices. This is transaction-planning guidance, not individualized legal advice; the buyer’s circumstances and documents require counsel’s assessment.
For a discreet perspective on your South Florida residence search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationOwnership structure and family circumstances affect Florida homestead succession rights. Counsel should review the proposed vesting alongside the buyer’s intended use and estate plan.
Yes, a married owner generally needs spousal joinder to mortgage or convey homestead. Counsel should identify the required participants for the specific transaction.
A direct conveyance from one spouse to the other can transfer real estate, including homestead, without the grantee spouse executing the conveyance. This is distinct from the general spousal-joinder rules.
When the deceased owner leaves a spouse and descendants, the spouse generally receives a life estate and the descendants receive the remainder, subject to statutory qualifications.
In those circumstances, the surviving spouse may elect an undivided one-half interest instead. The remaining half passes to the descendants.
No; the statutory waiver addressing certain inheritance rights does not waive homestead creditor protection or required spousal joinder in a sale, mortgage, gift, or deed.
Ask the insurance adviser to review the proposed ownership and explain its treatment in the actual policy documents. Do not assume approval of the deed resolves insurance questions.
Informal permission should not be treated as sufficient signing authority. The closing team should review legally sufficient authority for the representative’s intended role.
Not necessarily; its effectiveness and granted powers require review. A power of attorney used for a homestead deed or mortgage must also be executed with deed formalities.
They should not be assumed to exist. Proposed flexibility, review periods, and contingencies are negotiation recommendations that counsel should evaluate against the actual agreement.