A trustee’s preconstruction review should distinguish contract price from supported market value, examine terrace and upgrade assumptions, and define any negotiated appraisal-gap exposure before signing.
A beautifully conceived South Florida residence still calls for disciplined contract review. For a trustee signing a preconstruction purchase, the central question is not simply whether the home suits the intended lifestyle. It is whether the commitment remains acceptable if the eventual appraisal does not support the agreed price, terrace premium, or bespoke finish package.
The review should separate three matters: authority to sign, evidence supporting value, and the contractual allocation of a valuation shortfall. They are related, but not interchangeable. An appraisal does not establish trustee authority, and a negotiated purchase price does not guarantee a matching valuation.
Before execution, ask trust counsel to confirm the proposed purchaser designation, signing capacity, and any approvals or documentation appropriate to the trust. Separately, have transaction counsel identify what the purchase agreement actually promises if financing or appraised value falls short. These are review recommendations, not statements of automatic rights under Florida law.
A condominium valuation considers both the residence and the surrounding project. Location within the building, amenities, association assessments, and overall project appeal belong in that analysis. Matching interior square footage alone does not establish a persuasive comparison.
For a trustee considering The Residences at 1428 Brickell, the relevant Brickell question extends beyond price per interior square foot. Which available sales support the proposed valuation, and how are differences in residence location and project characteristics addressed? This is a review framework, not a conclusion about the project’s value or contract terms.
Ask how relevant information will be collected, verified, and analyzed, and which comparable sales support the sales-comparison analysis. Ask the lender what documentation may be submitted for consideration, recognizing that a buyer’s preferred valuation cannot replace an independently supported opinion.
The contract review should also identify the contemplated appraisal timing and valuation basis. Ask how the proposed residence, delivery specifications, and any completion assumptions will be described to the lender and appraiser.
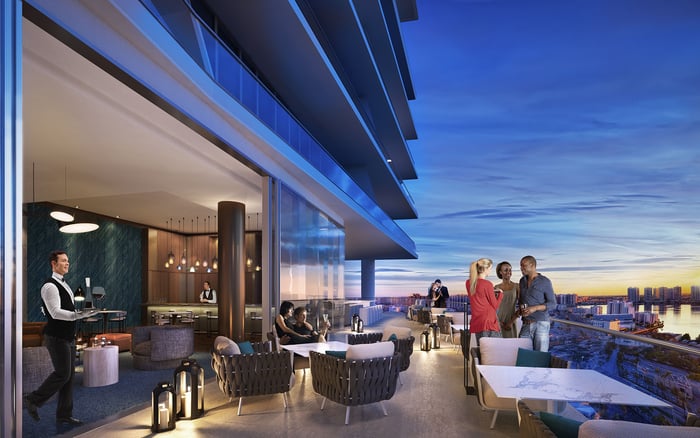
Outdoor space may be central to the purchase decision, but it should not automatically receive the same per-square-foot value as enclosed living area. Comparable-sale evidence and supported adjustments provide a better basis for evaluating a terrace premium than a fixed percentage selected for convenience.
For a Miami Beach residence under consideration at The Perigon Miami Beach, request clear documentation distinguishing interior area from terrace area. Then ask how the available comparisons account for outdoor space. Do not assume that a combined marketing area is the appropriate denominator for a valuation comparison.
Counsel should also examine the documents governing terrace use and maintenance. Ask what the purchase includes, what restrictions apply, and which obligations the purchaser would assume. Those questions require document-specific answers; an appraisal cannot establish them.
The trustee’s review file should explain why the outdoor space matters to the intended use and what market evidence supports its contribution to the price. Lifestyle preference and market value may align, but neither is proof of the other.
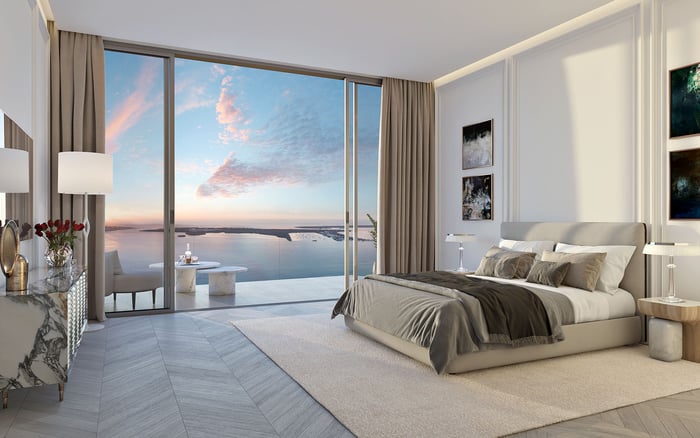
A tailored interior can make a residence personally compelling. The developer’s charge for that work, however, is not evidence that the market will recognize an equal increase in value. Bespoke improvements require market-supported analysis, not a dollar-for-dollar addition of upgrade invoices.
When evaluating Bentley Residences Sunny Isles or another Sunny Isles Beach purchase, distinguish the base residence specification from separately selected improvements. This recommendation does not presume that a particular customization program or upgrade arrangement is available.
Request an itemized scope, pricing, and the proposed treatment of changes or substitutions. Counsel should clarify whether the contract price used in any appraisal-gap provision includes later selections and whether those selections create separate payment obligations.
For the trustee, two figures warrant separate attention: what the trust agrees to spend and what the improvements contribute to supported market value. The review should make any difference explicit rather than conceal it within a single headline price.
An appraisal gap requires a contractual definition. Ask counsel to specify the purchase-price figure, appraisal figure, and trigger used in any proposed provision. The difference between price and appraised value is not necessarily the same as the additional cash required under the lender’s financing terms.
A useful negotiation agenda should address:
Which appraisal controls and whether lender acceptance is required.
Whether upgrades and later price changes enter the calculation.
Whether any additional buyer contribution has an agreed maximum.
What notice, supporting documentation, and response periods apply.
What happens if the shortfall exceeds the negotiated amount.
These are proposed negotiating points, not established buyer entitlements. A refundable deposit, termination option, second appraisal, price adjustment, or capped contribution must not be assumed. Counsel should determine whether the executed documents provide any such protection and how it operates.
Ask the lender to model cash requirements under more than one supported-value scenario, then compare those requirements with the trust’s intended liquidity commitment. Evaluate a proposed cap alongside deposits, separately payable improvements, and other closing obligations so that it does not give a misleading impression of total exposure.
Project-level considerations can affect both value and financing. Ask how special assessments, deferred maintenance, and common-area or amenity concerns will be evaluated. Also ask whether any physical deficiencies affecting safety, soundness, or structural integrity require further review under the intended lender’s requirements.
When considering Villa Miami, apply the same discipline: request project information relevant to the intended financing and ask which review requirements the lender will apply. Do not presume that every mortgage-program standard governs every luxury purchase.
Presale figures also require careful interpretation. Ask whether a quoted figure measures residences under contract, residences already conveyed, or a combination before treating it as evidence of completed closings.
Before signing, assemble a concise record connecting the trust’s proposed commitment to the evidence and negotiated terms. Distinguish interior and terrace areas, base specifications and bespoke selections, supported value and personal preference, and a contractual gap cap and the lender’s cash requirements.
The objective is not to eliminate every uncertainty. It is to identify which uncertainties the trust accepts, which require further documentation, and which should be addressed in the agreement before execution. A carefully negotiated purchase can preserve the intended lifestyle without confusing aspiration with valuation support.
For a discreet perspective on South Florida residences, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Ask trust counsel to confirm signing capacity, purchaser designation, and any appropriate approvals separately from the valuation review.
No. It also considers the condominium project, including amenities, association assessments, and the residence’s location within it.
That equivalence should not be assumed. Terrace value should be evaluated through comparable-sale evidence and supported adjustments.
No. The amount paid for improvements and their market-supported contribution to value are distinct.
Relevant comparisons consider unit location, amenities, and project characteristics, not merely similar interior size.
Proposed terms should identify the controlling appraisal, price calculation, trigger, any contribution cap, notice requirements, and consequences of an excessive shortfall.
It should not be assumed. Counsel should determine whether the executed agreement provides it and what conditions apply.
Not necessarily. Ask the lender to model cash requirements under its financing terms rather than relying solely on the price-to-value difference.
Ask how they will be evaluated in the appraisal and the intended lender’s project review. Request documentation relevant to those reviews before signing.
Not without clarification. Ask whether the figure counts residences under contract, residences already conveyed, or a combination.