For a nonresident buying through a U.S. entity, disciplined contract review connects financing, intended occupancy, rental taxation, and closing documentation without assuming that entity ownership creates deductions.
For a nonresident purchasing a South Florida residence through a U.S. entity, contract review should reach beyond price, deposits, and closing dates. It should connect the named purchaser, the borrowing arrangement, the intended occupancy, and the records needed after closing. Entity ownership alone does not establish that interest or occupancy expenses are deductible.
Before signing, give the attorney and international-tax adviser a coherent account of the transaction: who will own the residence, who will borrow, where the funds will move, and whether the home will serve personal, rental, or mixed purposes. These are practical planning questions, not assurances of a particular tax result.
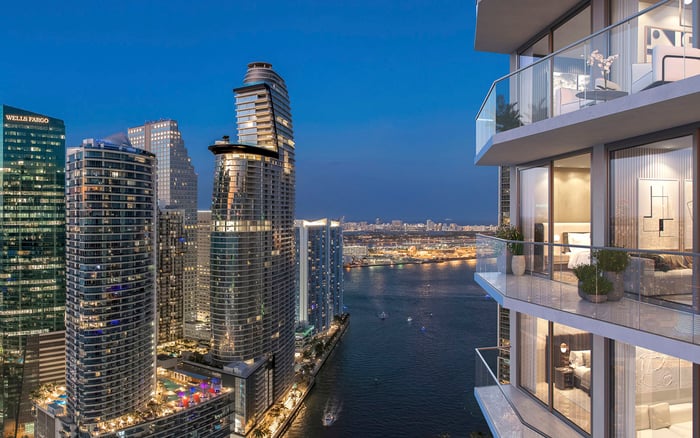
A buyer considering The Residences at 1428 Brickell should bring the same clarity to the ownership plan as to the residence selection. The Brickell address is the lifestyle decision; the entity and financing arrangements require separate analysis.
Federal interest-tracing rules generally allocate debt to the expenditures funded by its proceeds, then allocate the related interest accordingly. The central question is what the borrowed money paid for-not simply which property secures the loan.
A residential mortgage does not automatically become investment debt because an entity holds the residence. If borrowed funds support both rental activity and personal expenditures, the related interest must be allocated between those uses, not assumed wholly deductible. Classification alone does not resolve every deduction limitation.
During contract review, ask the lender and tax adviser to map the expected flow of proceeds before disbursement. Which payments will the loan fund? Will any proceeds pass through an account holding personal cash? How will each expenditure be identified later? A separate account for a particular loan's proceeds is a recommended way to simplify tracing, but the underlying records still matter.
Identify financing points separately. Points associated with rental borrowing generally require different treatment from an immediately deductible ordinary operating expense. The closing statement should support that analysis, not substitute for it.
Debt tracing and property-use allocation answer different questions. The first follows borrowed funds to expenditures. The second distinguishes rental activity from personal occupancy and determines how property expenses should be allocated. A complete purchase file needs both.
Where the applicable mixed-use dwelling rules govern, owner stays, certain family stays, and below-market occupancy can count as personal use. Calling an arrangement a rental does not necessarily establish its tax treatment. Records should distinguish days rented at fair rental value from personal-use days, while the adviser determines how the rules apply to the ownership structure.
For a Miami Beach buyer considering The Perigon Miami Beach, the practical question is whether the intended seasonal retreat also fits the proposed investment plan. This is not a representation about the project's rental permissions; those must be checked independently.
Separate rental and personal expenses rather than treating every ownership cost as an investment expense. Even the properly allocated rental portion may face further deduction limitations. Before closing, agree on who will maintain the occupancy calendar and how family visits, rental agreements, and payments will be documented.
U.S. real-property rents received by a nonresident alien that are not effectively connected income are generally subject to gross withholding, unless an applicable exemption or treaty provision changes the result. Address that possibility before rental receipts begin.
A qualifying nonresident alien holding U.S. real property for income production may elect under IRC §871(d) to treat qualifying real-property income as effectively connected with a U.S. trade or business. The election permits attributable deductions and taxation on a net basis, subject to applicable deduction rules. It generally extends to all qualifying U.S. real-property income held for income production, not just the newly purchased residence.
A valid election brings a continuing Form 1040-NR filing obligation for the election year and subsequent years until revoked. The electing individual should provide Form W-8ECI to the relevant withholding agent in the first election year and when otherwise required.
Do not automatically apply these individual nonresident-alien rules to every U.S. entity purchase. The international-tax adviser should first identify the relevant taxpayer and the entity's tax treatment, then determine the applicable elections, withholding documentation, and filings. The contract purchaser's name alone does not answer those questions.
A useful transaction file connects borrowing documents, bank statements, disbursement records, invoices, and the closing statement. Its purpose is to show how each debt's proceeds were used-not merely that the residence was acquired.
Maintain a separate operating record for rental receipts, expenses, and occupancy. Retain agreements and payment evidence supporting fair-rental-value stays, alongside a calendar recording personal use. Keep points and other financing charges distinguishable for adviser review.
For a Coconut Grove purchaser evaluating Four Seasons Residences Coconut Grove, establish these responsibilities before the first stay or rental receipt. A well-organized closing file is only the beginning; subsequent use must remain documented.
Ask the attorney to review whether the purchaser, financing arrangements, and intended use are consistently reflected in the transaction documents. Ask the international-tax adviser to address taxpayer identity, tracing, occupancy allocation, and applicable rental-income treatment. The lender should clarify disbursement mechanics and financing charges, while the closing agent should help preserve settlement and payment records.
For a West Palm Beach purchase at Alba West Palm Beach, the same coordination matters whether the initial intention is personal enjoyment or income production. These project references illustrate purchase contexts, not conclusions about leasing eligibility or tax treatment.
A short written responsibility schedule can identify who answers each question, who holds supporting documents, and which matters remain unresolved before signing or closing. Treat it as planning guidance, not a guarantee of deductibility.
Have counsel and the closing agent confirm any residential-transfer reporting obligations applicable to the actual transaction date rather than relying on an earlier checklist. Include that review among the matters to resolve before closing.
The strongest contract review leaves a clear ownership plan, a traceable funding path, a documented occupancy policy, and named advisers responsible for unresolved questions.
Explore South Florida residences with MILLION while your legal and tax advisers shape the ownership plan.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Entity ownership alone does not establish deductibility; the use of borrowed funds, the relevant taxpayer, and applicable limitations require separate analysis.
Generally, tracing follows how the borrowed proceeds are used rather than the collateral. A loan secured by a residence is not automatically investment debt.
The related interest must be allocated between the uses. It should not be assumed wholly deductible.
A separate account for a particular loan's proceeds helps simplify tracing. Records must still show the expenditures funded by that debt.
Certain family stays, owner occupancy, and below-market occupancy can count as personal use under applicable mixed-use dwelling rules. The adviser should determine how those rules apply to the structure.
Records should distinguish fair-rental-value rental days from personal-use days. Agreements, payment evidence, and an occupancy calendar can support the allocation analysis.
For a qualifying nonresident alien, it treats qualifying real-property income as effectively connected income and permits net-basis taxation with attributable deductions. Applicable deduction limitations still apply.
No. The adviser must identify the relevant taxpayer and entity tax treatment before determining whether the individual nonresident-alien election rules apply.
The electing individual must file Form 1040-NR for the election year and subsequent years until revocation. Form W-8ECI should be provided to the relevant withholding agent in the first election year and when otherwise required.
Counsel and the closing agent should confirm the obligations applicable to the actual transaction date. Buyers should not rely solely on an earlier checklist.