Continuum’s historically disclosed assessment approvals are a starting point, not a unit-level liability statement. Buyers should connect authorization, construction scope, contract pricing and collection records before negotiating responsibility at closing.
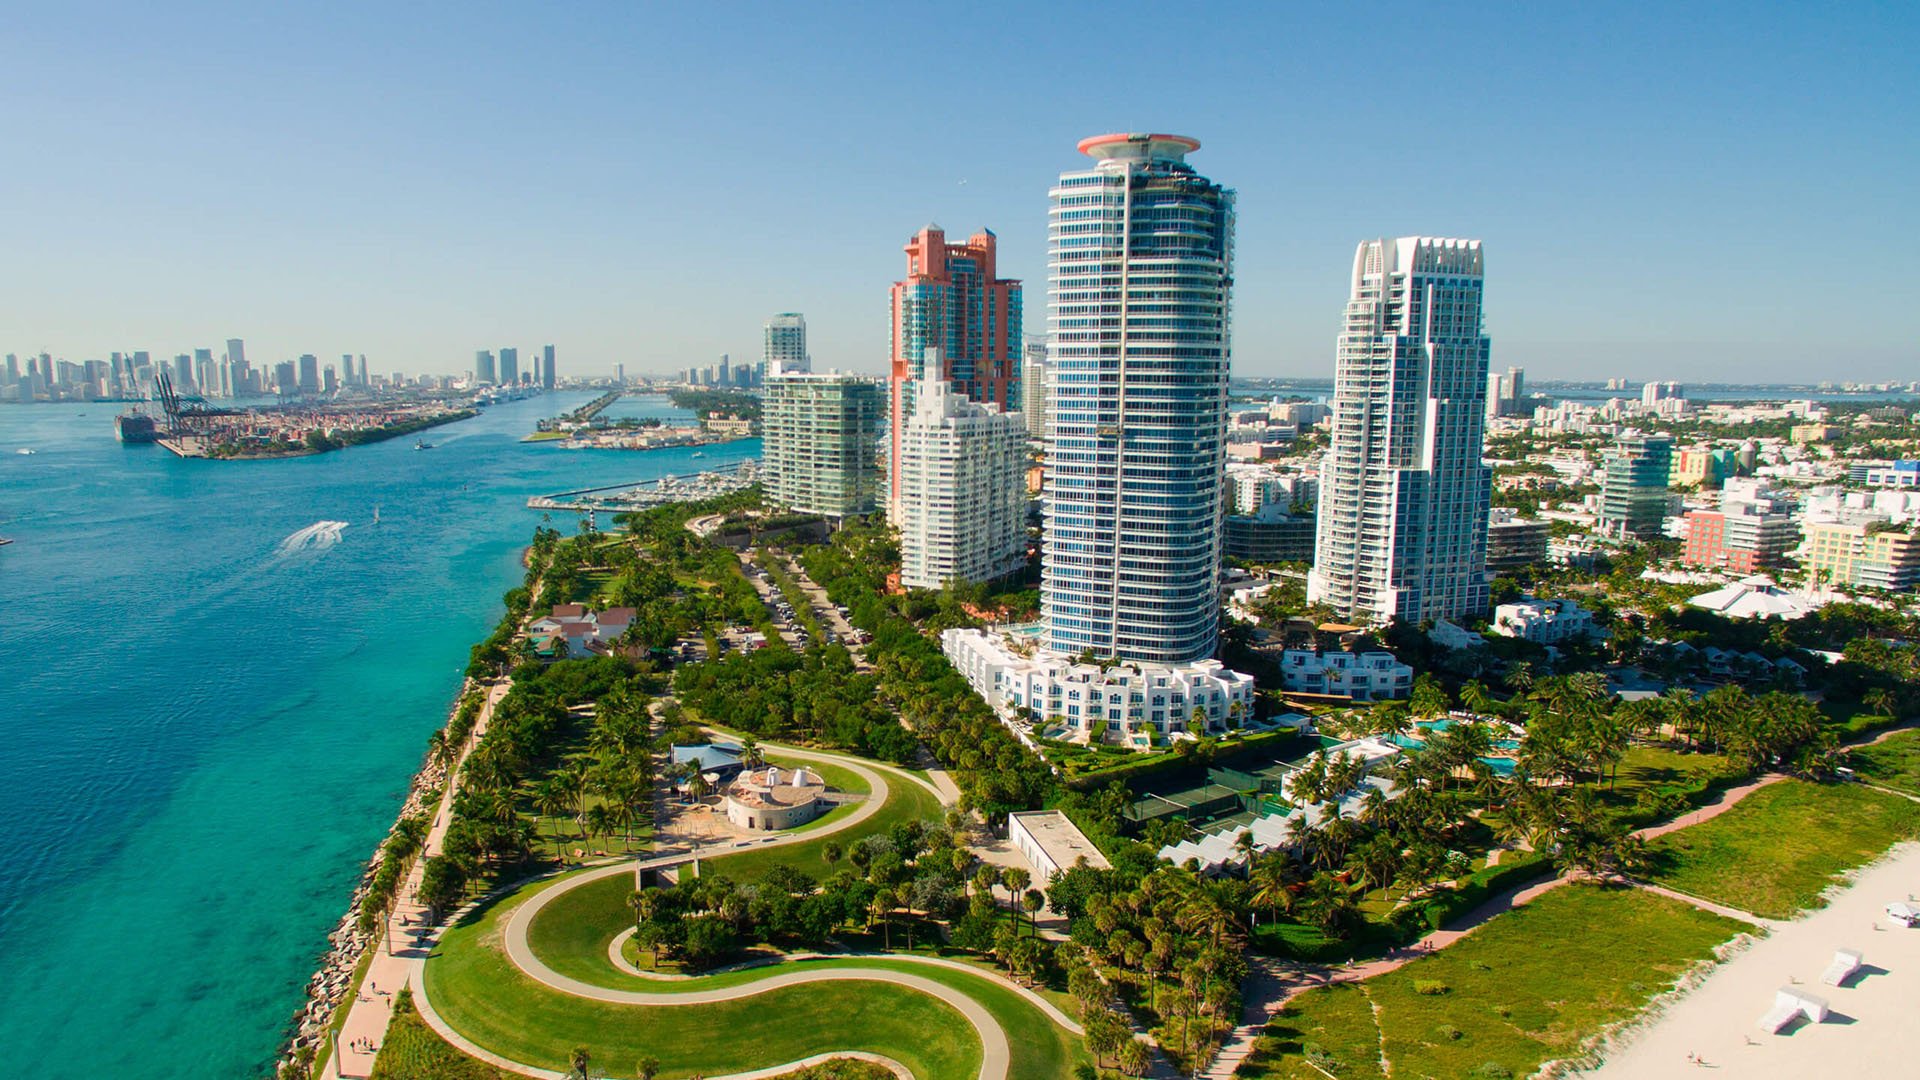
At Continuum on South Beach, the assessment question is not simply the size of the headline number. It is what that number authorizes, how firmly the work is priced, and what remains collectible. For a luxury buyer, those distinctions belong alongside the residence’s purchase price, not in an appendix to the decision.
Approval of a $27.2 million assessment for repairs and renovations was disclosed on December 19, 2024, following an approximately $30 million assessment two years earlier. Together, those historical approvals total approximately $57.2 million. They do not establish any particular residence’s allocation, unpaid balance or amount still payable today.
A special assessment is a nonrecurring association charge, separate from regular monthly dues, used to fund a project or shortfall. Approval, construction progress and payment are distinct milestones. A buyer needs to connect all three before treating an assessment as either a resolved expense or a future obligation.
Begin with the approving resolution or meeting minutes, the assessment notice and the stated purpose. These documents should identify the applicable association and the assessment at issue. Do not assume that a property-wide description establishes the precise tower or association coverage for the residence under consideration.
Distinguish an adopted assessment from a proposal, a preliminary discussion or a potential future charge. Each deserves attention, but they are not interchangeable. A listing’s brief assessment notation cannot replace the underlying authorization or explain whether subsequent decisions changed the original arrangement.
Ask condominium counsel to review applicable notice and procedural requirements, including the notice’s description of purpose and estimated cost. Requirements and exceptions call for transaction-specific interpretation; a general notice rule should not become a conclusion about the validity of a particular assessment.
The next step is to reconcile the engineering scope with the budget. Request the underlying engineering findings and an itemized project budget, then identify which funded items address structural or life-safety needs and which represent discretionary improvements. A broad repairs-and-renovations description does not provide enough detail for that analysis.
The distinction is especially important in a luxury residence, where preservation and enhancement may share a capital program. Neither category should be inferred from the building’s positioning. The scope must explain what owners are paying for, rather than leave the buyer to interpret an aggregate number.
For buyers also considering Apogee South Beach, the same document standard should guide the comparison. This is a diligence principle, not a suggestion of equivalent assessments: compare the work and funding obligations established for each residence, rather than transfer assumptions from another property.
Ask management to reconcile the authorized scope with the work currently planned, underway or completed. A historical approval alone establishes none of those present-day conditions.
An assessment amount may be based on preliminary engineering estimates, contractor bids or signed construction contracts. Each represents a different level of pricing commitment. Establish which formed the basis of approval and whether later procurement changed the budget.
Review the bid basis against the scope being purchased. Then examine contract pricing, contingencies, approved change orders and value-engineering adjustments. A lower revised figure deserves scrutiny if the work has also changed; a higher figure requires an explanation tied to scope or contractual revisions.
Compare the authorized funding with the latest documented project budget. Ask whether they still align, what contingency remains and which costs are not yet fixed. These questions test budget exposure without presuming an overrun.
Do not treat an approved assessment as evidence that contracts are fully executed, construction is complete or all project costs are settled. Each conclusion requires its own supporting record.
Collection status has two distinct meanings. The first is the residence’s own account: its total allocation, installment schedule, credited payments and remaining balance. The second is the association’s collection position across assessed owners. One cannot substitute for the other.
At the unit level, request a current ledger that reconciles the original charge with payments already received. Confirm which installments remain and when they fall due. The initial assessment allocation is not necessarily the amount a purchaser would assume.
At the association level, request current information on collections, outstanding installments, delinquencies and any relevant collection disputes. Compare receipts and scheduled collections with the project’s payment obligations. This frames the funding questions without implying that Continuum has a collection shortfall.
Potential liens and procedural challenges also merit separate review. A clear construction scope does not answer a title or collection question, just as a paid unit ledger does not establish that every other owner has paid.
Assessment responsibility should be explicit in the purchase contract. Specify whether the seller will pay the remaining assessment at closing or the buyer will assume some or all future installments. Do not rely on an informal assurance that the assessment is “handled.”
Match the negotiated arrangement to the current unit ledger and installment schedule. Have counsel distinguish responsibility for adopted assessments from the treatment of proposals or possible additional charges. Those categories should not disappear into a single closing-cost assumption.
For a Miami Beach buyer weighing Faena House Miami Beach alongside Continuum, this approach supports a more disciplined comparison: purchase price, regular dues and verified assessment obligations considered together. It does not imply a comparable assessment history at either property.
Completing one capital program does not eliminate future repair needs. Florida’s post-Surfside framework calls for structural inspections and structural integrity reserve studies for qualifying associations, helping identify future work and funding requirements.
Review the applicable inspection findings, reserve study and funding plan alongside the assessment documents. Ask whether pending findings could generate additional charges. Confirm current legal obligations with counsel rather than infer them from historical assessment coverage or an earlier legislative timetable.
The investment distinction is straightforward: an assessment may fund defined work, while the reserve plan addresses future needs. A buyer should understand both before describing the residence’s capital exposure as settled.
The strongest purchase file connects authorization to scope, scope to pricing, and pricing to collections. It then translates those association-level records into the residence’s allocation and the parties’ agreed payment responsibility.
Continuum’s historical totals warrant scrutiny, but they are not a verdict on a particular purchase. The decision becomes clearer when the buyer can identify what was approved, what is being delivered, what has been paid and what remains their contractual responsibility.
For a discreet perspective on South Florida luxury ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationDecember 19, 2024, disclosures described a $27.2 million assessment for repairs and renovations following an approximately $30 million assessment two years earlier. These are historical approvals, not confirmation of amounts still payable.
No. The combined historical approvals do not establish a particular unit’s allocation or remaining balance; those require unit-specific records.
A special assessment is a nonrecurring association charge in addition to regular dues. It funds a project or funding shortfall and may be collected in installments.
Request the approving resolution or meeting minutes, the assessment notice and the stated purpose. Confirm the applicable association and distinguish an adopted charge from a proposal.
The distinction clarifies what the assessment actually funds. Engineering findings and an itemized budget help identify structural or life-safety work separately from upgrades.
Preliminary estimates, contractor bids and signed contracts represent different levels of pricing commitment. Review contingencies, approved changes and the latest budget to understand remaining exposure.
It should reconcile the unit’s total allocation, credited payments, installment schedule and remaining balance. The original charge alone does not show what is still owed.
No. A unit ledger tracks one residence, while association collection records address receipts and outstanding amounts across assessed owners.
The purchase agreement should specify whether the seller pays at closing or the buyer assumes some or all remaining installments. The agreed arrangement should match current account records.
No. Future inspection findings and reserve funding needs can create additional obligations, so buyers should also review the applicable reserve study and funding plan.