A Downtown Miami address is only one part of a well-documented move from New York. Separate domicile from statutory residency, manage travel days conservatively, and align your housing records, registrations, and homestead application with how you actually live.
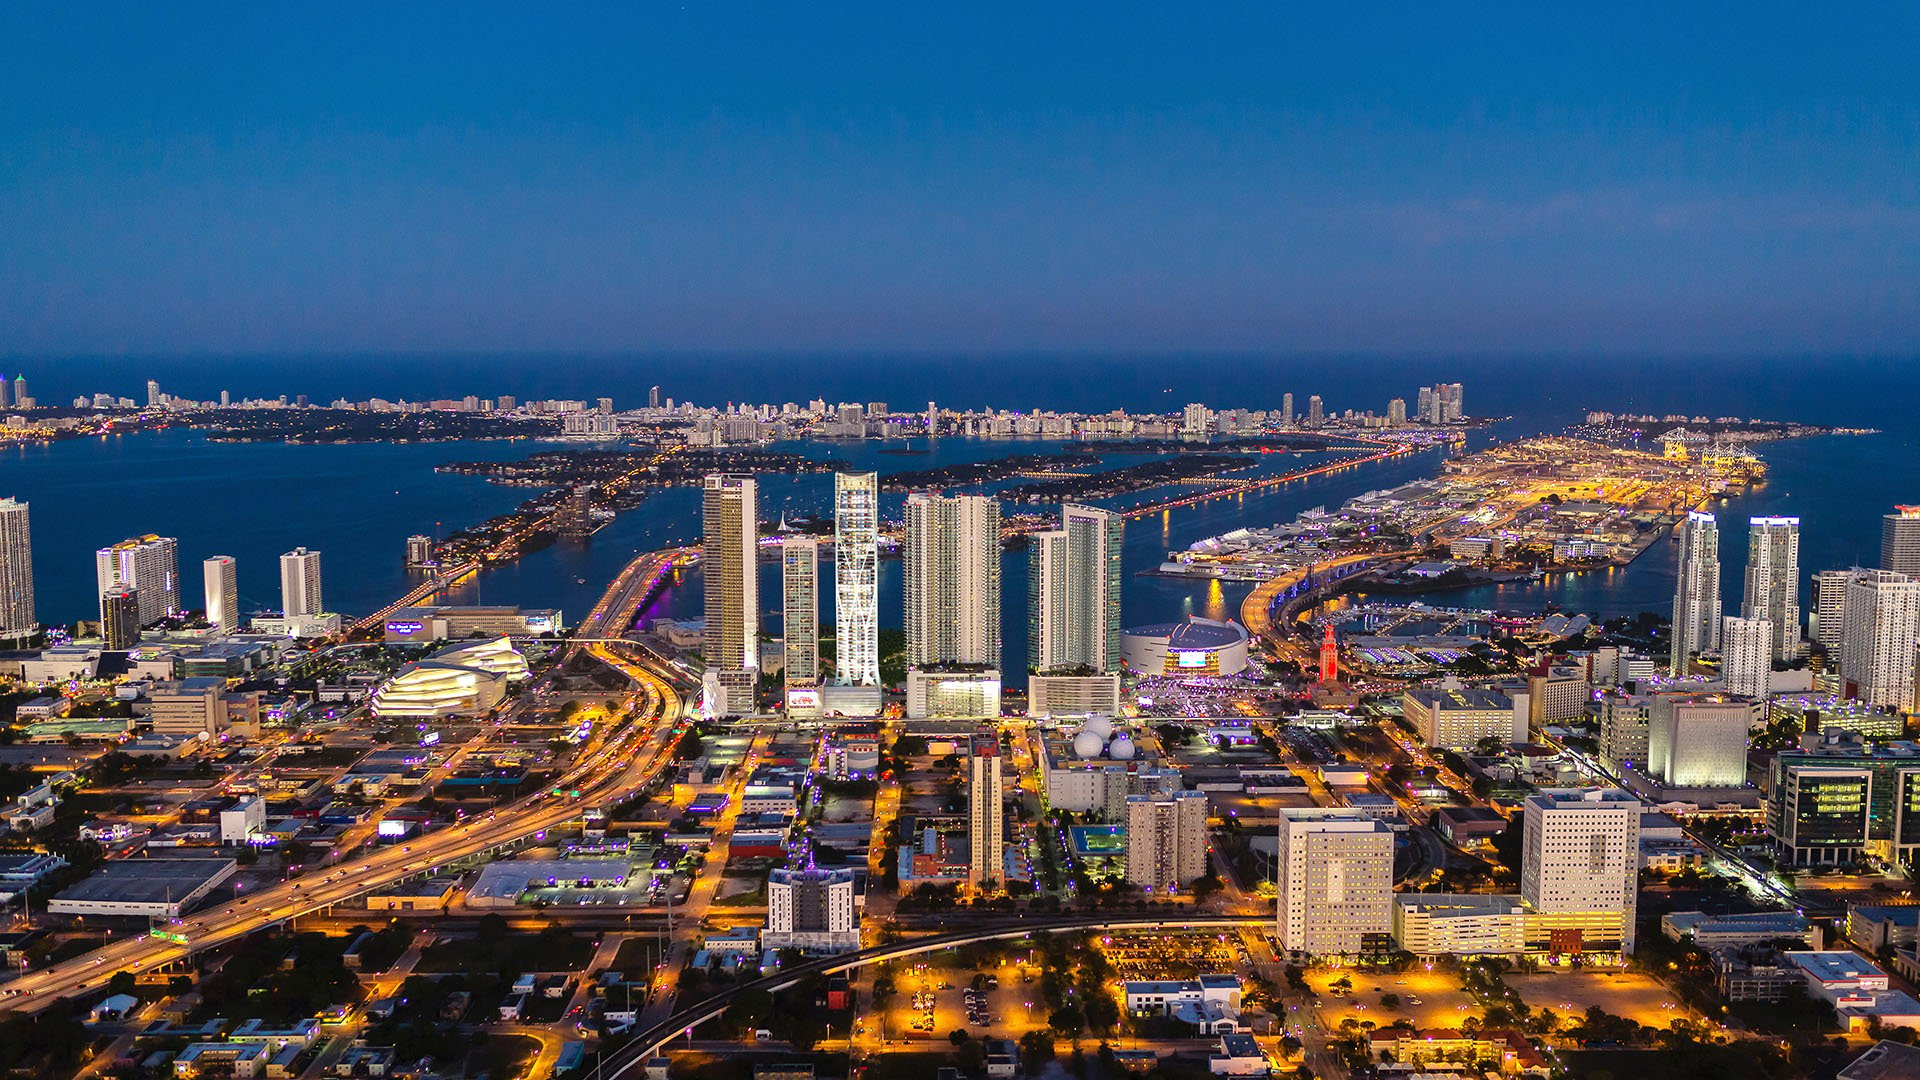
For a household accustomed to summers in the Hamptons, making Downtown Miami a principal home requires more than redirecting winter travel. The residence, calendar, and documentary record should reflect the same life. A purchase can anchor the transition, but it cannot establish a change of domicile on its own.
Whether your search includes Aston Martin Residences Downtown Miami or another Downtown address, distinguish the property decision from the residency analysis. One concerns where you want to live; the other examines where you actually make your permanent home and how much time you spend in New York.
The objective is not a persuasive mailing address. It is a genuine move supported by consistent, dated evidence. Individualized New York and Florida tax advice should guide that work.
New York residency presents two distinct questions. Domicile concerns your principal, permanent home. The analysis considers your overall pattern of life, including homes, time spent, business involvement, family connections, and meaningful personal possessions.
Statutory residency generally requires both a permanent place of abode in New York for substantially all of the tax year and at least 184 days of New York presence. A person domiciled in Florida can still become a New York statutory resident by meeting those tests.
Staying at 183 New York days or fewer avoids that statutory day-count threshold. It does not, by itself, establish that New York domicile has ended. Conversely, Florida registrations do not neutralize New York's abode and presence tests.
Treat these as parallel tasks: substantiate the change of permanent home and maintain a reliable New York day count. Neither substitutes for the other. Nor should the specialized 548-day rule become a shortcut in an ordinary Florida move: it involves at least 450 days outside the United States, along with additional conditions.
New York generally counts any part of a day spent in the state, subject to limited exceptions. The question is not simply where you slept. A business meeting, dinner, or brief visit can count even without an overnight stay.
For example, a hypothetical morning in Miami followed by an evening meeting in New York generally creates a New York day. Recording only that night's lodging, or leaving travel dates unassigned, can obscure the actual count. Have counsel assess any claimed exception rather than assuming it applies.
Use a daily record with these fields:
Date and every state visited.
Departure and arrival times.
Trip purpose and transportation.
Lodging and links to supporting records.
Track New York, Florida, other U.S. states, and foreign travel separately. A day outside New York is not automatically a Florida day, and a travel date may include presence in more than one state.
Before committing to a Hamptons season, enter anticipated business trips, family visits, and other New York commitments on the same calendar. Budget conservatively below 184 New York days, leaving room for disruptions and unexpected visits. That buffer is a planning recommendation, not a separate legal threshold.
Retain travel documentation and credit-card transactions to corroborate entries. Taxpayers claiming nonresident status while maintaining a New York permanent place of abode must keep adequate records substantiating that they did not exceed 183 New York days.
A Hamptons property retained for year-round personal use may remain a New York permanent place of abode after a Miami purchase. Review its continued availability specifically, even if the household describes it as a summer retreat.
Do not assume that offering the house for rent, or signing a lease, creates a safe harbor. Ask tax counsel to assess the lease terms, possession dates, actual access, and continued personal use. Preserve documents showing how the property was used or disposed of during the transition.
Keep the travel calendar and housing file aligned. If your position depends on limits to personal access, the underlying agreements and actual household arrangements should support it. Labels alone do not resolve the analysis.
For a buyer considering One Thousand Museum Downtown Miami, the residency question extends beyond ownership: will this be the home around which ordinary life is organized?
Document the transition with dated Miami housing records, moving invoices, utilities, insurance, and address changes. Consider where meaningful possessions are kept and whether household arrangements, correspondence, family connections, and business involvement support the claimed move. These form an overall picture, not a mechanical checklist in which one document determines the result.
Florida driver's licenses, voting records, vehicle registrations, and domicile declarations can support a change. No single administrative document conclusively determines domicile. Update records to reflect the real transition, rather than expecting those updates to create it.
As a practical discipline, reconcile the calendar regularly and arrange quarterly professional reviews. These are recommendations, not stated statutory requirements. Resolve inconsistencies while travel details and supporting documents are still readily available.
Miami-Dade's homestead exemption requires the property to be the owner's permanent residence as of January 1. Plan for that timing alongside your move, but do not treat homestead as a substitute for the separate New York residency analysis.
The application requests a Florida driver-license or identification-card number and Florida vehicle-tag information. It also requests Florida voter-registration information for U.S. citizens and details of previous residency outside Florida, including when it ended.
Those answers should agree with your actual move and broader domicile records. A recorded Declaration of Domicile is among the documents that may support an application; it is not conclusive proof that New York domicile has ended.
Submit homestead applications and supporting documentation to the property appraiser in the county where the property is located. For a Downtown Miami home, include that local filing in the transition calendar rather than leaving it disconnected from the rest of the move.
A search that includes Casa Bella by B&B Italia Downtown Miami should remain grounded in the household's intended daily life. Whether waterfront appeal or another preference leads the search, ask whether the selected residence genuinely supports your plan to make Miami home.
Before finalizing the transition, review three elements together: the Miami housing timeline, the future use of the Hamptons property, and the travel calendar. Have advisers examine them as one factual picture rather than as unrelated files.
The strongest practical approach is consistent: make the move, record it accurately, and revisit the evidence as circumstances change. This guide does not determine whether any particular move ends New York tax obligations.
Explore your Downtown Miami residential options with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. A purchase alone does not establish a change from New York domicile; the overall pattern of life must support Miami as the principal, permanent home.
New York statutory residency generally requires both a permanent place of abode in the state for substantially all of the tax year and at least 184 days of New York presence.
No. It avoids the statutory-residency day-count threshold, but ending New York domicile is a separate factual inquiry.
Yes. New York generally counts any part of a day in the state, subject to limited exceptions, so a meeting or dinner can count.
Record every state visited, departure and arrival times, trip purpose, transportation, lodging, and supporting records. Midnight location alone is insufficient.
Yes. A house retained for year-round personal use may remain a New York permanent place of abode, even after a Miami residence is acquired.
No rental safe harbor should be assumed. Counsel should assess lease terms, possession dates, actual access, and continued personal use.
Dated housing and moving records, utilities, insurance, address changes, Florida registrations, and a domicile declaration can support the transition. No single administrative document conclusively determines domicile.
The property must be the owner's permanent residence as of January 1. Applications and supporting documents go to the property appraiser in the county where the property is located.
It is not the ordinary framework for a Florida move. The specialized rule involves at least 450 days outside the United States and additional conditions.