A trust or LLC addresses how a residence is held, not what its service model costs. At Auberge Beach, disciplined diligence connects entity approval with operating performance, contract increases, staffing assumptions, and transaction-specific tax advice.
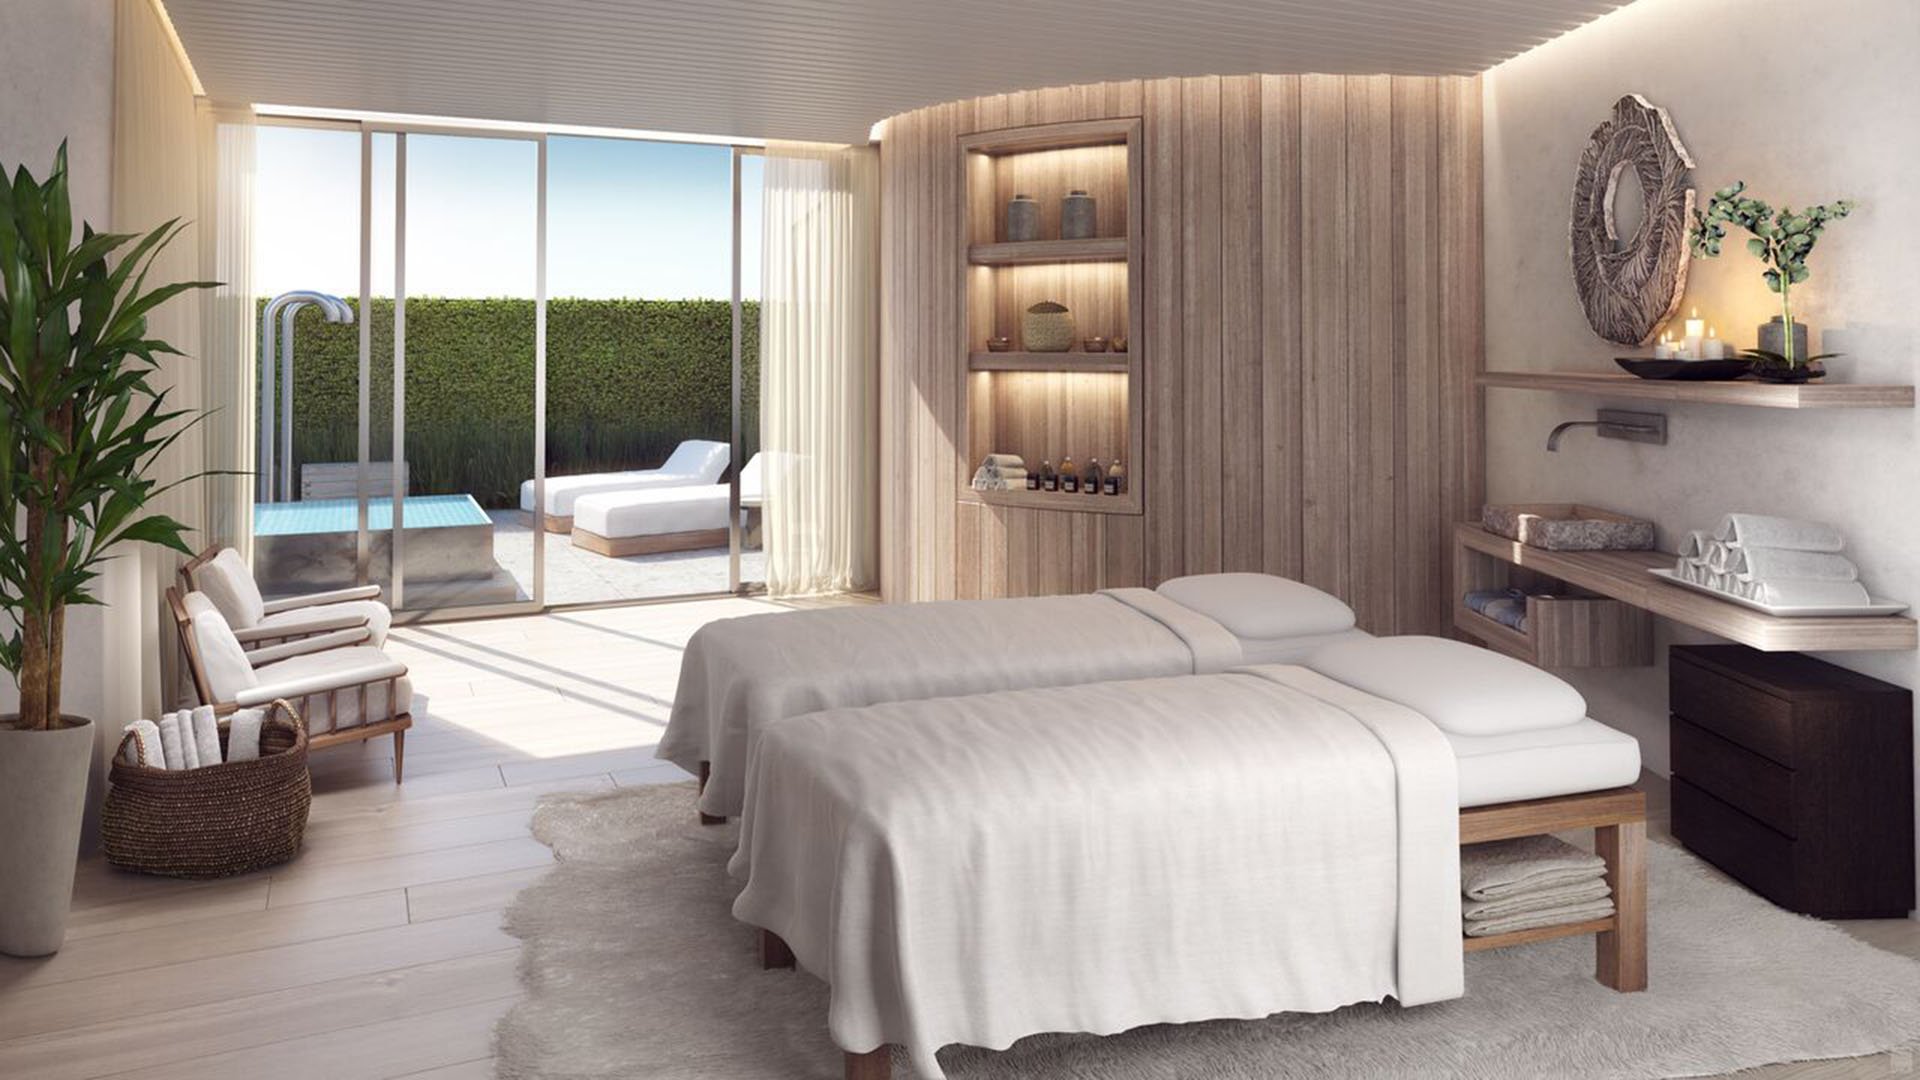
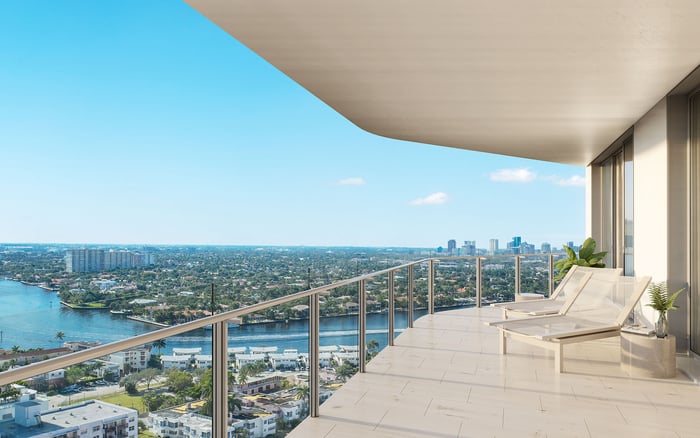
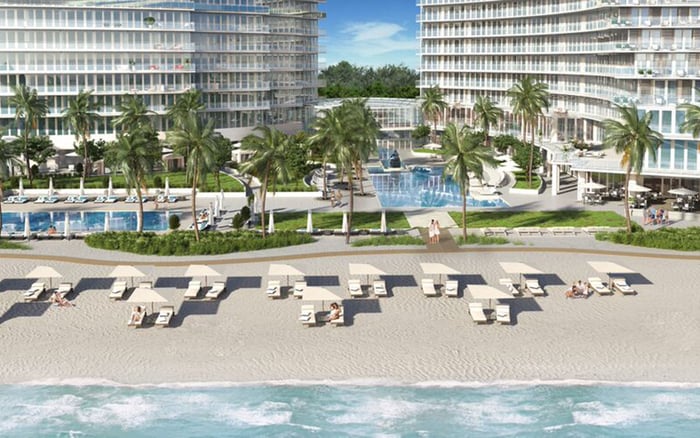
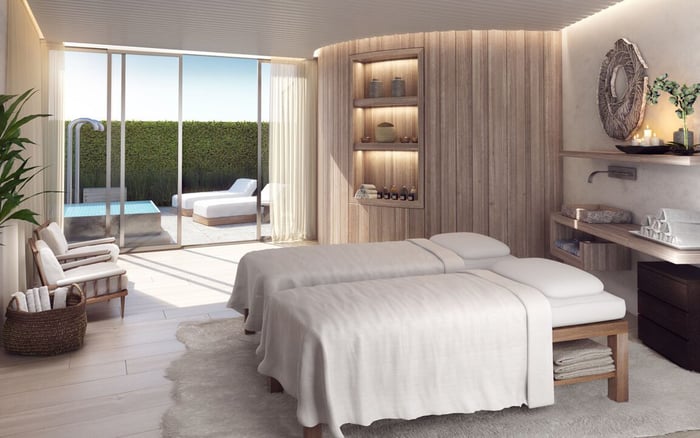
At Auberge Beach Residences & Spa Fort Lauderdale, the attraction is residential life organized around the ocean and attentive service. The property occupies 2200 North Ocean Boulevard in Fort Lauderdale, with completion dates for the North and South Towers in the third and fourth quarters of 2018, respectively. Its original vision was explicitly “private club-style,” with a restaurant, indoor-outdoor lounge, spa, pools, gardens, and spaces for children and meetings.
For a buyer considering a trust or LLC, that setting presents two distinct decisions: how to hold the residence and how to evaluate the economics supporting its services. An ownership structure does not make the operating budget more predictable.
A Fort Lauderdale Beach purchase should therefore proceed on parallel tracks. Counsel should examine title and entity approval, while the buyer’s financial review tests assessments, contracts, and staffing assumptions. Neither review substitutes for the other; both should inform the purchase decision.
Florida condominium operations are assigned to an association organized as a Florida for-profit or nonprofit corporation. Holding a unit through a trust or LLC does not itself remove assessment obligations or the association’s enforcement powers.
Begin with the declaration, bylaws, and purchase-approval requirements. Ask counsel to confirm whether the proposed structure may hold title, what documentation the association requires, and how occupants must be designated. Review leasing provisions separately: approval of an entity should not be taken as approval of every intended use.
For a trust, clarify who has authority to sign and communicate with the association. For an LLC, ask which organizational and authorization documents must accompany the application. These are transaction questions, not established Auberge requirements.
The objective is practical: align the buyer named in the contract, the proposed titleholder, and the application package before timing becomes a closing issue.
An assessment figure is a starting point, not a complete ownership forecast. Request the current adopted budget, recent actual-versus-budget statements, reserve schedule, and a unit-specific estoppel. Establish what the residence owes rather than extrapolating from another unit’s advertised fee.
Compare spending with the budget by category and period. Ask whether an unfavorable variance reflects timing, a one-time event, or a recurring expense. Scrutinize favorable variances as well: lower spending associated with an unfilled position tells a different story from a durable reduction in contract cost. These are analytical possibilities, not findings about Auberge.
Keep operating performance distinct from reserve funding. A balanced operating result does not, by itself, establish whether planned reserve contributions align with future expenditures. Ask for explanations that connect the figures to the underlying obligations.
If Four Seasons Hotel & Private Residences Fort Lauderdale is also on the shortlist, apply the same questions to its documents. Compare what each assessment funds, not simply the headline amount. The useful comparison is the cost of the service package the buyer intends to use.
Auberge Resorts Collection was originally designated as manager. That historical designation does not establish today’s management agreement, fee structure, or termination rights. Current executed agreements and applicable amendments should guide the review.
Request management and applicable brand or vendor agreements through the appropriate transaction channels. Where an agreement contains an escalator, identify its calculation base, adjustment date, and whether increases are fixed or linked to an index. Check for caps, floors, pass-through expenses, renewal dates, and termination provisions where present.
Then connect each contractual obligation to the budget. Ask whether the adopted figures reflect the next scheduled increase and whether additional reimbursable expenses sit outside the headline fee. A stated cap deserves particular scrutiny if other charges can change independently.
For buyers also considering Shell Bay by Auberge Hallandale, the shared brand name should prompt careful document review, not an assumption of matching economics. Evaluate each property’s agreements independently.
Personalized concierge services and around-the-clock valet and security are advertised amenities at Auberge Beach. Their appeal is clear; the diligence question is how the current operating plan supports the promised coverage.
Ask for budgeted positions, coverage hours, vacancies, overtime assumptions, benefits, and outsourced labor arrangements. Distinguish the number of positions from the hours of service they are intended to deliver. Clarify whether the budget assumes full staffing or incorporates vacancies.
Ask how costs are allocated between residential services and commercial amenities, where applicable. Do not presume that dining or spa operations are subsidized by the association, or that everyone working on the property is an association employee.
Obtain a written schedule separating association-funded services from spa treatments, dining, resident-account purchases, and other optional charges. Access to an amenity and payment for using it are different questions.
Florida’s general documentary stamp tax rate on deeds is $0.70 for each $100 of consideration, including a fractional part. A trust or LLC is not an automatic exemption.
Specific transfer determinations illustrate why the details matter. A qualifying land-trust transfer, with the individual remaining the sole current income beneficiary and retaining full revocation rights, received minimum-tax treatment. Particular transfers involving unencumbered property and a sole-member LLC or a related trust and LLC received favorable treatment. By contrast, a transfer of encumbered property from a trust to a newly formed Florida LLC was taxable in the circumstances examined.
These outcomes should not be generalized to an arm’s-length purchase from a seller. Ask Florida counsel and a tax adviser to examine the actual consideration, debt, ownership continuity, beneficial interests, and transfer sequence. Evaluate any proposed post-closing restructuring separately rather than assuming it will be tax-neutral.
Before closing, consolidate the findings into one decision document: approved title structure, unit-specific obligations, explanations for material variances, applicable contract increases, staffing assumptions, and separately charged services.
Build a baseline from current documents. Then ask advisers to test alternatives using disclosed renewal terms and explicitly labeled assumptions. Do not insert an arbitrary annual increase and treat it as a property forecast. Resolve unexplained differences between budgeted costs and contractual commitments before relying on the total.
The aim is not to strip the purchase of its pleasure. It is to understand the financial commitments behind the service experience, with the ownership structure properly aligned to the buyer’s plans.
For a considered approach to South Florida residential ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe oceanfront residential property is at 2200 North Ocean Boulevard, Fort Lauderdale, FL 33305.
Development information lists North Tower completion in the third quarter of 2018 and South Tower completion in the fourth quarter of 2018.
Have counsel review the declaration, bylaws, and purchase-approval requirements to confirm whether the proposed structure is permitted and what conditions apply.
No. Holding the residence through a trust or LLC does not itself remove assessment obligations or the association’s enforcement powers.
Request the current adopted budget, recent actual-versus-budget statements, reserve schedule, and unit-specific estoppel. Ask for explanations of recurring or material variances.
Determine whether it reflects lasting savings, timing, or a temporary condition such as a vacancy. Lower spending alone does not establish that future costs will remain lower.
If present, examine fixed increases, index links, caps, floors, and pass-through expenses. Review adjustment dates, renewal terms, and termination provisions alongside the budget.
Ask about budgeted positions, coverage hours, vacancies, overtime, benefits, and outsourced labor. Clarify applicable cost allocations between residential services and commercial amenities.
Do not assume they are included. Obtain a written schedule distinguishing association-funded services from separately charged treatments, dining, and other optional purchases.
No. Treatment depends on the transaction’s consideration, encumbrances, ownership continuity, and structure; favorable treatment for a particular restructuring should not be applied automatically to a purchase.