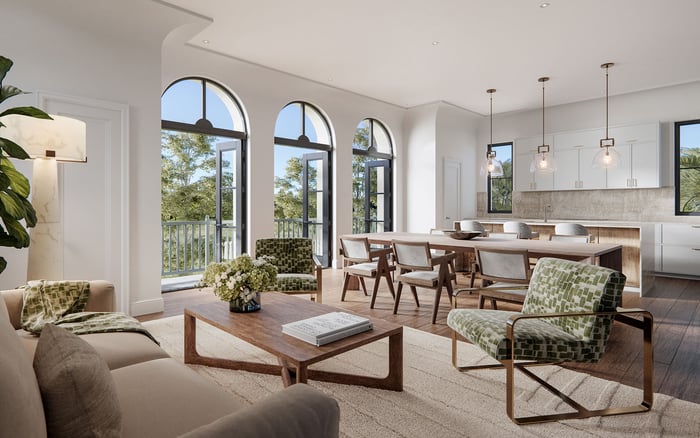
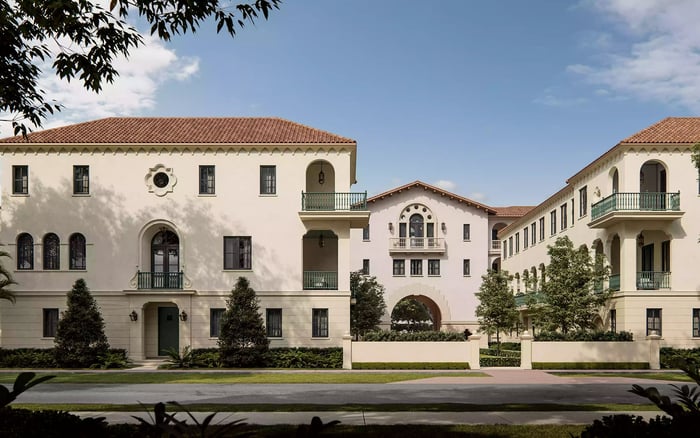
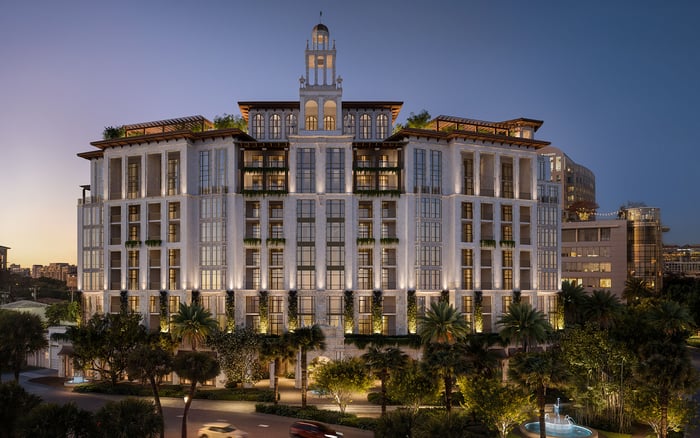
A considered Zurich-Coral Gables life begins with family, work and everyday preferences. Coordinated Swiss and U.S. advice should clarify residence, travel thresholds and income-specific taxation without choosing the home for you.
A two-city life between Zurich and Coral Gables should begin with the household, not a day-count spreadsheet. Where will children study, where will healthcare relationships be maintained, and where can each partner sustain meaningful work and friendships? The right residence should support those answers, not require the family to reorganize itself around a tax assumption.
For a buyer considering Ponce Park Coral Gables, the first brief should describe an ordinary week: working hours, family visits, privacy requirements and time spent away. These are purchase criteria in their own right. They also give advisers a more accurate picture than the convenient label “winter home.”
Tax planning should support a genuine two-city life, not manufacture one. Before committing to a residence, ask Swiss and U.S. advisers to test the intended arrangement together-including what happens if a school decision, extended visit or work commitment changes it.
Florida imposes no personal state income tax and requires no state personal-income-tax return from individuals. That distinction matters, but it does not fully explain the cost of living between Switzerland and the United States. A foreign national can still become a U.S. federal tax resident under the substantial presence test.
Request one written analysis with four clearly separated parts: U.S. domestic tax residence, Swiss domestic tax residence, treaty residence and the taxing rights attached to each income category. These questions interact, but they are not interchangeable. A conclusion under one heading should not silently become the answer under another.
Swiss advisers should address the applicable domestic rules and the relevant federal, cantonal and communal dimensions. The treaty covers specified Swiss income taxes at all three levels. U.S. advisers should assess the federal position, with both teams cross-reviewing the same household facts and proposed calendar.
The substantial presence test generally requires at least 31 U.S. days in the current year and 183 weighted days across three years. The calculation includes all current-year days, one-third of the preceding year’s days and one-sixth of the second preceding year’s days.
Staying below 183 actual U.S. days in a single year therefore does not necessarily avoid substantial presence. Prior visits matter. Ask advisers to review the rolling calculation before extending a stay, rather than treating the current calendar year as a clean slate.
The closer-connection exception is separate. It generally requires fewer than 183 actual U.S. days, a foreign tax home throughout the year and a closer connection to the foreign country. Claiming it generally requires timely filing of Form 8840. Applying for lawful permanent residence, or taking certain other steps toward that status, can make the exception unavailable.
A third test concerns the treaty’s short-stay employment exemption. Its 183-day condition is not sufficient by itself: employer residence and whether remuneration is borne by a local permanent establishment or fixed base also matter. The practical instruction is simple: whenever an adviser refers to “183 days,” clarify which test they mean.
Owning a residence in each city does not settle treaty residence. Where an individual is resident in both countries under domestic law, the treaty tie-breaker examines permanent home, center of vital interests, habitual abode and nationality in sequence, with competent-authority agreement available if necessary.
If permanent homes are available in both Zurich and Coral Gables, the next inquiry is where personal and economic relations are closer. A purchase at The Village at Coral Gables should therefore be evaluated as a home first, not as documentation that automatically establishes or displaces residence.
The closer-connection inquiry also looks beyond labels to the location of family, personal belongings, business activities and social or civic affiliations. These are genuine features of a life, not merely statements to place in a file. Ask advisers to distinguish this domestic exception from the treaty tie-breaker, even when some underlying evidence overlaps.
Citizenship and immigration status deserve explicit treatment. The treaty’s saving clause generally preserves U.S. taxation of U.S. citizens, subject to specified exceptions. Lawful permanent residents require separate analysis of treaty claims and their consequences; they should not simply be grouped with citizens or short-stay visitors.
Treaty residence is not a blanket exemption from U.S. taxes. Employment income, directors’ fees, business profits, dividends, interest, pensions, real-estate income and capital gains fall under different provisions. The coordinated analysis should address each relevant category rather than apply one conclusion to the household’s entire financial life.
Work performed physically in Coral Gables can give the United States taxing rights even when the employer is Swiss, subject to the treaty’s employment-income exemption. A working stay therefore needs a work-location record, not just flight confirmations. Before treating an extended visit as business as usual, have advisers examine the actual employment arrangement.
Property income deserves separate attention. The treaty permits the country where real estate is situated to tax income from that property. Swiss treaty residence does not, by itself, exempt Coral Gables rental income from U.S. taxation. Any plan to rent the residence during absences should be reviewed alongside the intended pattern of personal use.
Keep a single household calendar recording travel, physical work locations, available homes, family location, schooling and rental periods. Support it with contemporaneous records. The purpose is to help both teams analyze the same reality, rather than reconcile conflicting recollections at filing time.
Ask the advisers to cross-review one written position using the applicable treaty, amending protocol and technical explanations together. Assign responsibility for calculations, filing obligations and unresolved questions. Revisit the position when actual living arrangements diverge from the original plan.
Property ownership structures, estate tax, foreign-account reporting and payroll should be scoped separately with the appropriate specialists. A residence analysis should not be mistaken for clearance on those subjects.
When evaluating Cora Merrick Park, return to the original household brief. Does the residence suit the weeks the family genuinely intends to spend there? Is there appropriate space for work and guests? What arrangements will keep the home cared for during Zurich stays? Verify those practical details independently of the tax analysis.
The strongest purchase is one the household would still value after advisers replace broad assumptions with specific obligations. Choose the home for the life it enables, then keep the legal and tax position aligned with how that life actually unfolds. This is a planning framework, not individualized tax or legal advice.
Explore a considered Coral Gables residence search with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Florida imposes no personal state income tax, but federal residence rules and income-specific U.S. taxing rights still require analysis.
It generally requires at least 31 current-year U.S. days and 183 weighted days. The weighting includes all current-year days, one-third of the preceding year’s days and one-sixth of the second preceding year’s days.
Not necessarily. Earlier years’ visits enter the substantial presence calculation, so fewer than 183 actual days in the current year can still satisfy that test.
It generally requires fewer than 183 actual U.S. days, a foreign tax home throughout the year and a closer connection to the foreign country. Timely Form 8840 filing is generally required, and steps toward lawful permanent residence can make the exception unavailable.
No. If permanent homes are available in both countries, the treaty next examines where personal and economic relations are closer.
Yes, subject to the treaty’s employment-income exemption. That exemption involves employer residence and who bears remuneration, not merely a 183-day condition.
Not by itself. The treaty permits the country where real estate is situated to tax income from that property.
They should not be treated as interchangeable. The saving clause generally preserves U.S. taxation of citizens, subject to exceptions, while lawful permanent residents require separate review of treaty claims and consequences.
They should cross-review one analysis separating domestic residence in each country, treaty residence and income-specific taxing rights. A shared calendar should record travel, work locations, available homes and household arrangements.
Start with family routines, work, healthcare, community and everyday preferences. Then have advisers test the implications of that genuine living arrangement before committing to a purchase.