A practical framework for managing a part-time Coral Gables residence, from contractual deposits and independently verified wires to delegated spending authority, reconciliation, and secure records.
A part-time residence in Coral Gables should offer a change of pace, not a second set of financial uncertainties. For a family office, that ease depends on decisions made before the first deposit: who may commit funds, who verifies the destination, who releases payment, and where the supporting records are kept.
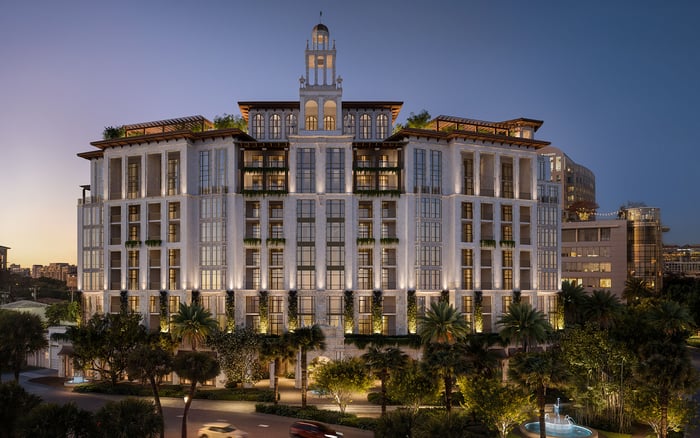
For a buyer considering Ponce Park Coral Gables, those questions belong alongside the choice of residence. The objective is not to burden ownership with administration, but to make the financial process reliable when the principal is elsewhere.
Do not assume part-time occupancy changes the applicable escrow or retention requirements. Keep three layers distinct: the buyer’s executed agreements, Florida requirements governing brokers, and the family office’s recommended internal controls. Review the applicable requirements with legal advisers.
Begin with the purchase and escrow agreements, not an assumed customary percentage. Record the deposit amount and timing specified for the transaction rather than relying on expectations from another purchase.
For a proposed purchase at Cora Merrick Park, the same discipline applies: establish the actual payment obligations from the executed documents rather than carrying assumptions over from another transaction. For staged purchases, record each contractual milestone separately.
An internal funding calendar should identify the paying entity, amount, contractual due date, escrow recipient, supporting document, and required approvers. Schedule preparation and review early enough to complete verification before payment is due. Internal scheduling does not change the contract.
Ask legal advisers to confirm the applicable escrow handling requirements, including who receives the funds, where they are held, and how disbursement is authorized. Track the buyer’s contractual deadline separately from any handling deadlines that apply to the broker; do not use the latter as an assumed extension of the payment date.
An emailed instruction sheet should begin verification, not conclude it. Before wiring a deposit or closing balance, independently confirm the escrow agent’s instructions by telephone. As an internal procedure, use contact information established independently of the payment message being checked.
New beneficiaries and changed bank instructions warrant fresh verification and additional approval. A familiar name in an email chain is no substitute for confirming the actual destination. Recommended practice is to pause release until the change has been checked and the necessary approvals renewed.
Separate four functions: preparation, approval, release, and reconciliation. The preparer assembles the payment package; an approver reviews the obligation and authority; a separately authorized person releases the transfer; and an independent reviewer matches it to the records afterward.
Family-member approval or dual approval can add an independent check before processing. Approval should identify the specific payment and verified instructions, rather than serve as general permission to fund the purchase. Keep the callback record, approvals, and banking evidence together so the decision can be reconstructed without searching individual inboxes.
Delegation is essential to a home used intermittently, but its boundaries should be explicit. Routine property-management expenses are different from acquisition deposits and capital improvements. Authority to keep the household functioning should not automatically include authority to make owner-level commitments.
For a family evaluating The Village at Coral Gables, this is an ownership question to settle before delegating household payments. Define authority around the family’s entity and governance structure, without assuming that a property’s services replace financial oversight.
A recommended approval matrix can distinguish:
Routine expenses within an approved budget, with delegated authority and retained supporting records.
Acquisition funding, with transaction-specific owner-level approval and independently verified escrow instructions.
Capital improvements, with approval of both the commitment and related payments.
New beneficiaries or changed banking details, with added verification and approval before release.
Emergency expenses, with a documented exception and independent review.
Set thresholds by transaction type, dollar amount, entity, risk, and urgency. No single dollar threshold is established here for every family office. Name authorized alternates before travel makes a principal unavailable. Urgency should activate a defined exception process, not eliminate controls.
A released wire is not the end of the payment process. Independent reconciliation should match outgoing funds to the underlying obligation, approvals, and banking records, while preserving evidence that the transfer was recorded correctly.
The audit trail should identify who requested, reviewed, approved, released, and recorded the payment. For acquisition funding, keep the relevant agreement and deposit instructions with that trail. For household expenses, retain the invoice and supporting approval. The standard is a payment history another authorized reviewer can understand.
Review bank signers, banking permissions, vendor information, and repository access periodically. Remove access when personnel leave. Delegation should remain current throughout ownership, not reflect a staffing arrangement that existed only at closing.
Maintain a secure, searchable repository with controlled access, backups, and documented retention procedures. Organize acquisition documents, payment evidence, approvals, and ongoing property records so authorized staff can retrieve them without relying on the principal’s inbox.
Ask legal advisers to distinguish any broker recordkeeping obligations from the family office’s own retention needs. Do not adopt a broker’s retention period as an automatic destruction date for the owner’s records.
For the owner’s records, establish a retention schedule with legal and tax advisers. The procedure should specify record categories, access permissions, retention decisions, and how litigation-related preservation is handled. Closing should mark the transition to an ownership file, not the disappearance of the acquisition trail.
Before leaving Coral Gables, confirm that upcoming obligations have named approvers, alternates understand their authority, and new or changed beneficiaries cannot bypass verification. Check that an independent reviewer can reconcile payments and retrieve the supporting documents.
The desired result is simple: routine ownership continues smoothly, while consequential decisions remain visible to the family. A well-run part-time residence does not depend on the principal being available for every invoice. It depends on knowing precisely which decisions require that attention.
Explore your next Coral Gables residence with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationDo not assume that part-time occupancy changes the applicable requirements. Have legal advisers distinguish contractual obligations, broker requirements, and recommended family-office controls.
Use the purchase and escrow agreements for the specific transaction. Do not substitute an assumed customary percentage for the agreed terms.
Track them separately from the buyer’s contractual payment deadline and confirm applicable requirements with legal advisers. Do not treat a broker handling deadline as an assumed extension for the buyer.
Independently confirm the escrow agent’s instructions by telephone using contact information established separately from the payment message. Do not rely solely on emailed instructions.
Changed instructions should receive independent verification and additional approval before release. Preserve evidence of the verification and renewed approval.
Recommended practice separates preparation, approval, release, and reconciliation. One person should not control the entire transfer.
Routine property-management authority should be distinguished from owner-level acquisition funding. The approval matrix should explicitly assign authority for each category.
Urgency should activate a documented exception procedure with independent review, rather than remove controls entirely. Authorized alternates should be identified in advance.
Establish the schedule with legal and tax advisers, including procedures for litigation-related preservation. Do not treat a broker’s retention period as automatic permission to destroy the owner’s records.
Retain supporting agreements or invoices, verification evidence, approvals, and banking records. The trail should identify who requested, reviewed, approved, released, and recorded the payment.