A considered two-city life requires more than a flight calendar. Separate Singapore tax-residency calculations from Florida domicile planning, maintain jurisdiction-specific travel records, and select a South Florida residence around how the household will actually live.
A home in Palm Beach Gardens and a continuing presence in Singapore can offer a compelling balance of personal space, family continuity and international business access. The arrangement is more durable when the household treats property selection, travel planning and residency classification as distinct decisions. A purchase establishes a place to live; it is not a shortcut to a tax conclusion.
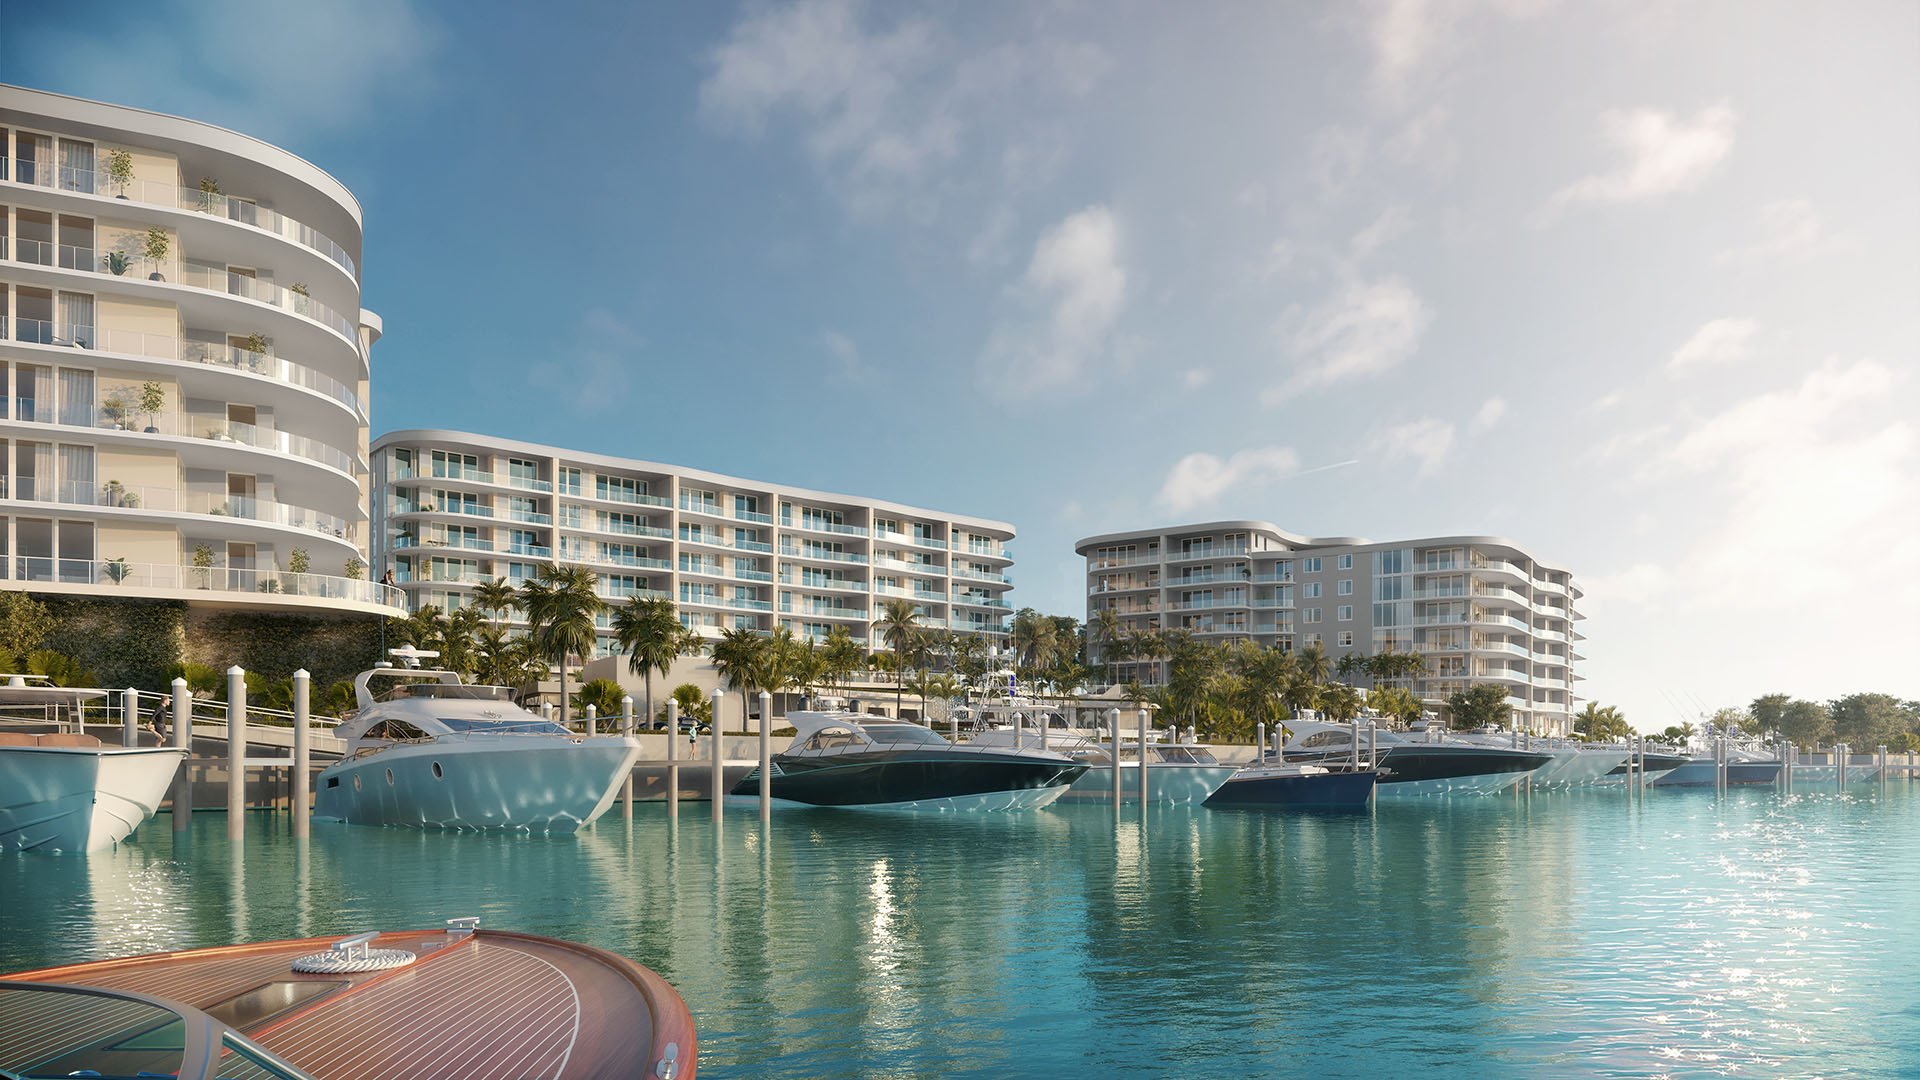
For buyers considering The Ritz-Carlton Residences® Palm Beach Gardens, the first question is how the residence will function: as a seasonal retreat, a regularly occupied base or the center of a broader relocation. The answer shapes both the calendar and the questions to bring to advisers. The Palm Beach chapter should be designed around actual use, not an assumed number of qualifying nights.
The governing principle is simple: a travel calendar records movement; residency analysis determines what that movement means.
Singapore individual income-tax rates depend on tax-residency status, so classification warrants a separate review before a household commits to a recurring travel pattern. For a foreigner, the general residency threshold is staying or working in Singapore for at least 183 days in the preceding calendar year. It is not an arbitrary rolling twelve-month test.
That distinction matters when travel straddles December and January. A single itinerary can cross two calendar years, but the annual calculation and any applicable multi-year treatment remain separate questions. Keep each calendar year visible rather than relying on a single total for the latest twelve months.
Singapore citizens and permanent residents have a different starting point: they qualify as tax residents when they normally reside in Singapore, except for temporary absences. A foreigner's day-count strategy should not be applied indiscriminately to a household whose members have different residency statuses.
Tax residence is also jurisdiction-specific. Extended travel or overseas work can result in residence in more than one country simultaneously. A Singapore conclusion does not, by itself, settle the position elsewhere.
Physical presence is only one part of the Singapore analysis. The three-consecutive-year residency concession can apply even when presence falls below 183 days in the first or third year. Separately, a qualifying employment period spanning two calendar years can establish residency when the total stay or employment period reaches at least 183 days.
For an employee based in Singapore, employment-day calculations include weekends and public holidays, not just days spent working. Certain temporary overseas absences, including vacation and business trips, can also count under the applicable rules.
A period spent in Florida may therefore belong in the physical-location calendar while still requiring consideration in the Singapore employment calculation. Record the trip accurately rather than assuming departure automatically stops every relevant count.
These distinctions make a narrow buffer below 183 physical-presence days an unreliable standalone nonresidency strategy. Before adjusting flights to reach a target, ask an adviser to review the employment arrangement, temporary absences and consecutive-year history. The calendar should implement that analysis, not substitute for it.
Do not translate Singapore's threshold into a presumed Florida rule. Spending 183 days in Palm Beach Gardens is not a universal formula for establishing Florida domicile. Obtain separate advice on domicile, any applicable state residency tests, homestead eligibility and state income-tax treatment before relying on a proposed schedule.
If another U.S. state remains part of the household's life, give that jurisdiction its own calendar and review. Combining all U.S. days into one figure can obscure the questions advisers need to examine. Property ownership, tax residence and domicile should remain distinct entries in the planning discussion.
A wider search in West Palm Beach, including Alba West Palm Beach, can proceed alongside that work. Evaluate the residence against the intended household routine, while keeping legal classification a separate analysis. The selected address should support the life being planned, not be expected to determine its tax treatment.
As a planning practice, maintain separate totals for Singapore, Florida, each other relevant U.S. state and other countries. Keep a second calculation for days potentially counted under Singapore employment rules. These are administrative recommendations, not a declaration that every jurisdiction measures days identically.
For each journey, record departure and arrival dates, locations, travel purpose and whether employment continued during an absence. Retain itineraries, boarding passes, passport records and corresponding calendar entries. When dates differ between documents, preserve the discrepancy and ask the adviser how to treat it rather than choosing whichever produces the preferred total.
Monthly reconciliation is a useful household discipline. Compare planned travel with completed travel, then update the rest of the year's calendar. Before a substantial itinerary change, review its implications across all relevant calculations, including consecutive-year patterns.
For a buyer weighing Forté on Flagler West Palm Beach, the same discipline can inform the occupancy plan. Consider who will use the home, when family visits are expected and how business travel may interrupt longer stays. Those practical questions belong alongside the purchase decision.
Consistent records should describe the household's circumstances accurately, not manufacture an appearance of permanence. Keep an organized file of address changes, residence-related correspondence, occupancy information and adviser instructions. Where documents serve different purposes, ask which address belongs on each rather than assuming one address should appear everywhere.
Retain a dated explanation when arrangements change. A planned relocation, a delayed move and a seasonal stay are different narratives; the file should reflect what actually occurred. Travel evidence should remain reconcilable with the household's account of where it lived.
Whether the eventual choice is in Palm Beach Gardens or Mr. C Residences West Palm Beach, record consistency is a recommended administrative discipline, not a complete legal domicile test. Ask counsel which facts and documents matter to the jurisdictions involved.
Singapore nonresident employment income for work lasting 61-182 days is generally taxed at 15% or resident rates, whichever produces the higher tax. A nonresident exercising employment for 60 days or fewer in a calendar year may qualify for a short-term employment-income exemption, subject to conditions. Exclusions include directors and specified professionals, so a short visit should not automatically be budgeted as exempt.
A considered two-city plan brings these questions together without conflating them: where the household wants to live, how travel will be recorded, which residency rules apply and what the resulting treatment means. Revisit the plan when employment or family circumstances change, not only when another flight is booked.
Explore residences for a thoughtfully planned South Florida chapter with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA foreigner generally qualifies as a Singapore tax resident after staying or working there for at least 183 days in the preceding calendar year. This is not an arbitrary rolling twelve-month test.
No. Multi-year concessions and the treatment of qualifying temporary overseas absences can affect the result.
They qualify as tax residents when they normally reside in Singapore, except for temporary absences. Their analysis should not automatically follow a foreigner's day-count approach.
A three-consecutive-year concession can apply despite fewer than 183 days in the first or third year. A qualifying employment period spanning two calendar years can also establish residency when the total stay or employment period reaches at least 183 days.
For an employee based in Singapore, employment-day calculations include weekends and public holidays. Counting only working days can misstate the relevant total.
Certain temporary overseas absences, including vacations and business trips, can count under the applicable Singapore employment rules. Record physical location separately and have the employment-day treatment reviewed.
Do not treat that number as a universal Florida domicile formula. Obtain separate advice on Florida domicile, applicable state residency tests and related tax questions.
As a recordkeeping practice, retain itineraries, boarding passes, passport records and calendar entries. Reconcile completed travel regularly and keep physical-presence totals separate from Singapore employment-day calculations.
It is generally taxed at 15% or resident rates, whichever produces the higher tax. Residency classification and the applicable employment period need separate review.
No. A short-term employment-income exemption may apply subject to conditions, with exclusions including directors and specified professionals.