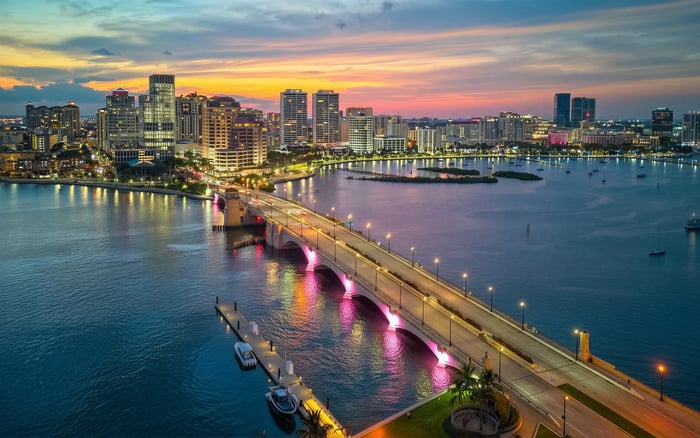
For a Sydney family establishing a Palm Beach Gardens home, residency planning requires three distinct reviews: U.S. federal tax residency, Australian tax residency, and Florida domicile. A coordinated travel calendar and an accurate record of daily life matter more than a single day-count target.
For a Sydney family considering Palm Beach Gardens, the residence is the visible part of a much larger decision. Behind the purchase are travel commitments, family arrangements, business responsibilities, and records that should reflect the same reality. The family office's task is to coordinate those details without mistaking a desirable address for a completed residency transition.
Three concepts must remain separate: U.S. federal tax residency, Australian tax residency, and Florida domicile. Each asks different questions. Florida has no individual state income tax, but that does not remove federal exposure. Living abroad does not necessarily end Australian residency. Establishing Florida domicile is not simply a matter of spending six months there.
A purchase at The Ritz-Carlton Residences® Palm Beach Gardens should therefore form part of a broader plan for how the family intends to live. The property can support that plan; it cannot, on its own, determine the tax consequences.
The substantial presence test generally requires both at least 31 days in the United States during the current calendar year and 183 weighted days across that year and the preceding two years, subject to exceptions. The calculation includes all current-year days, one-third of the preceding year's days, and one-sixth of the second-preceding year's days.
That weighting makes a current-year-only dashboard inadequate. In a hypothetical example, 120 countable days in each of three consecutive years produces a weighted total of 180 in the third year: 120 plus 40 plus 20. Four additional countable days in that third year would raise the total to 184. Spending fewer than 183 days in the United States in the current year is not an automatic federal safe harbor.
Physical presence at any time during a day generally counts as a full day. Arrival and departure dates therefore deserve the same attention as nights spent at home. Certain exclusions exist, including qualifying transit of less than 24 hours between two places outside the United States. Ordinary Florida visits, however, should not be treated as excluded transit.
The calendar must capture time across the entire country. A business stop elsewhere in the United States belongs alongside time in Palm Beach Gardens. Keep confirmed travel separate from proposed travel, and recalculate before accepting an additional trip.
Florida has no general 183-day requirement for establishing domicile. The central question is whether a person has established a home with the present intention of keeping it permanently. That differs from both the federal substantial presence calculation and Australian residency tests.
A family office should not apply federal day-count rules indiscriminately to individual states. Where another U.S. state remains part of the family's living or business pattern, obtain a separate assessment of that state's rules. A national travel total answers a different question from a state-specific review.
U.S. resident aliens generally face federal taxation on worldwide income. Florida's absence of individual income tax is therefore one feature of the destination, not a conclusion about the family's overall tax position. Cross-border advisers should review the projected calendar before the family commits to its intended pattern of stays.
Australian residency is not determined solely by counting days. The framework includes ordinary-concepts residency, domicile, and the 183-day test. Physical presence, intentions, family and business ties, assets, and social and living arrangements all inform the ordinary-concepts assessment.
Under the Australian 183-day test, presence for at least 183 days in an income year generally establishes residency unless the Commissioner is satisfied that the person's usual place of abode is outside Australia and they do not intend to reside in Australia. The reverse is not an automatic exit rule: spending 183 days outside Australia does not, by itself, end residency.
For someone with an Australian domicile, establishing a permanent place of abode outside Australia is central to the domicile test. Overseas accommodation, intended and actual duration abroad, and continuing Australian connections matter. The family office should document what changes in practice: where family life takes place, how the Sydney home will be used or maintained, and how business commitments will be managed.
If the search extends to Alba West Palm Beach, the question remains unchanged: how will the chosen residence function in the family's actual living arrangements? Acquisition alone does not settle Australian residency.
A Florida domicile file should be an accurate record, not a collection of disconnected formalities. Supporting evidence can include a Florida home, driver's license, vehicle registration, banking relationships, and community connections. Homestead exemption and voter registration may also be relevant where the individual is eligible. Neither should be assumed available simply because a residence has been purchased.
A resident may file a sworn Declaration of Domicile with the circuit-court clerk in the county of residence. Palm Beach Gardens is in Palm Beach County. Treat the declaration as supporting evidence of the family's genuine circumstances, not a substitute for them.
Make it an administrative discipline to review addresses and residency descriptions across relevant records. Differences may have legitimate explanations, but those explanations should be documented. Consistency means accurately recording the same life across different systems-not changing documents to imply circumstances that do not exist.
The most useful property brief connects the residence to ordinary family life. Ask how much time the family genuinely expects to spend there, which commitments will bring it back to Sydney, and how business travel could alter the projected U.S. total. Those answers should guide both the home search and discussions with advisers.
When comparing Mr. C Residences West Palm Beach with a Palm Beach Gardens option, keep the intended use explicit. A seasonal base and a home intended to be kept permanently represent different circumstances. Neither a project's name nor its purchase price replaces evidence of actual use and intention.
Assign responsibility for maintaining the travel ledger, retaining supporting travel records, and updating projected stays. Keep the preceding two years of U.S. presence available alongside current-year actuals. Schedule reviews when itineraries, living arrangements, or family commitments change, rather than relying solely on a year-end reconciliation.
Maintain a separate domicile file and an Australian-ties review, then have the relevant advisers assess them together. These are planning controls, not guarantees of a particular residency outcome. Individual tax and legal advice should determine how the rules apply to each family member.
The strongest relocation plan is one in which the home, calendar, intentions, and records tell a consistent and truthful story.
For a discreet conversation about a residence suited to your family's South Florida plans, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA home can support evidence of living arrangements and domicile, but buying it does not independently settle U.S. federal or Australian tax residency.
Florida has no general 183-day domicile requirement. Domicile centers on establishing a home with the present intention of keeping it permanently.
It generally requires at least 31 current-year U.S. days and 183 weighted days across three years, subject to exceptions. Count all current-year days, one-third of preceding-year days, and one-sixth of second-preceding-year days.
Physical presence at any time during a day generally counts as a full day. Exceptions exist, but should not be assumed for ordinary Florida visits.
Yes. The calculation measures U.S. presence nationally, not just days in Florida or Palm Beach Gardens.
No. Weighted days from the preceding two years can bring the total to the substantial presence threshold even with fewer than 183 current-year days.
No. Australian residency also considers domicile, intentions, continuing ties, and living arrangements, rather than relying solely on time abroad.
No. U.S. resident aliens generally face federal taxation on worldwide income, regardless of Florida's lack of individual state income tax.
Supporting evidence can include a Florida home, driver's license, vehicle registration, banking relationships, community connections, and a Declaration of Domicile. Homestead exemption and voter registration may also be relevant where eligible.
A resident may file the sworn declaration with the circuit-court clerk in Palm Beach County. It supports, but does not replace, evidence of genuine domicile.