For Miami waterfront buyers, the strongest purchase is not simply the most compelling residence. It is the one whose closing timetable, deposit obligations and documented ownership requirements align with the buyer’s liquidity and intended title structure.
For a cash buyer, the appeal of a Miami waterfront residence extends beyond the view. The purchase must also fit a preferred timetable, a deliberate ownership structure and a plan for moving capital. The most suitable residence is not necessarily the one with the most dramatic arrival. It is the one whose contractual requirements align with the buyer’s priorities.
Cash readiness and closing flexibility are distinct. Available funds do not establish permission to take title through an LLC or trust, nor do they give a purchaser control over a building’s completion. The meaningful comparison is transaction-specific: the residence, its purchase agreement, applicable association requirements and the buyer’s intended titleholder.
Begin with three decisions: when possession is needed, how much capital can be committed before closing and who should hold title. Those answers give a waterfront shortlist a clear purpose.
A completed resale deserves first consideration when the priority is a negotiated closing date rather than a future delivery milestone. A 30-45-day cash closing can serve as an initial planning estimate when entity formation and wire documentation are prepared in advance. It is not a commitment from a seller, building or closing agent.
Pre-construction follows a different rhythm. Miami luxury projects commonly require staged deposits totaling 30-50% of the purchase price, with the balance paid in cash or financed at closing. Percentages and milestones vary by contract. Review the actual schedule rather than assume a familiar deposit pattern applies everywhere.
Pre-construction closing depends on completion and the purchase agreement’s closing requirements; immediately available cash cannot, by itself, accelerate delivery. For a buyer coordinating a relocation or a second-home calendar, that distinction may matter more than the appeal of buying new.
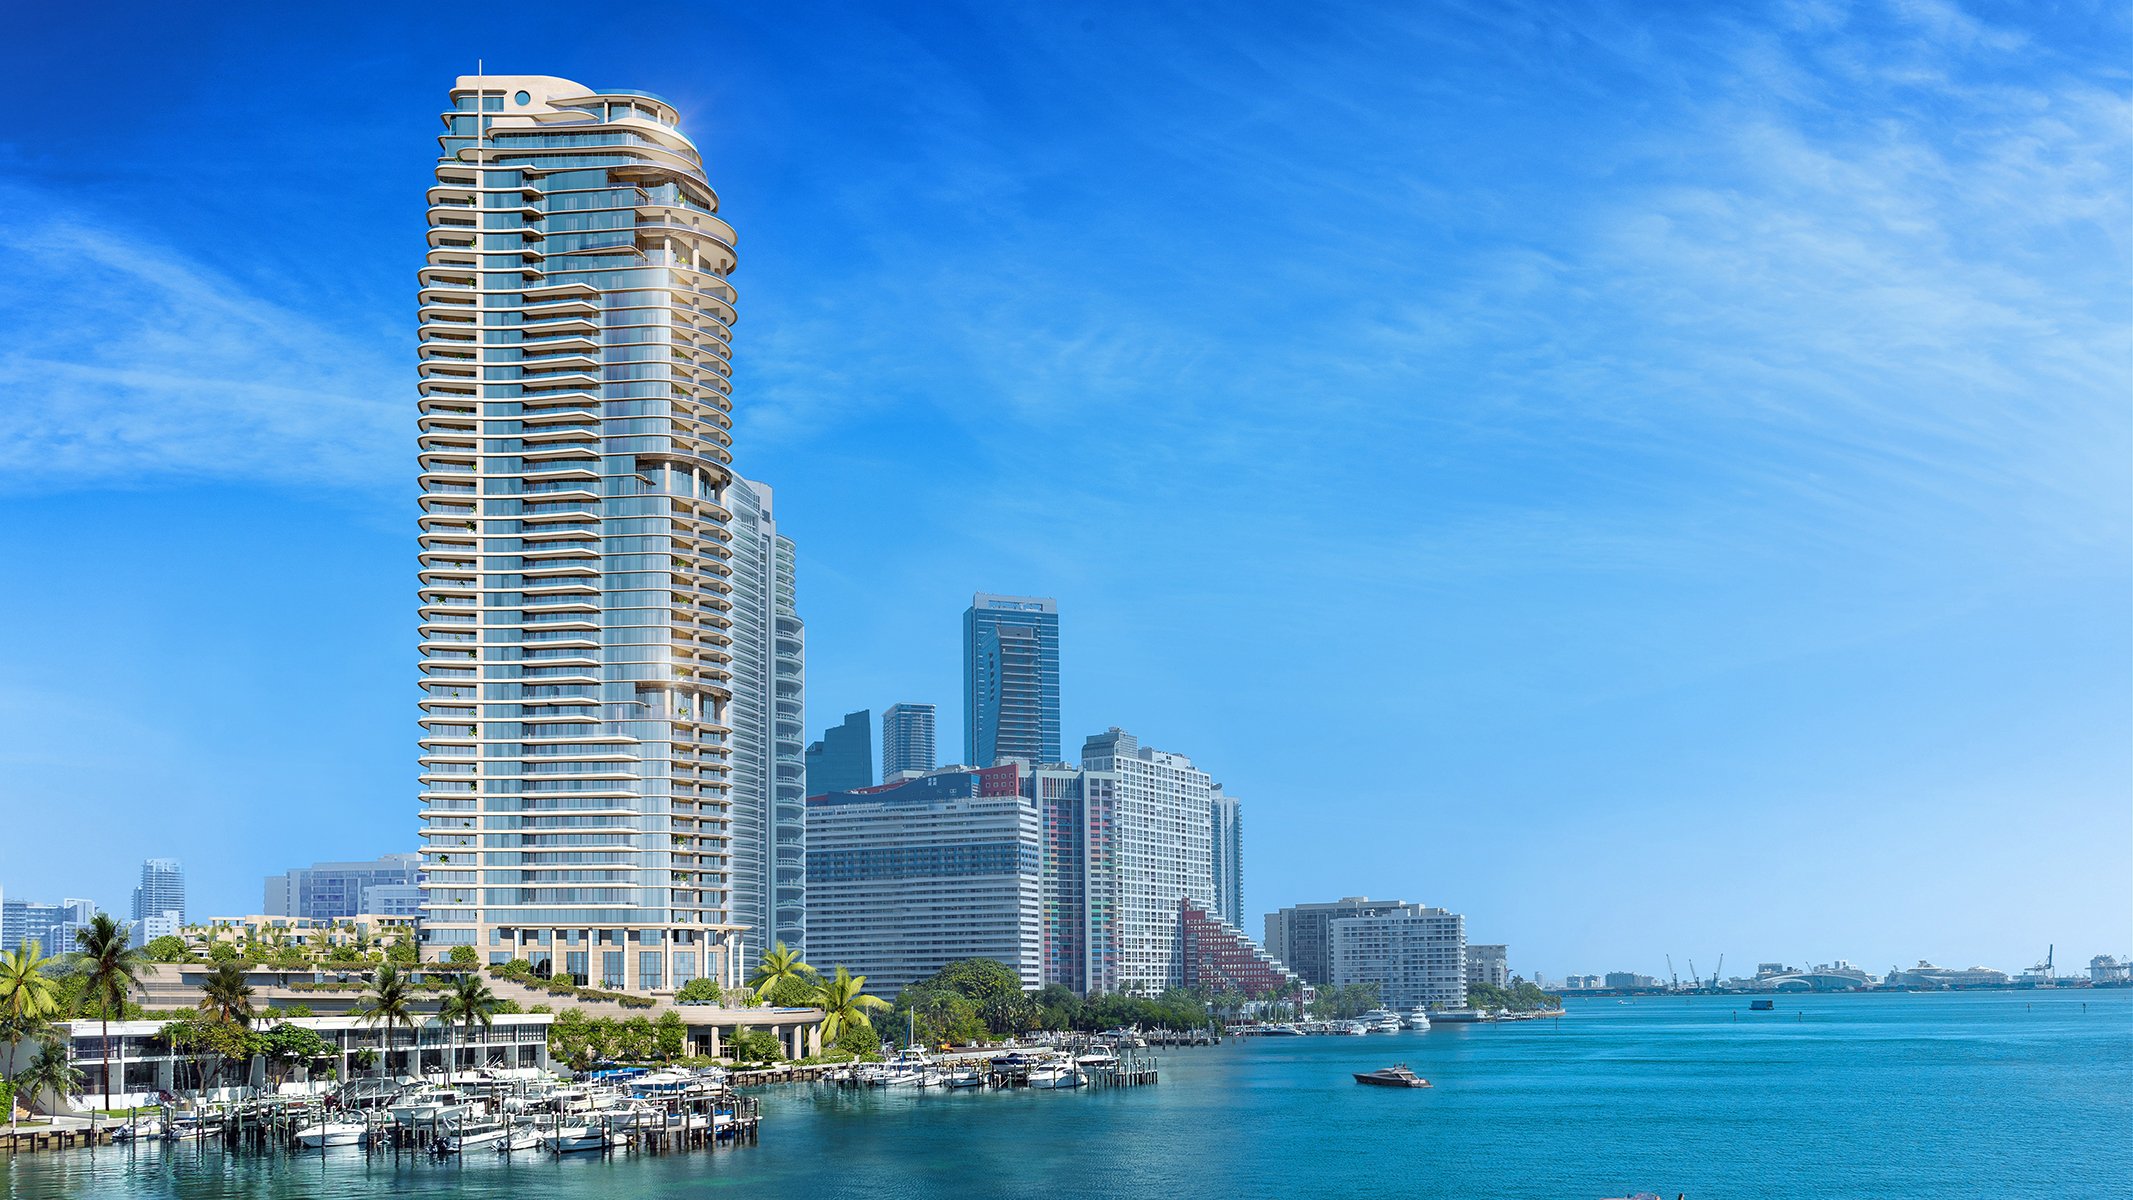
A buyer considering Una Residences Brickell should assess the specific offering against the same questions: which transaction type is available, what triggers closing and whether the documented timetable matches the intended use. A project name alone cannot answer them.
LLCs, trusts and land trusts are proposed ownership structures, not assumed building privileges. Before signing, have counsel review the purchase agreement and applicable association documents for the intended titleholder. Establish which approvals, disclosures and supporting documents are required, and obtain transaction-specific confirmation before relying on that structure.
The review should distinguish taking title in the intended entity from signing personally and requesting a change later. Ask counsel whether the agreement permits that sequence and whether consent or conditions apply. The closing plan should not depend on a future change that remains unaddressed.
For a Miami Beach search that includes The Perigon Miami Beach, ownership compatibility belongs alongside layout and outlook. The question is not whether luxury residences generally accommodate entities, but whether the particular purchase can close in the proposed name under its governing documents.
Entity selection also warrants individualized legal and tax advice. Privacy preferences, family planning and investment objectives should guide the discussion, without assuming one structure suits every purchaser.
Have proof of funds ready when submitting an offer. That preparation also makes it easier to discuss closing timelines and ownership-structuring requests before committing to a particular residence.
For international purchasers, readiness extends beyond the account balance. Transactions can involve source-of-funds, ownership-structure and wire-documentation checks. Coordinate early with counsel and the closing team to establish what they need, who will sign and how funds will reach escrow. Cash does not remove those checks.
When comparing an offering at Aria Reserve Miami with another candidate, ask the same operational questions of each transaction. What remains outstanding before closing? Which documents must be accepted first? Can the proposed signing and funding arrangements accommodate the requested date? Compare the answers rather than assume cash delivers identical flexibility everywhere.
Buyers who want financing available as a backup should engage a lender offering foreign-national programs early. Explore that option alongside the purchase plan, not as a closing deadline approaches.
For a cash resale condo, approximately 1-1.5% of the purchase price is a preliminary buyer closing-cost estimate, primarily covering title insurance, recording fees and prorations. Treat it as a budgeting reference-not an all-inclusive quote or a figure that automatically applies to new development.
Request a transaction-specific estimate before finalizing the capital allocation. Have the closing team identify what is included and what falls outside the estimate. The aim is to distinguish the purchase balance from every other amount the buyer must arrange to pay.
International buyers should also account for currency risk, particularly when deposits and the final balance fall at different times. A purchase fully funded in one currency still requires planning for its dollar-denominated obligations. Potential FIRPTA withholding on a later sale belongs in the longer-term discussion with tax counsel; it should not be confused with a current buyer closing charge.
An all-cash offer is no substitute for property review. Waterfront purchases still require diligence on title, applicable condominium documents, surveys and seawall condition. The scope should reflect the property being purchased, not the absence of a lender.
If Onda Bay Harbor is under consideration, request the documents and inspections relevant to the specific residence and its waterfront setting. Assess physical diligence separately from whether the proposed entity can take title. Both require satisfactory answers.
For waterfront single-family alternatives, inspections should address the seawall, dock, pests and flood risk before closing. A willingness to fund promptly should not reduce the review to a formality. A well-negotiated timetable preserves enough time to understand the asset while keeping the requested closing date realistic.
Foreign nationals generally do not need U.S. residency, a visa, a green card or a Social Security number to purchase Miami residential property, subject to applicable restrictions. Confirm eligibility for the specific buyer and transaction with counsel rather than assume unrestricted access.
Remote or mail-away closings can involve funds wired to escrow and documents notarized internationally. Confirm the accepted arrangements in advance, especially when an entity and overseas signatories are involved.
The best residence for these priorities ultimately satisfies four tests: a workable timetable, manageable cash commitments, confirmed titleholder requirements and satisfactory waterfront diligence. Resolve those points before treating closing flexibility as a reason to choose one address over another.
For a discreet conversation about aligning a Miami waterfront search with your closing and ownership priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe specific transaction should offer a workable closing timetable, manageable funding obligations and requirements compatible with the intended titleholder. Cash alone does not establish flexibility.
A 30–45-day window is an initial planning estimate when entity formation and wire documentation are prepared in advance. The actual timetable depends on the transaction and is not guaranteed.
No, available cash does not by itself give the buyer control over delivery. Pre-construction closing depends on completion and the purchase agreement’s closing requirements.
Staged deposits commonly total 30–50% of the purchase price, with the balance paid in cash or financed at closing. The actual percentages and milestones depend on the contract.
The proposed structure must be reviewed against the purchase agreement and applicable association requirements. Do not assume that a particular building accepts LLCs, trusts or land trusts.
Yes, cash buyers should prepare proof of funds when submitting an offer. International transactions may also require source-of-funds, ownership-structure and wire documentation.
Approximately 1–1.5% of the purchase price is a preliminary estimate, primarily for title insurance, recording fees and prorations. Obtain a transaction-specific estimate rather than treating that range as all-inclusive.
Foreign nationals generally do not need U.S. residency, a visa, a green card or a Social Security number to purchase Miami residential property. Applicable restrictions still require review.
Remote or mail-away closings can involve wiring funds to escrow and notarizing documents internationally. Confirm accepted signing and funding arrangements with the closing team in advance.
Review title, applicable condo documents, surveys and seawall condition as relevant to the property. Waterfront single-family inspections should also address the dock, pests and flood risk.