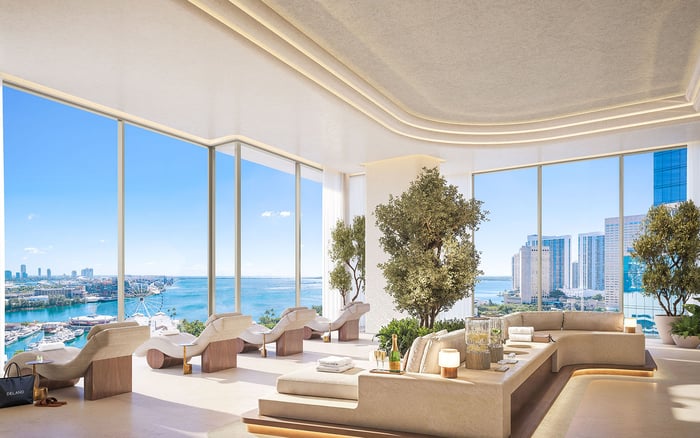
A document-led framework for evaluating luxury condominium candidates in Miami’s urban neighborhoods, with nearby alternatives clearly distinguished and no verified ranking of reserve strength or assessment risk.
For a luxury condominium buyer, predictability is part of the amenity package. A well-managed arrival and thoughtfully designed common spaces matter. So does knowing how the building will fund its next major obligation. In Downtown Miami, Wynwood, and the Design District, the decisive question is not simply what ownership costs each month. It is how clearly those costs connect to reserves, insurance, and future capital needs.
The information available here does not substantiate a ranked list of five active residences within those three neighborhoods or establish any candidate’s financial superiority. The four named candidates below are starting points for investigation, with nearby alternatives identified explicitly. Active availability, reserve adequacy, insurance terms, and assessment exposure require purchase-specific verification.
A place on a shortlist is an invitation to investigate, not a guarantee against additional charges. The strongest purchase decision pairs the desired lifestyle with a clear account of the building’s obligations.
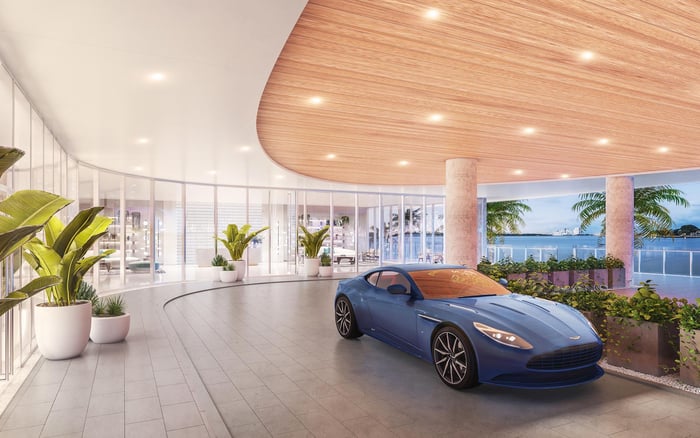
When considering Aston Martin Residences Downtown Miami, apply the same document requests used elsewhere. A recognizable project name should neither change the standard of financial review nor imply a particular reserve position.
Request the applicable association budget, reserve information, insurance documents, and assessment history before drawing conclusions about ownership costs. Confirm availability for the particular residence rather than treating inclusion here as an active-listing confirmation.
The Residences at Mandarin Oriental, Miami belongs in a broader urban-Miami comparison for buyers willing to consider Brickell Key rather than limit their search to Downtown Miami, Wynwood, and the Design District. Its branded-residence identity is a reason to examine the offering, not evidence of stronger association finances.
Before giving it priority, request the applicable budget, reserve-funding information, and master-policy terms. Distinguish the residential experience on offer from the financial commitments supporting it. Neither should stand in for the other.
St. Regis Residences Miami is another candidate for a search extending into Brickell. Newer development does not establish lower assessment risk, and a brand name does not answer questions about reserves, insurance, litigation, or pending charges.
Evaluate those subjects together rather than treating them as separate closing formalities. For a buyer prioritizing predictable ownership, the relevant advantage would be clear documentation and understandable funding obligations-not an assumed financial benefit attached to the name.
The Standard Residences, Midtown Miami is a Midtown candidate adjacent to Wynwood and the Design District, not a substitute for either neighborhood. It merits consideration when proximity serves the buyer’s lifestyle and the search allows that geographic flexibility.
Review operating and reserve contributions separately, then examine how the association intends to fund major components. Building scale alone does not establish insurance transparency or protection from assessments.
Downtown Miami, Wynwood, and the Design District should remain distinct searches. Brickell, Brickell Key, and Midtown may offer relevant alternatives, but convenience does not make them interchangeable. Establish which locations satisfy the purchase brief before comparing carrying costs.
For Wynwood and Design District searches, identify the specific condominium and association before making comparisons. A neighborhood description cannot substitute for building-specific financial information. Compare the obligations attached to a particular residence, not the general appeal of its surrounding district.
A Structural Integrity Reserve Study, or SIRS, evaluates funding needs for major building components, including roofs and load-bearing structural elements. Ask which study requirements apply to the particular condominium rather than assuming that every candidate has identical obligations.
For a buyer, the central question is how the applicable study connects to the association’s budget and reserve funding. Request the study, current budget, reserve information, assessment history, and association records together. A balance viewed without its corresponding obligations offers an incomplete picture.
Monthly dues alone cannot establish financial strength. Association charges fund operating expenses, reserves, and shared services. In Downtown buildings, those charges may include security, front-desk staffing, pools, fitness facilities, common-area insurance, utilities, and reserves, with inclusions varying by building.
Compare what the dues cover before comparing their size. A lower charge is not inherently preferable when the underlying funding commitments remain unclear.
Insurance transparency means more than confirming that a master policy exists. Review hurricane, windstorm, and flood exposure, then request policy limits, exclusions, deductibles, and renewal information. Those details turn a broad assurance of coverage into a more useful discussion of ownership costs and exposure.
Building insurance is an association expense. Changes in master-policy premiums can therefore affect owners’ carrying costs, even when their individual use of the property remains unchanged.
A buyer evaluating The Residences at Mandarin Oriental, Miami should ask the same coverage questions as a buyer considering any other condominium. Branding does not replace policy review, and an attractive monthly budget should not end the inquiry into renewal exposure.
New-construction and branded offerings can be compelling lifestyle choices. Neither characteristic demonstrates adequate reserves, favorable insurance terms, or immunity from surprise assessments. Keep the residence’s appeal separate from conclusions about association finances.
For St. Regis® Residences Brickell, as for other candidates, ask which financial documents apply to the contemplated purchase and have the obligations explained before relying on a carrying-cost estimate.
Older condominium buildings can also face additional expenses associated with structural requirements and reserve funding. Age deserves attention, but it is not a complete financial verdict. Evaluate the actual structural documentation, funding position, and assessment exposure rather than making a blanket judgment about an entire generation of buildings.
A special assessment is an additional association charge for repairs or capital improvements not covered by the regular budget or reserves. The objective is not to promise that one can never occur. It is to understand existing obligations and scrutinize how foreseeable needs are being funded.
Reserve adequacy, assessments, litigation, and insurance also matter in condominium financing and project review. Have the relevant association records examined alongside the proposed purchase, rather than treating financial due diligence as separate from choosing the home.
The most persuasive residence satisfies both tests: the life the buyer wants to lead and financial obligations the buyer can understand.
For a discreet discussion of Miami residences and a document-led purchase strategy, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. It identifies four candidates for further review, including nearby alternatives, without verifying current availability or ranking their association finances.
No. Review the budget, reserve study, assessment history, and association records together, including what the monthly charges actually cover.
A SIRS evaluates funding needs for major building components, including roofs and load-bearing structural elements. Confirm which requirements apply to the particular condominium.
Request master-policy limits, exclusions, deductibles, and renewal information. Review hurricane, windstorm, and flood exposure rather than simply confirming that coverage exists.
Yes. Building insurance is an association expense, so changes in master-policy premiums can affect owners’ carrying costs.
It is an additional association charge for repairs or capital improvements not covered by the regular budget or reserves.
Neither establishes adequate reserves, favorable insurance terms, or protection from assessments. Those conclusions require review of the applicable financial and insurance documents.
The Standard Residences, Midtown Miami is identified as a Midtown candidate adjacent to Wynwood and the Design District. Buyers should treat it as a nearby alternative rather than an interchangeable location.
They are alternatives to the title’s Downtown Miami, Wynwood, and Design District focus. Buyers should explicitly decide whether those locations satisfy their purchase brief.
Reserve adequacy, special assessments, litigation, and insurance are material considerations in condominium financing and project review.