A Downtown Miami condominium purchase deserves precision beyond the price. Understand how assessment installments, contractual allocations, proposed seller credits, and negotiated escrow holdbacks fit together before closing.
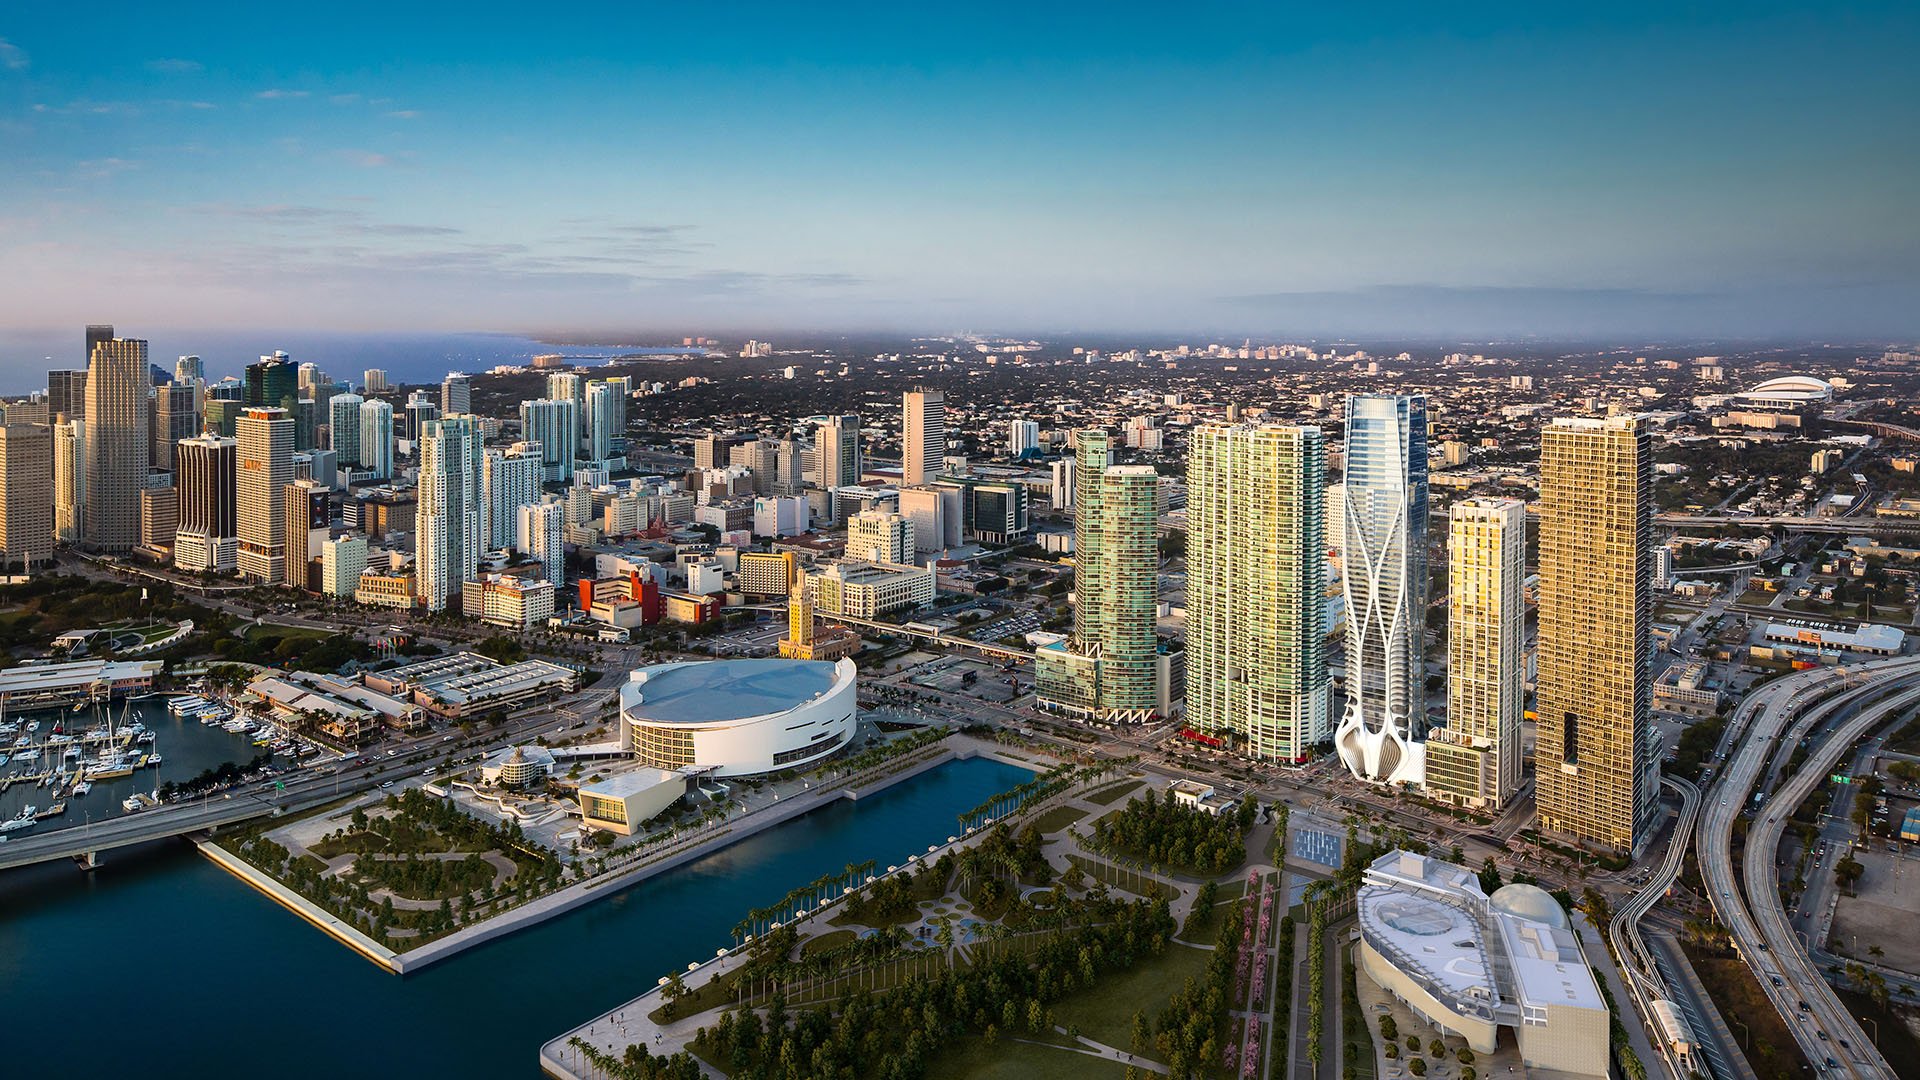
In Downtown Miami, choosing a luxury condominium is both a lifestyle decision and an exercise in financial precision. A residence may satisfy every personal preference, yet the purchase still calls for a separate review of association obligations: what is owed, when it becomes payable, and which party has agreed to fund it.
The central distinction is straightforward. A purchase contract allocates responsibility between buyer and seller; it does not necessarily limit the association’s collection rights. An assessment approved before signing is not automatically the seller’s entire obligation. Nor does a bill arriving after closing establish, by timing alone, the buyer’s contractual responsibility.
For buyers considering Aston Martin Residences Downtown Miami, that distinction belongs alongside the evaluation of the residence itself. This is a framework for reviewing a transaction, not a statement about assessments at that property or any project mentioned here.
Divide the assessment discussion into installments due before closing, installments due afterward, and assessments imposed between signing and closing. Each deserves explicit treatment in the agreement.
A condominium rider may assign pre-closing installments to the seller while allowing the parties to select responsibility for later installments. Read the actual form and its version carefully. An unchecked allocation box is not a harmless omission or an invitation to settle the issue later.
If the seller agrees to cover installments due after closing, review the rider’s payoff provisions. Do not assume that a promise to reimburse the buyer periodically satisfies the contract. The agreed payment mechanism should match the operative language.
Ask counsel to address intervening assessments expressly. The aim is to avoid arriving at closing with a newly imposed obligation that neither party believes is theirs. Disclosure review should likewise include relevant pending assessments, not merely invoices already received. Failure to disclose can leave the seller responsible under applicable rider provisions.
A total assessment balance is useful, but it does not describe the buyer’s cash-flow exposure. Request the installment schedule and reconcile it with the proposed closing date and contractual allocation.
A working schedule should identify:
The remaining amount and each installment’s due date.
Which installments fall before and after the anticipated transfer.
The party assigned to fund each obligation under the contract.
The proposed payment method and evidence needed to verify completion.
Keep regular assessments separate from special assessments. The estoppel’s regular-assessment information includes payment frequency, the paid-through date, and the next installment’s amount and due date. These details establish the immediate payment calendar; they do not replace a review of the special-assessment schedule.
If closing moves, revisit the schedule. A changed transfer date may shift installments to either side of closing under the agreed allocation. It may also require an updated estoppel.
A Florida condominium estoppel must itemize assessments and other amounts owed when it is issued. It must also identify additional assessments, special assessments, and other amounts scheduled to become due during its effective period.
The certificate is essential, but its scope has limits. Its effective period is finite, and it is not a guarantee that no further funding needs exist. A delayed closing may require a refreshed certificate rather than reliance on the original balance.
For a purchase under consideration at One Thousand Museum Downtown Miami, the review principle is the same: reconcile the certificate, the contract, and the payment schedule for that transaction. A project’s identity cannot answer a unit-specific allocation question.
Payoff verification matters because a buyer can be jointly and severally liable with the previous owner for unpaid assessments that became due before title transferred. A seller’s contractual promise and the association’s statutory ability to collect are distinct. Ask the closing team what evidence will confirm that the required payment was made.
A proposed seller credit should answer a precise question: what obligation is the concession intended to offset? Identify the relevant assessment, the negotiated amount, and who remains responsible for paying the association.
A credit is not synonymous with an association payoff. If the proposed structure leaves the buyer responsible for future installments, the buyer should understand the payment calendar and whether the negotiated concession adequately addresses that obligation.
Before relying on the arrangement, have counsel and the closing team review its treatment in the transaction documents. Where financing is involved, ask the lender to confirm whether the proposed credit is acceptable. Do not assume acceptance or any applicable limits.
The negotiation should also address discrepancies. Ask what happens if an updated estoppel or revised schedule changes the amount before closing. A clearly defined concession is more useful than a broad promise to make the buyer whole later.
An escrow holdback may be worth discussing when the parties want funds retained pending a defined assessment-related resolution. It is a proposal for the transaction team to evaluate-not an automatic closing solution or a substitute for required payoff provisions.
Before committing, ask counsel to document the proposed amount, who would hold it, the obligation it is intended to cover, and the evidence required for disbursement. The terms should also address release deadlines, disputed claims, any shortfall, and the return of unused funds.
Confirm that the proposed holder will accept the arrangement and, where relevant, that it is acceptable to the lender. Neither acceptance nor a standard assessment-holdback form should be presumed. Above all, do not assume retained funds prevent the association from pursuing an unpaid obligation.
The same document-first approach belongs in a broader search that includes Waldorf Astoria Residences Downtown Miami. Review the documents applicable to the contemplated purchase rather than importing assumptions from another residence or contract.
Beyond the estoppel, examine recent association agendas and minutes, budgets, financial statements, reserve information, and available engineering or structural documentation. These materials help frame questions about contemplated work and funding needs that a current balance alone cannot resolve.
Before proceeding, seek clear answers to three questions: what must be paid at closing, what remains payable afterward, and what future funding questions remain open? That clarity supports a more deliberate purchase without confusing an elegant residence with a fully resolved financial obligation. Transaction-specific legal and financing decisions belong with the buyer’s advisers.
For a considered approach to your Downtown Miami residence search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The purchase contract and condominium rider determine the allocation between buyer and seller; the levy date alone does not settle responsibility.
Separate installments due before closing from those due afterward, then match each to the contract’s allocation. Also address assessments imposed between signing and closing.
Do not assume a blank selection has no effect. Review the actual form and version with counsel and make the intended allocation explicit.
It itemizes assessments and other amounts owed when issued, along with additional amounts scheduled to become due during its effective period. Regular-assessment details include payment frequency, the paid-through date, and the next installment.
Not necessarily. An estoppel has a limited effective period, so a delayed closing may require an updated certificate and another review of installment dates.
A buyer can be jointly and severally liable with the previous owner for unpaid assessments that came due before title transferred. Contractual allocation does not eliminate the need to verify seller payoff.
No. A proposed credit and an association payoff are different arrangements, so the documents should identify who will pay the association and when.
Acceptance should not be assumed. Ask the lender and closing team to review the specific proposal before relying on it.
No. Any proposed holdback needs transaction-specific review, an accepting holder, and clear written funding and release terms; lender acceptance should also be confirmed where relevant.
Review association agendas and minutes, budgets, financial statements, reserve information, and available engineering or structural documentation. A current assessment balance does not establish future funding needs.