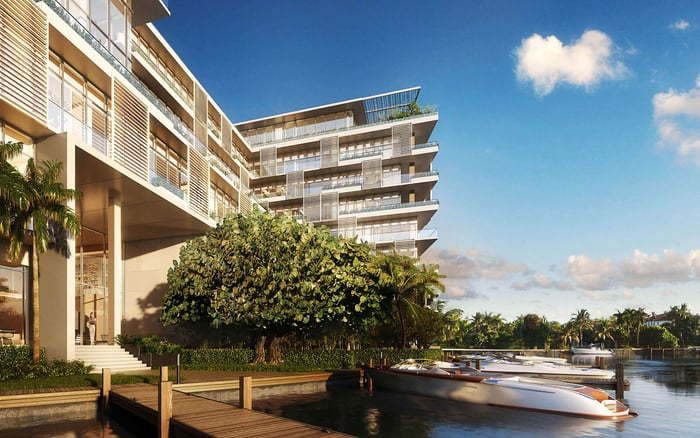
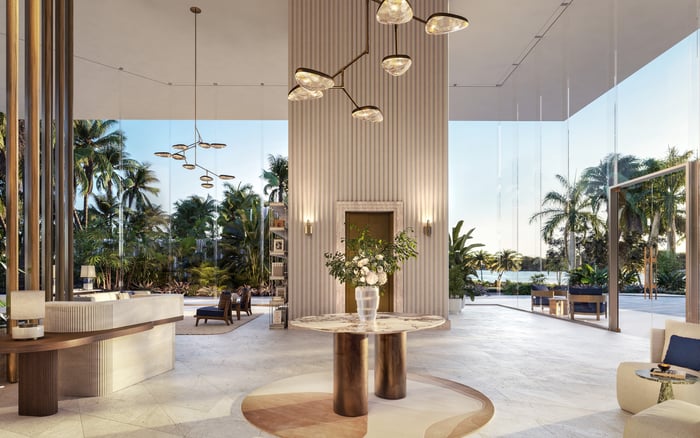
For prospective Perigon buyers, the first owner-controlled budget could clarify the relationship between quoted maintenance, service commitments, insurance and long-term funding. The opportunity is to evaluate the supporting documents, not assume that turnover means higher costs.
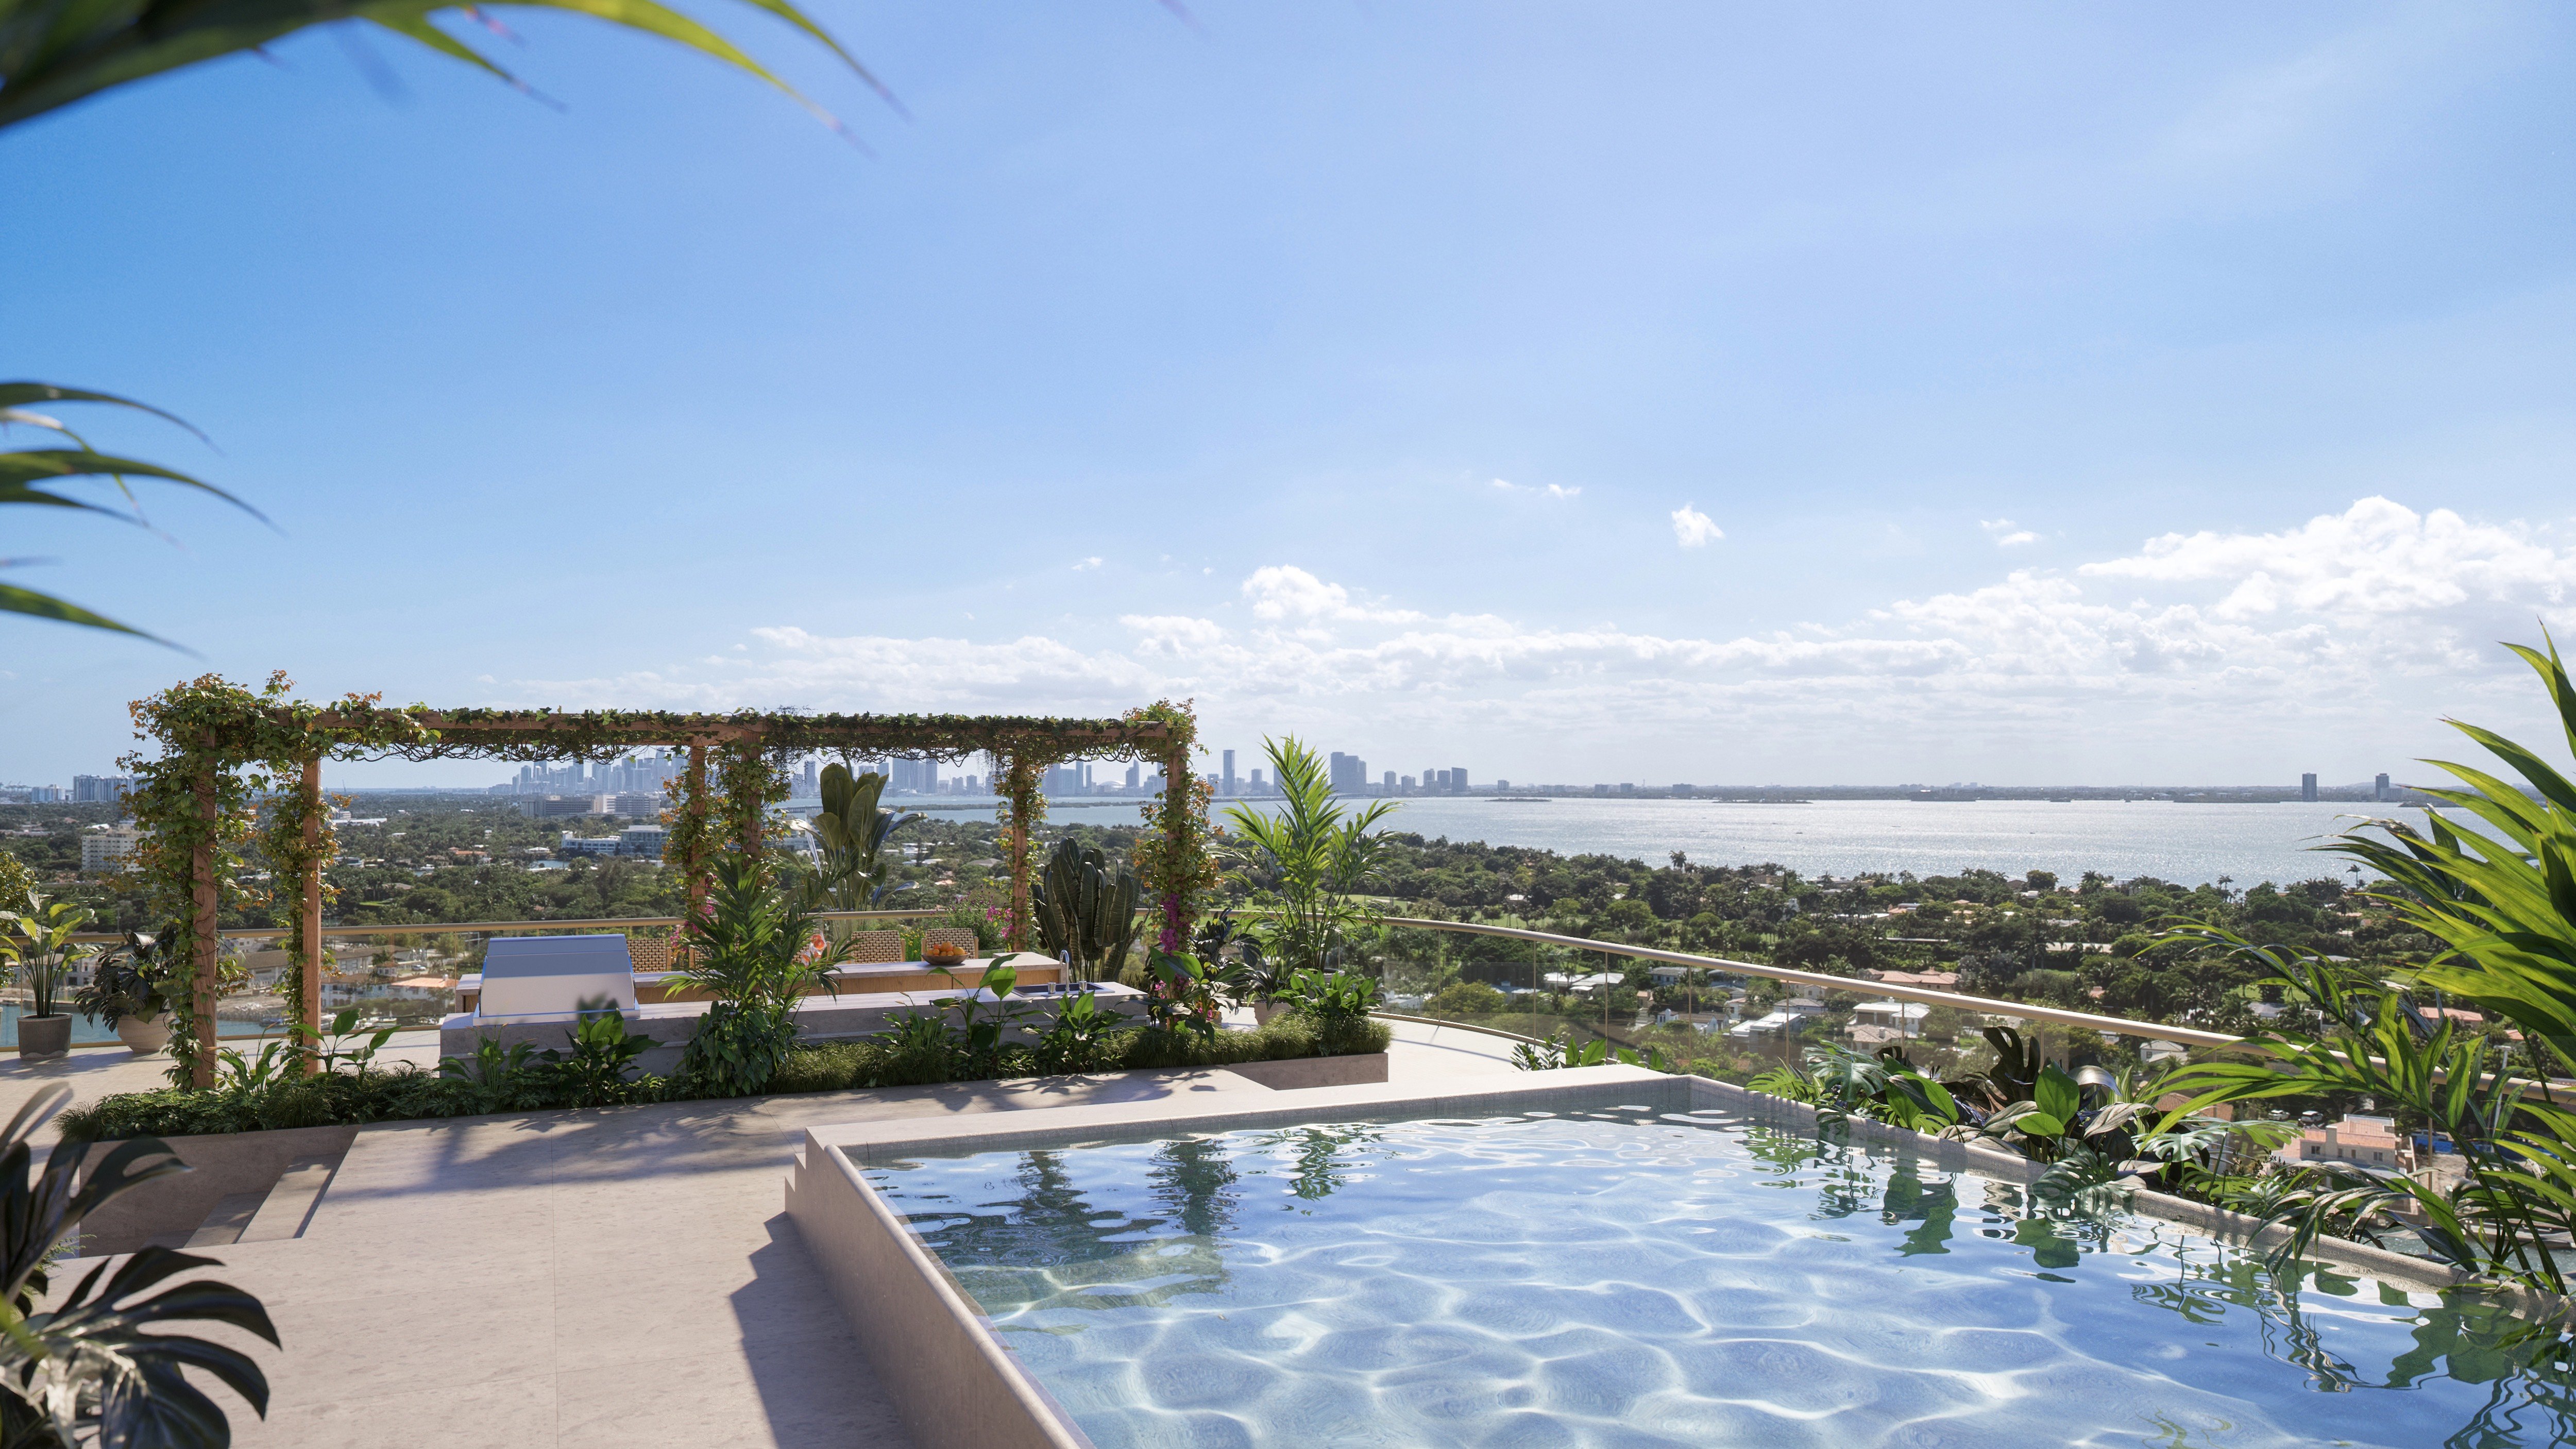
At The Perigon Miami Beach, the purchase decision extends beyond architecture and an oceanfront address. For a buyer considering a residence at 5333 Collins Avenue, the first budget adopted under owner control could clarify how the building’s service commitments translate into recurring expenses and long-term funding.
This is a prospective diligence question-not a statement that developer turnover has occurred or that an initial budget understates costs. The test is whether each material assumption can be explained, documented and tied to the residence being purchased.
A monthly charge is the starting point, not the conclusion. A well-supported budget could confirm earlier expectations, reveal different spending priorities or distinguish temporary opening expenses from recurring obligations. None of those outcomes should be presumed.
Developed by Mast Capital and Starwood Capital Group, The Perigon pairs OMA architecture with interiors by Tara Bernerd & Partners and landscape design by Gustafson Porter + Bowman. The residential program comprises approximately 73 luxury residences, generally ranging from two to four bedrooms and about 2,100 to 6,700 square feet of interiors, plus terraces.
For diligence purposes, these details frame questions; they do not determine assessments. Ask which landscaped areas, finishes, building systems and shared facilities the association will maintain, and which obligations fall to individual owners or other parties.
Do not divide a projected expense total by 73 and assume the result represents a residence’s assessment. Request the governing allocation schedule and the calculation for the specific home. The residence count provides context, not a substitute for the documents governing expense allocation.
Three advertised figures must be kept distinct. Average maintenance is quoted at $1.02 per square foot, but neither the billing period nor the square-footage denominator is established. It should therefore not be converted into a monthly ownership estimate or reconciled using interior-plus-terrace dimensions.
Separately, Apartment 1101, identified by MLS A11728995, carries a quoted monthly maintenance charge of $12,695. A different residence, 5333 Collins Avenue #W, has a quoted HOA fee of $12,530 per month.
These figures concern different residences; they are not two observations proving a fee increase. Neither establishes a building-wide rate or an adopted owner-controlled budget. Before relying on either, request written confirmation of the applicable period, expense allocation, inclusions and whether the amount is estimated or adopted.
A buyer also considering 57 Ocean Miami Beach should apply the same discipline to any comparison. Headline monthly charges are useful only after reconciling the residence allocation, service scope and expenses paid outside the association bill.
The quoted fee inclusions for #W encompass association management, amenities, common areas, insurance and structural maintenance, as well as parking, pools, sewer, security, trash and water. This is a useful starting point for questions, not a substitute for contracts or a detailed operating budget.
Start with management and staffing. Ask for the service schedule, staffing assumptions, contract terms and any separately charged services. Establish what the recurring assessment actually buys, including how service coverage is funded throughout the budget year.
Then examine maintenance and utilities. Request the assumptions behind common-area upkeep, pool operations, landscaping, water and sewer. Distinguish signed agreements from preliminary allowances, and ask whether the figures cover a full year of the intended operating program.
Insurance warrants a separate review. Ask for policy information, premiums, deductibles, covered property and exclusions, with professional advice on any coverage needed for the residence itself. An inclusion labeled insurance does not, by itself, explain the owner’s complete insurance exposure. Nor does an allowance establish the cost of a bound policy.
The objective is clarity about service, not simply the lowest charge. A smaller budget is not inherently better if it supports a different ownership experience.
The first owner-controlled budget could also clarify how current operations and future capital needs are presented. Look for a clear distinction between spending that maintains daily service and contributions intended for longer-term repair or replacement.
Request any applicable reserve study, funding schedule and supporting professional assessments. Ask which components are included, how contribution amounts were determined and what assumptions underpin timing and costs. A line labeled structural maintenance should not automatically be treated as evidence of a funded reserve program.
Keep the questions neutral. There is no basis here to assume deliberately minimized reserves, an inevitable special assessment or a particular increase after turnover. The useful inquiry is whether the funding approach is documented and whether unresolved items could affect the buyer’s obligations.
Have condominium counsel evaluate the governing documents and applicable requirements rather than relying on a generic turnover timeline or reserve deadline.
The most useful comparison would place the relevant developer-controlled budget beside the first owner-controlled version, with an explanation for each material change. Request that reconciliation when both documents are available, along with supporting financial statements and actual-versus-budget results where available.
For each difference, ask whether it reflects pricing, service scope, contract timing, reserve contributions or partial-year versus full-year operations. Identify any developer contributions, guarantees or temporary arrangements if they exist, and establish how they are treated. Their existence should never be assumed.
Separate recurring items from one-time expenditures. A transitional expense and an ongoing contract can affect the same year’s total while carrying different implications for subsequent ownership costs.
For a buyer whose Miami Beach shortlist also includes Faena House Miami Beach, this document-based approach provides a consistent method of evaluation. It does not imply that another property has the same governance status, allocation rules or service structure.
Before committing, assemble a residence-specific file: the applicable budget, assessment calculation, governing expense allocations, insurance information, reserve materials and available financial statements. Add relevant contracts and board materials where available, then ask counsel and financial advisers to identify unresolved obligations and assumptions.
If an owner-controlled budget is not yet available when the decision must be made, distinguish contractual commitments from projections and ask how future information will be communicated. The absence of a future document is not proof of a future problem, but an estimate should still be treated as an estimate.
The first owner-controlled budget could ultimately be reassuring. Its value would lie in showing how the desired standard of living is funded-with enough detail to support an informed purchase, rather than a prediction about fees.
For a discreet conversation about evaluating South Florida residences and ownership costs, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe Perigon is an oceanfront condominium development at 5333 Collins Avenue in Miami Beach.
The development partners are Mast Capital and Starwood Capital Group. OMA designed the building, with interiors by Tara Bernerd & Partners and landscape design by Gustafson Porter + Bowman.
No. It treats the first owner-controlled budget as a prospective diligence milestone, not as evidence that turnover has occurred.
It could clarify operating assumptions, service funding, insurance allowances and reserve contributions. A comparison with the relevant earlier budget would help explain any material differences.
No. It is a marketing benchmark whose billing period and square-footage denominator are not established, not an adopted association budget.
Apartment 1101, MLS A11728995, has quoted monthly maintenance of $12,695, while 5333 Collins Avenue W has a quoted monthly HOA fee of $12,530. These separate listing figures do not establish a fee increase or a building-wide rate.
The listing names management, amenities, common areas, insurance, structural maintenance, parking, pools, sewer, security, trash and water. Buyers should confirm the scope through budget and contract documents.
An increase should not be assumed. Buyers should evaluate documented changes in costs, service scope and funding rather than predict an outcome from turnover alone.
Request any applicable reserve study, funding schedule and supporting professional assessments. Ask which components are included and how the contributions were determined.
Compare residence-specific expense allocations, service inclusions, reserve funding and separately paid costs. Headline monthly charges alone do not establish equivalent ownership costs.