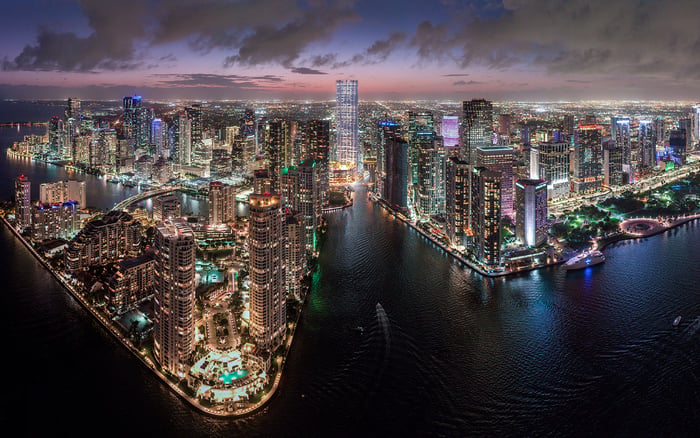
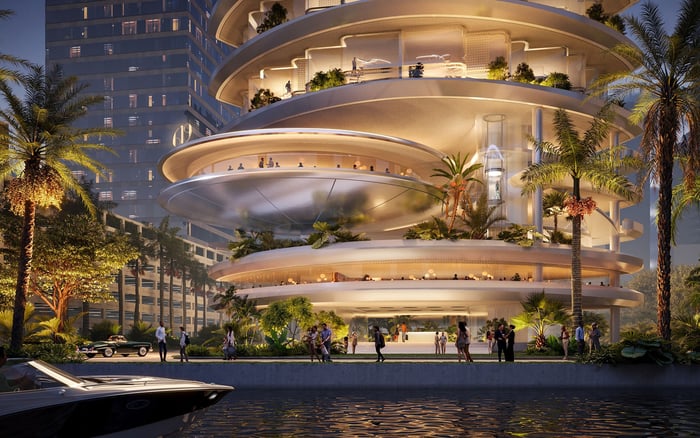
Baccarat Residences Brickell and 2200 Brickell invite different lifestyle choices, but the same financial discipline. Buyers should distinguish purchase installments from contract escalators, reconcile unit-specific assessments, and establish which services regular dues actually cover.

A luxury condominium purchase is also a commitment to an operating model. Beyond the residence itself, buyers are choosing how staffing, shared spaces, maintenance, and service will be funded over time. The useful comparison between Baccarat Residences Brickell and 2200 Brickell therefore begins with financial clarity-not the assumption that branded hospitality or boutique scale offers better value.
For a buyer weighing these two Brickell properties, neither identity, on its own, establishes a lower long-term cost. The buyer’s question is more precise: what does this particular residence contribute, what does that contribution cover, and what could change after closing?
For Baccarat, begin by requesting the intended residence’s current assessment disclosure and supporting budget. This comparison does not establish a verified monthly fee for either featured property, and a figure associated with one residence should not be treated as a building-wide quotation.
If sales materials, listings, or operating estimates present different figures, do not average them or treat them as interchangeable quotes. A meaningful comparison requires the same unit size, measurement basis, budget date, service inclusions, and reserve assumptions. Confirm whether each figure is a total monthly assessment or a per-square-foot estimate, and identify the area measurement used in any calculation.
Ask for a written reconciliation of differences among the sales presentation, unit disclosure, and operating estimate. The objective is not to select the more attractive number, but to establish which figure applies to the intended residence and what remains provisional.
At 2200 Brickell, the boutique proposition warrants its own financial review, not an assumed discount. Consider how the number of contributing homes affects the allocation of staffing and amenity expenses. A more intimate residential environment can be desirable without necessarily producing a lower monthly assessment.
For both properties, begin with the specific unit’s assessment rather than a generalized expectation about building type. Then ask how common expenses are allocated to that residence and which operations the assessment supports.
The number of homes is only one consideration alongside the scope of services and allocation of expenses. Boutique living and hospitality-led living are lifestyle preferences, not reliable shortcuts to ranking ownership costs.
Purchase deposits, purchase-price escalation clauses, and association assessment increases belong in separate parts of the buyer’s analysis. Each may affect cash flow, but they address different obligations.
Use the applicable purchase agreement to build a deposit calendar. Record the amount of each installment, its due date or milestone, and the balance payable at closing. Have counsel reconcile any differences between a sales summary and the agreement before relying on a payment schedule. Staged deposits are installments toward the purchase price, not evidence that the price or association assessment is increasing.
A purchase-price escalator raises a different question: does the contract permit the purchase price to change under specified conditions? Do not assume such a clause exists at either property. Have counsel identify any applicable adjustment language, explain what triggers it, and clarify any limits or buyer rights stated in the agreement.
Association increases require a separate review of the budget and governing documents. Do not assume an annual cap exists or that a purchase-price provision also protects the owner against future operating-cost increases.
For buyers considering Baccarat for its service proposition, the essential distinction is between availability and inclusion. A service presented as part of the residential experience should not automatically be treated as covered by regular dues.
Request a written service-inclusion schedule that distinguishes association-funded operations from services charged when used. Ask whether minimums, recurring charges, or separate arrangements apply; assume neither inclusion nor exclusion. Confirm which services are proposed and which are established in the applicable documents.
This distinction is equally useful when a search extends to Cipriani Residences Brickell: apply the same questions without carrying over another building’s fee assumptions.
The practical test is personal. Identify the services the household expects to use, establish how they are charged, and model those costs alongside the unit assessment. A compelling hospitality offering becomes a clearer ownership proposition when recurring and discretionary costs are separated.
Use maintenance, shared utilities, master building insurance, staffing, amenity operations, vendor contracts, administration, and reserves as a budget-review checklist. Establish the actual inclusions and allocation of each category for the intended residence rather than assuming they are identical across projects.
Request the current budget and unit-specific assessment together, noting whether either is preliminary. Review insurance assumptions, reserve contributions, and the scope of staffing and vendor commitments. Ask which expenses are fixed for a stated period, which may change at renewal, and how contractual adjustments would flow through to owners.
Next, examine provisions addressing developer subsidies, turnover, assessment increases, and special assessments. If a subsidy applies, establish its duration and how the budget would operate after it ends. Treat these as questions for document review, not assumptions about either building.
Also ask whether separate master-association or neighborhood charges apply. Do not attribute additional obligations to either featured development without confirmation in the relevant documents.
Finally, have the adviser preparing the comparison identify the date and status of every budget. An estimate should remain clearly labeled as an estimate throughout the decision process.
The disciplined conclusion is not that Baccarat or 2200 Brickell will cost less over time. Neither a brand name nor boutique positioning supplies the unit-level documents needed to support that judgment.
Either choice deserves an ownership model that separates purchase installments, regular assessments, discretionary services, and potential additional charges. Test changes as planning scenarios, not predictions, and keep unconfirmed items visible rather than treating them as zero. Then choose the experience whose financial obligations are as clearly understood as its lifestyle appeal.
For a considered approach to South Florida residential ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo verified monthly assessment is established here. Obtain the current disclosure for the intended residence and its supporting budget.
Match the unit size, measurement basis, budget date, service inclusions, and reserve assumptions. Request a written reconciliation rather than averaging incompatible figures.
No. Review the specific unit’s assessment and expense allocation rather than assuming boutique scale produces lower costs.
Use the applicable purchase agreement to identify installment amounts, dates, milestones, and the closing balance. Have counsel reconcile any differences from sales summaries.
No. Deposits are purchase-price installments, while a purchase-price escalator concerns contractual provisions that could change the price.
No. Counsel should review the applicable agreement for price-adjustment language and explain any triggers, limits, or buyer rights.
Availability does not establish inclusion. Request a written schedule separating association-funded services from separately charged offerings.
Request the current budget, unit-specific assessment, reserve and insurance assumptions, and service-inclusion schedule. Also review provisions concerning increases, subsidies, turnover, and special assessments.
No such obligation is established here for either property. Confirm any master-association or neighborhood charges in the relevant documents.
No. Build a unit-level ownership model and treat potential cost changes as planning scenarios rather than forecasts.