For nonresident buyers acquiring South Florida property through a U.S. entity, careful drafting should separate termination rights, restoration decisions, proceeds allocation, and federal withholding obligations.
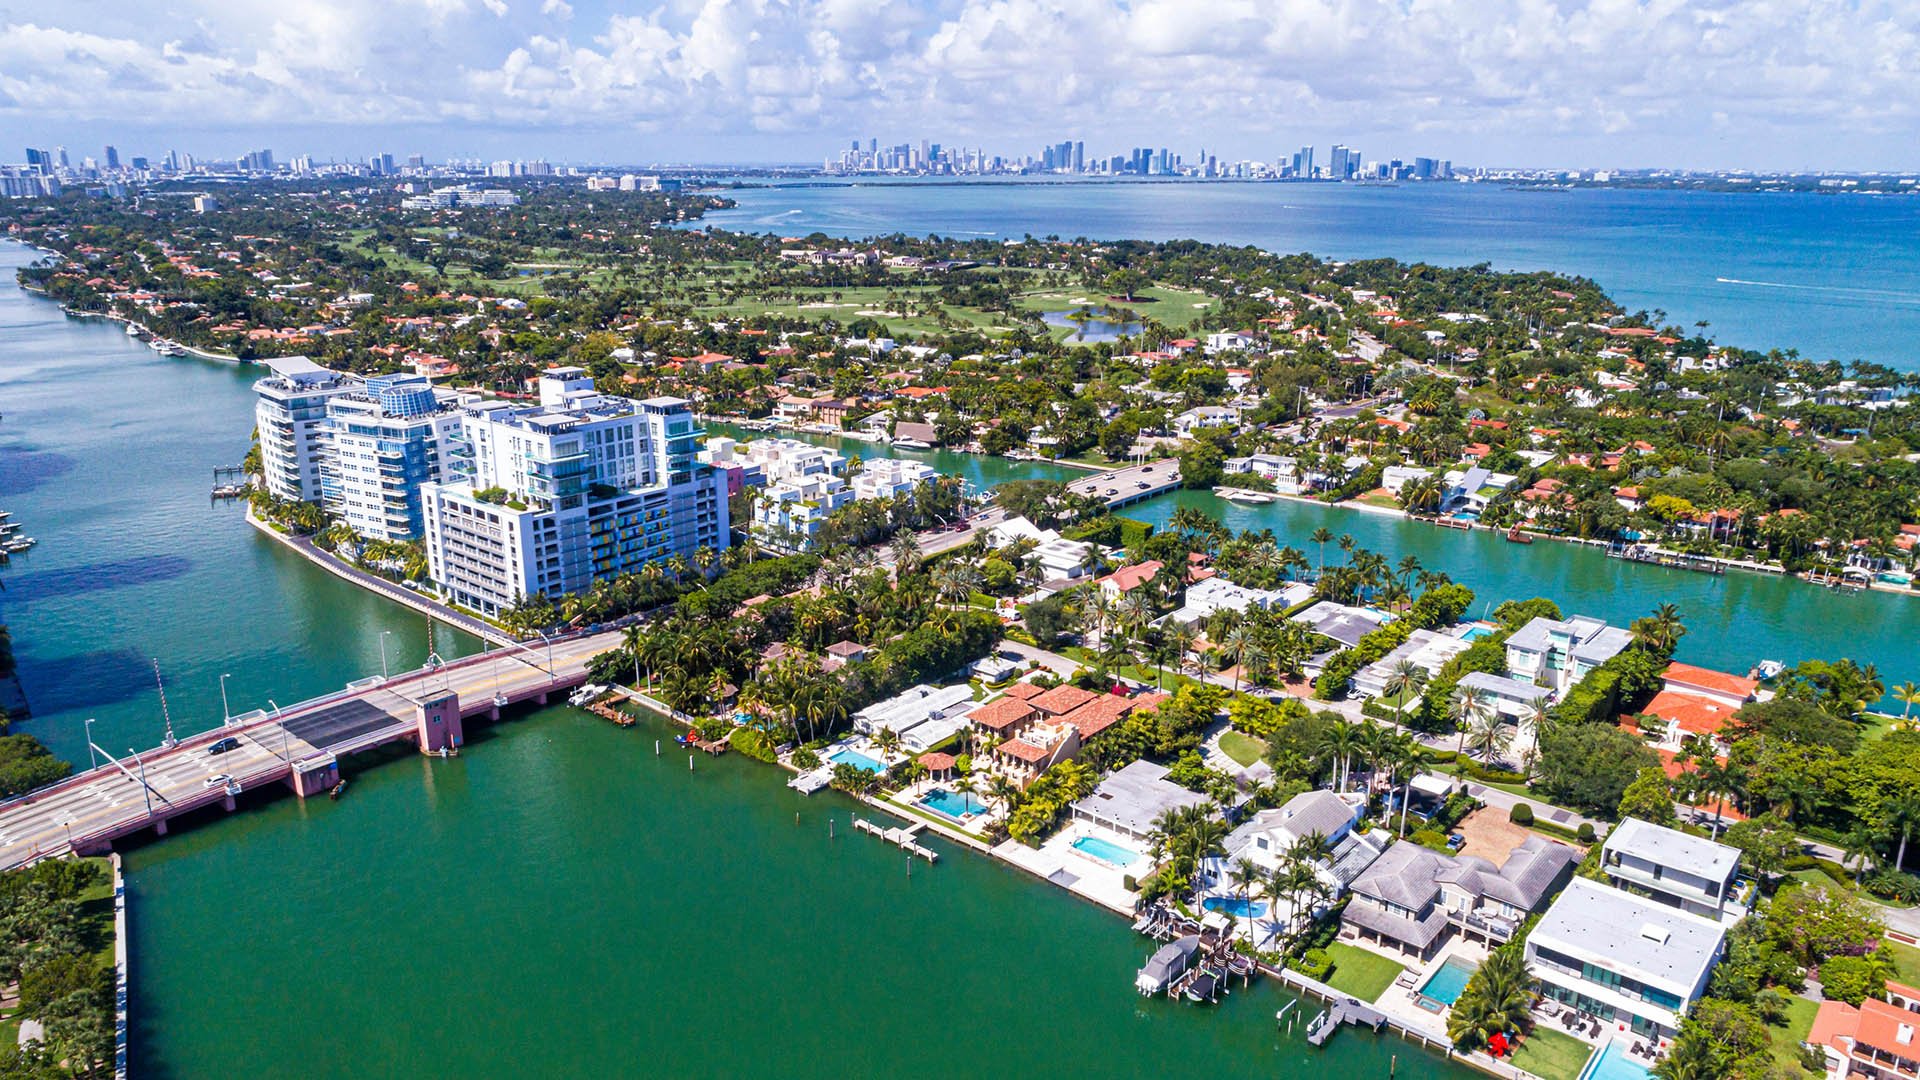
For a nonresident buyer, acquiring a South Florida residence through a U.S. entity raises three drafting questions: who can act, who bears a loss, and who receives compensation if the property changes before closing? Review the ownership vehicle alongside the purchase agreement, condominium documents, and tax classification. It is not a substitute for them.
Whether the search centers on Brickell and The Residences at 1428 Brickell or another residential setting, the protections depend on the actual transaction documents. No project-specific casualty, condemnation, or voting provisions are implied here.
The central distinction is between the right to leave the transaction and the economics of staying. A buyer may negotiate a termination right without resolving how insurance proceeds, condemnation awards, or uninsured restoration costs will be handled if closing proceeds.
A negotiated definition of a pre-closing “Taking” can encompass eminent-domain actions and proposed governmental takings, temporary or permanent. That formulation is an example, not a universal rule for residential contracts.
The drafting lesson is to look beyond a completed transfer of title. Counsel should examine whether the proposed clause captures governmental notices, threatened proceedings, temporary interference, and partial takings. These are negotiating questions, not established requirements for every purchase.
For a Miami Beach buyer considering The Perigon Miami Beach, the task is to test the purchase agreement against the buyer's intended use. Consider negotiating protection for interference with access or use rather than relying exclusively on the monetary size of an award.
Notice provisions should give the entity a workable opportunity to evaluate the event. Clarify who receives notice, what supporting documents must follow, and when the buyer must elect a remedy. Broad notice language and buyer-consent rights over settlements are proposed protections, not automatic entitlements.
A negotiated termination right can cover a taking or material casualty, with material casualty defined by restoration costs exceeding 5% of the purchase price. That percentage is an example of negotiated materiality, not a mandatory Florida threshold.
A buyer should consider whether repair cost alone captures the intended protection. A loss below a financial threshold could still disrupt the intended use of a residence. Counsel can evaluate proposed triggers tied to restoration timing, use, or uncertainty over completion without assuming those protections already exist.
The contract should distinguish the election to terminate from the election to close. For termination, review notice deadlines, the method of election, and the agreed treatment of deposits. For continued performance, negotiate restoration responsibilities, completion deadlines, and the allocation of uninsured losses or deductibles.
These are separate drafting decisions. Do not assume a general casualty paragraph resolves all of them, particularly when the buyer's authorized decision-maker is abroad.
A negotiated arrangement can provide for insurance and condemnation proceeds to be held for the purchaser's benefit and credited against the purchase price. This is not a universal rule; it illustrates why compensation needs its own provisions.
For a Sunny Isles Beach acquisition involving Bentley Residences Sunny Isles, diligence should focus on the actual agreement, not presumed protections associated with the address or brand.
If the buyer closes after a loss, consider specifying how received proceeds, pending claims, and settlement decisions will be handled. Review whether the proposed arrangement uses a price credit, an assignment of rights, or another agreed mechanism. Counsel should also examine policy terms and any relevant lender requirements before relying on that mechanism.
Investment discipline means matching the remaining restoration obligation to the money available for it. Negotiate who bears any shortfall and how the agreement avoids counting the same compensation twice.
Condominium restoration introduces a separate layer of authority. For a South Florida condominium purchase, ask counsel to examine the association's repair responsibilities and the rules governing allocation of repair or reconstruction expenses.
Do not assume a universal restoration-vote percentage. Buyers should verify current applicable law and governing documents, then identify the precise decision: repair, expense allocation, or termination of the condominium.
Review responsibility for owner-insured portions separately, including whether association-performed work could result in an assessment. Map insurance responsibilities before relying on a proposed restoration budget.
Second-home planning should include that review before closing. Ask counsel to distinguish association-insured property from owner-insured portions and examine how each category affects the proposed restoration budget.
For a South Florida condominium, review how the declaration and any applicable termination plan address insurance or condemnation proceeds not used for repair or reconstruction. Ask counsel to verify the allocation requirements under current law rather than assuming a distribution formula.
This is distinct from a seller's pre-closing promise to credit proceeds-and from distributing money within the buyer's ownership entity. Each question requires its own document review.
A buyer considering Vita at Grove Isle should maintain the same separation: examine the declaration and any relevant termination provisions, then review the entity's internal authority and distribution arrangements. Do not assume a manager can settle a claim, approve a material decision, or distribute proceeds without examining the operating agreement and applicable law.
FIRPTA generally applies to a foreign person's disposition of a U.S. real-property interest. The buyer's nonresident status alone is not the trigger. The buyer or transferee is generally the withholding agent and must determine whether the transferor is a foreign person.
Federal tax definitions include nonresident alien individuals, foreign corporations, foreign partnerships, foreign trusts, and foreign estates. Entity classification therefore matters; a U.S. entity label alone does not resolve the tax analysis.
The general withholding rate is 15% of the amount realized, subject to exceptions and special rules. Transferees generally use Forms 8288 and 8288-A to report and pay withheld tax. Have tax counsel evaluate seller status, classification, and withholding separately from the casualty and condemnation negotiations.
Before committing, ask counsel to align four matters: the events that permit termination, the economics if closing proceeds, the condominium's restoration or termination rules, and the entity's authority to act. Record proposed protections explicitly rather than treating them as standard rights.
This framework is for transaction planning, not individualized legal or tax advice. Its purpose is to preserve informed choices when circumstances change while keeping the purchase decision focused on the residence itself.
For a discreet perspective on South Florida residential opportunities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe entity does not replace the need to review purchase terms, condominium documents, and tax classification. Its authority to make decisions and distribute proceeds also requires separate review.
A negotiated clause can include proposed governmental takings, temporary or permanent. Buyers should discuss the scope with counsel rather than assume that protection is standard.
No; the 5% threshold discussed here is an example of negotiated materiality, not a mandatory Florida standard. The agreement should expressly define the applicable trigger.
A termination clause governs the option to exit. Separate provisions should address compensation and restoration obligations if the buyer instead closes.
A price credit is one possible negotiated arrangement, not a universal rule. The purchase agreement should expressly establish the agreed treatment.
Buyers should not assume a universal restoration-vote percentage. Counsel should verify current applicable law, governing documents, and the specific decision being voted on.
Ask counsel to review responsibility for owner-insured portions and whether association-performed work could result in an assessment. The analysis should use current applicable law and governing documents.
Review the declaration, any applicable termination plan, and current law to determine how unused insurance or condemnation proceeds are allocated. Keep that analysis separate from distributions within the ownership entity.
No. FIRPTA generally concerns a foreign person's disposition of a U.S. real-property interest, while the buyer or transferee generally acts as withholding agent.
The general rate is 15% of the amount realized, subject to exceptions and special rules. Transferees generally use Forms 8288 and 8288-A to report and pay the withheld tax.