
A revocable trust does not turn an all-cash acquisition into a protected mortgage transaction. For South Florida buyers, disciplined risk allocation starts by separating contractual closing arrangements from the disclosure, rate-lock, and cost-tolerance rules that apply to covered financing.
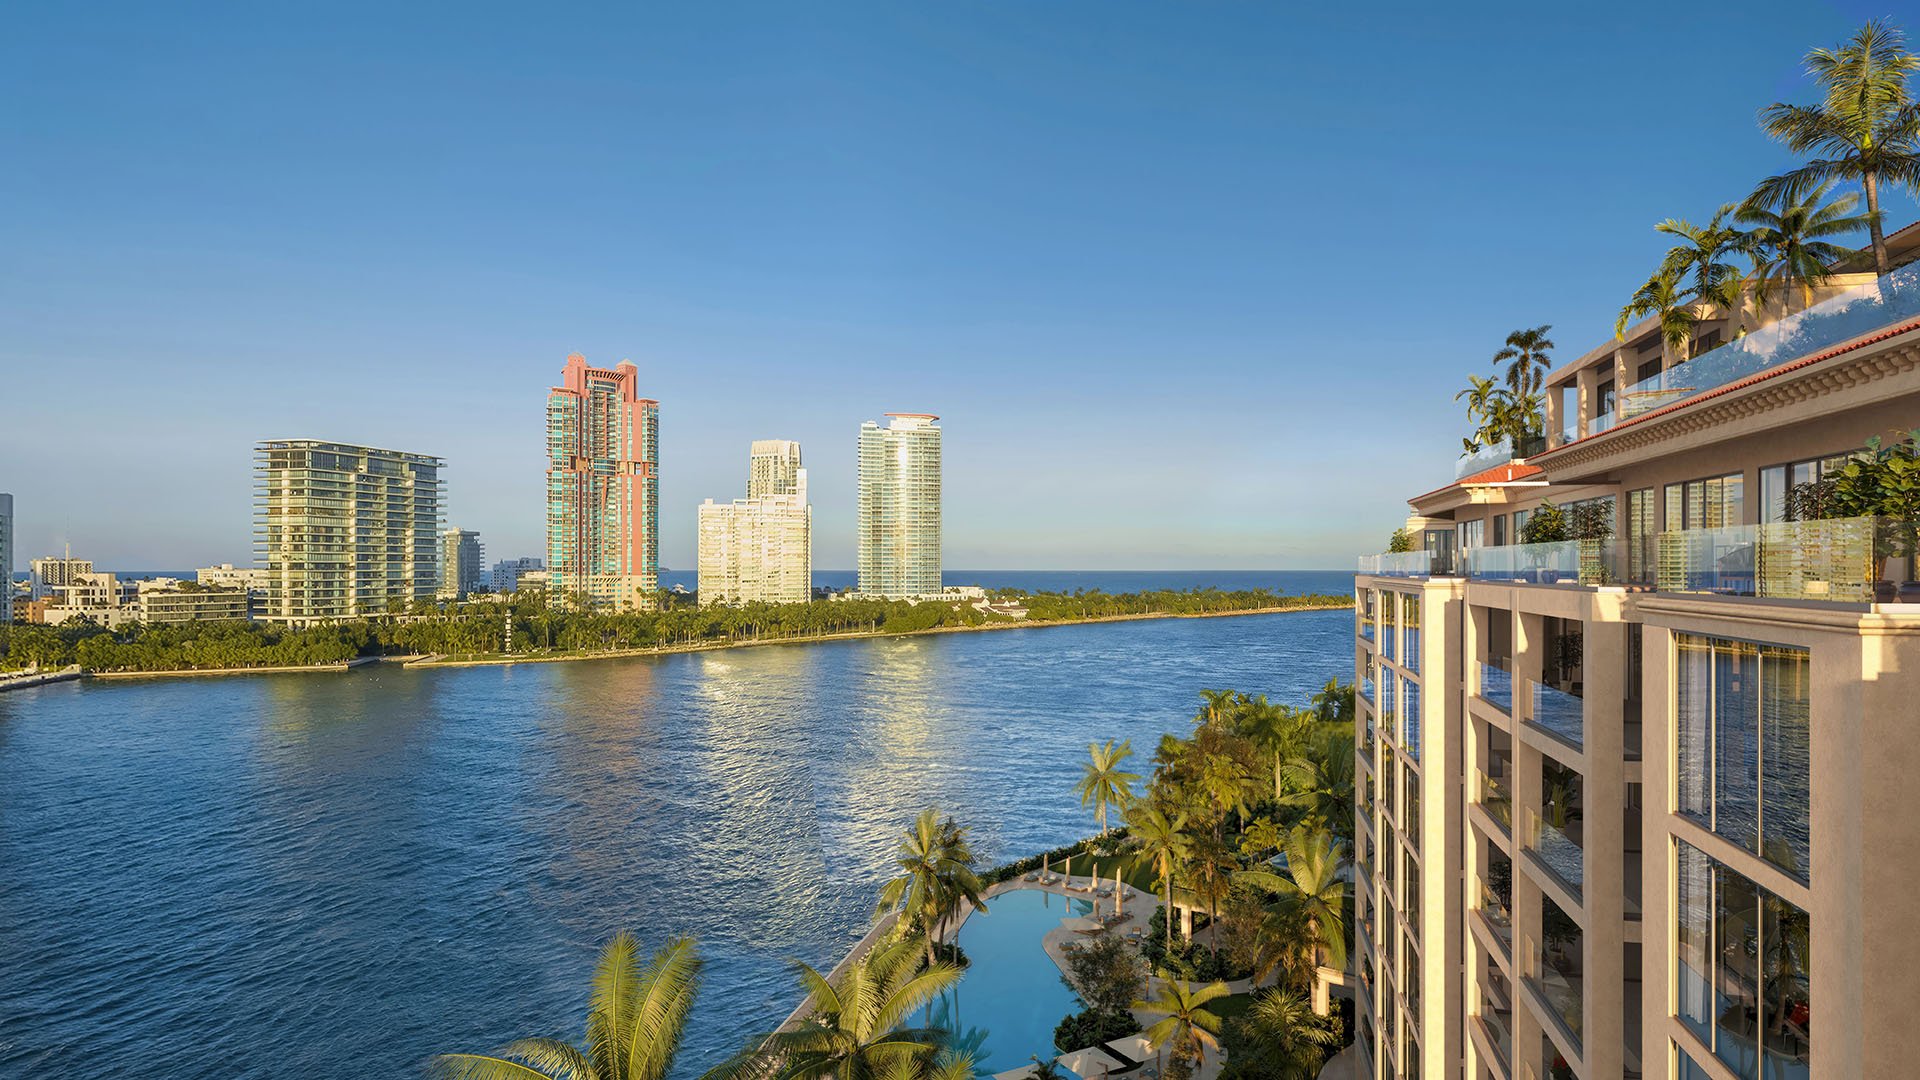
For a South Florida buyer, acquiring a residence through a revocable trust raises two distinct questions: how title will be held and how the purchase will be funded. Mortgage disclosure protections attach to a covered credit transaction, not simply to the presence of a trust.
A true cash purchase does not trigger mortgage Loan Estimate, rate-lock, or federal mortgage-cost tolerance protections.
Taking title through a revocable trust does not change that result. A cash settlement estimate should not be treated as a federally protected mortgage quote.
Whether considering Una Residences Brickell or another Brickell address, begin by identifying the intended funding route. If financing enters the transaction, assess its disclosure obligations separately from the purchase contract and trust review.
Without a covered mortgage, the task is to clarify the parties’ arrangements rather than assume lending protections apply. Ask counsel and the closing team to document the proposed title holder, required trust documentation, anticipated charges, and responsibility for resolving outstanding questions.
Request an itemized settlement estimate that identifies which amounts remain provisional. Discuss how changes will be communicated, who must approve additional services, and whether negotiated cost commitments should be recorded in writing. These are transaction-planning recommendations, not assertions of mandatory cash-purchase protections.
Timing deserves equal attention. Ask counsel to address what happens if trust review remains incomplete near closing, whether an extension mechanism is appropriate, and who would bear any agreed delay costs. Do not assume a trust-review issue creates an automatic extension, deposit remedy, or right to withdraw. Those questions require transaction-specific legal review.
For a covered mortgage, the lender generally must provide a Loan Estimate within three business days after receiving six application elements: the applicant’s name, income, Social Security number, property address, estimated property value, and requested loan amount.
The Loan Estimate provides a reference point for reviewing proposed financing. It does not, by itself, establish that the rate is locked. Read the rate-lock status and expiration information; the presence of a rate on the page is not enough.
For a buyer evaluating The Perigon Miami Beach, the same discipline applies as elsewhere in Miami Beach: keep the acquisition and financing timetables distinct, then coordinate them. A purchase deadline and a lender’s lock expiration answer different questions.
If an initially unlocked rate is subsequently locked, the lender generally must provide a revised Loan Estimate within three business days, reflecting the rate, points, lender credits, and other rate-dependent charges.
A locked rate ordinarily remains unchanged when the borrower closes within the lock period and the application does not change. It is not an unconditional promise independent of the underlying loan.
Changes to the loan amount, credit score, verified income, loan type, or closing timing can affect locked terms. Before adjusting the financing structure, ask the lender to explain the consequences for pricing and lock duration in writing.
Keep trust review separate. A rate-lock confirmation does not confirm that trust documentation and signing arrangements have been accepted. Ask the lender and counsel to confirm any applicable trustee-authority, title-vesting, and document-execution requirements. Likewise, completion of trust review does not establish rate-lock status.
A revised Loan Estimate can be legitimate. Permitted reasons for revising estimates used to determine tolerances include qualifying changed circumstances, borrower-requested changes, and a subsequent interest-rate lock.
Qualifying changed circumstances include unexpected transaction-specific events, previously relied-upon information that proves inaccurate or changes, and newly discovered information specific to the borrower or transaction. A lower-than-expected appraisal, unverifiable income, or a requested change to the loan type or down payment can lead to a revision.
To rely on a changed circumstance, the lender generally must issue the revision within three business days after receiving sufficient information to establish the event.
A revised estimate does not automatically reset every fee tolerance.
Ask what happened, when the lender obtained sufficient information, and which charges were affected. The permitted event must justify the increase, and the revision must be limited to affected charges. A new document alone is not an explanation.
For covered mortgages, closing charges fall into three broad categories. Understanding those categories is more useful than asking only whether the total closing bill increased.
Zero tolerance: Generally includes creditor, mortgage-broker, and affiliate fees; required unaffiliated services for which shopping was prohibited; and transfer taxes. Permitted revisions can affect the applicable baseline.
10% Cumulative tolerance: The test compares the combined applicable charges. It does not impose a separate 10% ceiling on each line item.
Charges permitted to vary: Some charges can change without a prescribed percentage cap when the applicable requirements are satisfied.
Request a line-by-line explanation identifying the applicable category and any valid revision. Charges exceeding an applicable tolerance can require a lender refund or another permitted cure. Disclosing an increase does not automatically make it permissible.
For a cash buyer considering Alba West Palm Beach, these mortgage categories do not cap charges on an all-cash settlement statement. In West Palm Beach as elsewhere, scrutinize the estimate while distinguishing negotiated cost arrangements from federal mortgage tolerances.
For a covered mortgage, the borrower generally must receive the Closing Disclosure at least three business days before consummation. Compare it with the Loan Estimate and any valid revisions, focusing on the interest rate, points, lender credits, and closing fees.
Not every correction starts a new waiting period. A corrected Closing Disclosure requires a new three-business-day period for specified annual percentage rate inaccuracies, a loan-product change, or the addition of a prepayment penalty. An ordinary closing-cost adjustment does not automatically restart that clock.
Ask for unresolved differences to be explained before proceeding. Retain the estimates, lock confirmation, revisions, and final disclosure so the basis for each material change remains clear.
The final review is most useful when it separates three matters: contractual purchase obligations, trust and title documentation, and any covered mortgage requirements. Each needs its own confirmation.
For cash acquisitions, concentrate on documented costs, authority, and timing arrangements. For financed acquisitions, add the disclosure timeline, lock conditions, revision explanations, and tolerance reconciliation. Have counsel assess transaction-specific rights rather than assuming one set of protections substitutes for another.
For a considered approach to South Florida residential acquisitions, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. A true cash purchase without a covered mortgage transaction does not trigger the mortgage Loan Estimate requirement, and trust ownership alone does not change that.
For a covered mortgage, generally within three business days after receiving the applicant’s name, income, Social Security number, property address, estimated property value, and requested loan amount.
No. Check the form’s rate-lock status and expiration information rather than assuming the quoted rate is secured.
A locked rate ordinarily remains unchanged if closing occurs within the lock period and the application does not change. Changes to loan amount, credit score, verified income, loan type, or closing timing can affect locked terms.
The lender generally must provide a revised Loan Estimate within three business days reflecting the rate, points, lender credits, and other rate-dependent charges.
Qualifying events include unexpected transaction-specific developments, relied-upon information that changes or proves inaccurate, and newly discovered borrower or transaction information. A lower-than-expected appraisal or unverifiable income can lead to a revised estimate.
No. Increases must be justified by a permitted event and limited to the affected charges; issuing a revised document does not automatically validate every increase.
No. It is a cumulative test of the combined applicable charges, not a separate 10% ceiling for each line item.
No. A new three-business-day waiting period is required for specified annual percentage rate inaccuracies, a loan-product change, or the addition of a prepayment penalty, not every closing-cost adjustment.
No. Ask counsel to review the purchase contract and address extension arrangements, delay costs, and any available remedies for the specific transaction.