A precise review of hurricane-season closing requirements, from contractual extensions and disclosure timing to lender credits, prepaid expenses, and the final cash-to-close calculation.
A hurricane-season closing requires two coordinated reviews: whether the signed agreement permits a change in timing, and whether the mortgage disclosure accurately reflects the transaction that will close. For a South Florida luxury buyer, moving the closing date demands more precision than moving a calendar appointment.
Hurricane season alone does not create an automatic extension. The event must meet the executed contract’s requirements, and any revised schedule must also satisfy applicable mortgage disclosure rules. A contractual extension and a federal waiting period are separate obligations.
For a buyer considering Una Residences Brickell in Brickell, the starting point is the purchase agreement, including its selections, amendments, and addenda. A residence’s address does not establish which contract provisions govern. Ask counsel to identify the controlling language before treating a postponement as permitted.
Florida residential contract provisions can address hurricanes and other force-majeure events that prevent performance or disrupt essential services, insurance, or approvals. Storm-related unavailability of required insurance may therefore affect closing, but the contractual requirements must still be satisfied.
Under the Florida force-majeure clause discussed here, affected deadlines may extend for a reasonable period, up to seven days after the event no longer prevents performance. That is not simply seven days after the original closing date. Counsel should confirm whether the signed agreement contains that language and how it applies to the interruption.
A separate provision in an August 2024 Florida residential contract example addresses unavailable lender funds caused by federal disclosure-delivery requirements. It requires Paragraph 8(b) to be checked, loan approval to have been obtained, and underwriting to be complete. The extension lasts only as long as necessary to satisfy delivery requirements, with a seven-day maximum.
Do not treat these provisions as interchangeable. One concerns an event preventing performance; the other concerns a qualifying disclosure-related funding delay. Neither example establishes the terms of a particular transaction.
Borrowers must receive the Closing Disclosure, or CD, at least three business days before closing on the mortgage loan. Confirm receipt and the permissible closing date with the lender rather than assuming the contractual date satisfies this requirement.
Only specified changes require a new three-business-day waiting period: an APR that becomes inaccurate under applicable rules, a change in loan product, or the addition of a prepayment penalty. Other settlement changes generally require a corrected CD without restarting the waiting period.
This distinction matters after a storm postponement. A revised prepaid-interest figure does not, by itself, restart the disclosure clock. Ask the lender to identify what changed and whether it triggers a new waiting period. Then align the disclosure schedule with the contractual deadline.
Cash to Close is the amount the buyer must pay at closing in addition to money already paid. It is not another name for total closing costs.
Compare the CD with the latest Loan Estimate, beginning with the loan amount, interest rate, closing costs, and explanations for changes in cash to close. Then reconcile the transaction summary against the purchase agreement and amendments. The purchase price, loan proceeds, seller credits, deposits, and adjustments must reconcile as a whole-not merely appear reasonable in isolation.
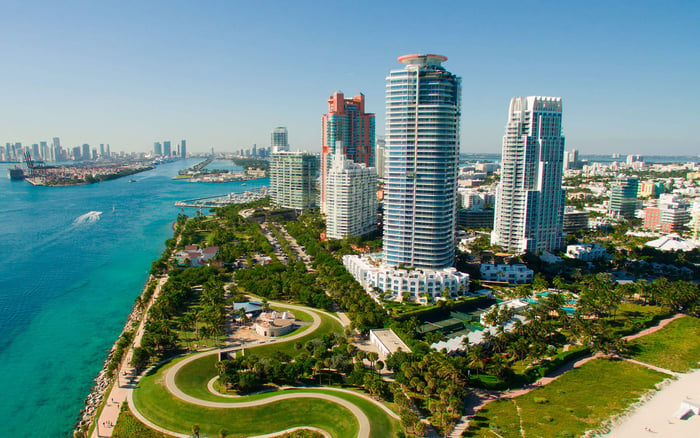
For a Miami Beach acquisition such as The Perigon Miami Beach, the same principle applies: verify the transaction’s deposit history against the disclosure. Previously delivered earnest money should appear in the cash-to-close calculation so it is not counted again.
Ask the closing team to explain discrepancies before accepting the final figure. A familiar bottom line is no substitute for a reconciled transaction.
Lender credits reduce the buyer’s closing costs. Compare the final credit with the amount shown on the Loan Estimate and request an explanation for any difference. Specific lender credits must be separately disclosed in the applicable Loan Costs or Other Costs table on page 2 of the CD.
Discount points are a different component of the financing: upfront charges paid to the lender in exchange for a lower interest rate. They appear under Origination Charges. One point equals 1% of the loan amount, so review both the percentage and the dollar charge.
Read the rate, points, and lender credits together. A rate alone does not describe the economics of an offer, and a reduced cash requirement does not explain whether the financing terms changed.
Keep seller credits distinct from lender credits during reconciliation. Do not assume a particular seller-credit limit or a right to receive unused lender credits as cash; ask the lender to confirm the treatment applicable to the loan.
Prepaid items commonly include interest from closing through month-end and the first year of homeowners insurance. Initial escrow deposits are separate: they fund an account for future expenses such as property taxes and homeowners insurance.
A changed closing date can change prepaid interest. Review the revised interest period and amount rather than carrying the original figure into the new settlement schedule. Also confirm that insurance amounts and initial escrow deposits reflect the final transaction.
For a West Palm Beach purchase, including a residence at Alba West Palm Beach, review insurance timing alongside the financial figures. Confirm whether required coverage can be placed for the intended closing; do not infer availability from the scheduled date.
For National Flood Insurance Program coverage, application and premium-payment timing at or before closing can affect the effective date and any applicable waiting period. Do not assume a universal 30-day waiting period: qualifying loan transactions receive different treatment from other new policies. Confirm the applicable effective date with the insurance and lending teams.
When closing moves, review tax, association-assessment, rent, and other applicable prorations. These date-sensitive adjustments deserve the same attention as revised lender charges.
Before accepting the final cash-to-close figure, request a coordinated check:
Counsel confirms the contractual deadline and any applicable extension.
The lender confirms disclosure timing and final loan terms.
The closing team reconciles deposits, credits, and date-sensitive adjustments.
The insurance team confirms required coverage and effective dates.
The objective is not simply to close after an interruption. It is to close on a permitted date, with consistent financing terms and a fully explained funding amount. This is a review framework, not a determination of extension rights or storm-damage remedies under an individual agreement.
For a considered approach to South Florida luxury real estate, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The event must satisfy the executed contract’s force-majeure requirements, and the signed agreement, selections, amendments, and addenda govern.
Under that clause, affected deadlines may extend for a reasonable period up to seven days after the event no longer prevents performance. It is not simply seven days after the original closing date.
The borrower must receive it at least three business days before closing on the mortgage loan. This federal requirement is separate from any contractual extension.
A new waiting period is required when the disclosed APR becomes inaccurate under applicable rules, the loan product changes, or a prepayment penalty is added. Other settlement changes generally require a corrected disclosure without restarting the period.
The August 2024 Florida contract example requires Paragraph 8(b) to be checked, loan approval obtained, and underwriting completed, with lender funds unavailable because of disclosure-delivery requirements. Its extension is limited to the time necessary, not exceeding seven days.
No. Cash to Close is the additional amount the buyer must pay at closing, accounting for the transaction’s financing, deposits, credits, and adjustments.
Compare the final credit with the Loan Estimate and ask for explanations of differences. Specific lender credits must be separately disclosed in the applicable Loan Costs or Other Costs table on page 2.
One point equals 1% of the loan amount and is an upfront lender charge paid in exchange for a lower interest rate. Check both the percentage and dollar amount under Origination Charges.
Recheck prepaid interest and closing-date-dependent tax, association-assessment, rent, and other applicable prorations. Confirm insurance amounts, coverage timing, and initial escrow deposits against the final transaction.
No. National Flood Insurance Program guidance distinguishes qualifying loan transactions from other new policies, so confirm application timing, premium payment, and the applicable effective date.